
Regions’ Intrinsic Valuation Gap and New Loan Platform Might Change The Case For Investing In RF
- Regions Financial recently reported that its Excess Returns intrinsic value estimate suggests upside while traditional market multiples appear more moderate, alongside the launch of its Regions Whole Loan Advisory platform to bolster fee and balance sheet-related earnings.
- This divergence between valuation methods, combined with the new Whole Loan Advisory business, sharpens the focus on how credit quality and loan losses could influence the bank’s longer-term earnings mix.
- Next, we’ll examine how the Regions Whole Loan Advisory launch fits into Regions Financial’s existing growth, earnings stability, and risk considerations.
Outshine the giants: these 19 early-stage AI stocks could fund your retirement.
Regions Financial Investment Narrative Recap
To own Regions Financial, you need to be comfortable with a regional bank where credit quality and loan losses sit at the center of the story, even as fee income grows. The new Whole Loan Advisory platform supports that earnings mix, but it does not change the fact that how credit costs evolve still looks like the most important near term catalyst and risk to watch.
The launch of Regions Whole Loan Advisory is the clearest tie-in here, since it aims to expand fee-based and balance sheet-related revenue streams alongside traditional lending. That matters for investors who see a stronger, more diversified earnings base as a counterweight to any future swings in loan performance or charge offs as the credit cycle develops.
Yet even with these new fee opportunities, investors should still be aware of how quickly credit losses could...
Read the full narrative on Regions Financial (it's free!)
Regions Financial's narrative projects $9.0 billion revenue and $2.4 billion earnings by 2029. This requires 7.4% yearly revenue growth and about a $0.3 billion earnings increase from $2.1 billion today.
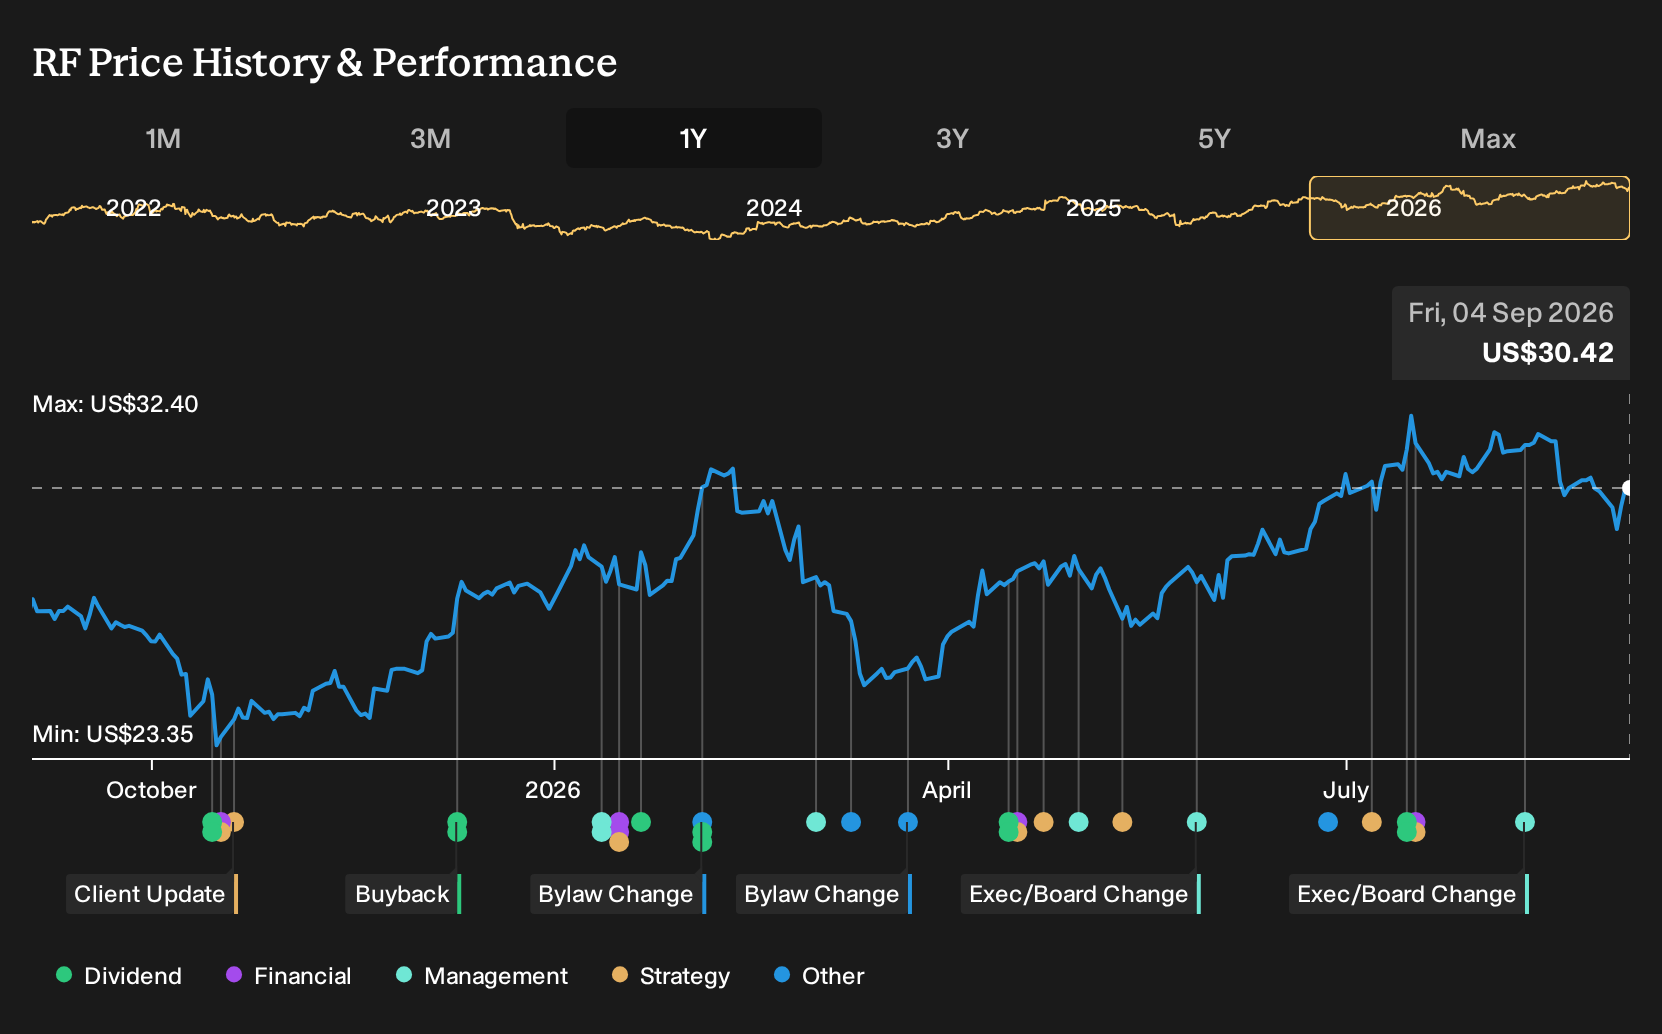
Uncover how Regions Financial's forecasts yield a $32.90 fair value, a 8% upside to its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$32.90 to US$58.39 per share, showing how far apart individual views can be. When you set those side by side with concerns about credit quality and loan losses, it becomes clear that you should weigh several perspectives before deciding how Regions’ earnings profile could evolve over time.
Explore 2 other fair value estimates on Regions Financial - why the stock might be worth just $32.90!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Regions Financial research is our analysis highlighting 3 key rewards that could impact your investment decision.
- Our free Regions Financial research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Regions Financial's overall financial health at a glance.
Ready For A Different Approach?
Our daily scans reveal stocks with breakout potential. Don't miss this chance:
- The future of work is here. Discover the 36 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
- This technology could replace computers: discover 25 stocks that are working to make quantum computing a reality.
- AI is about to change healthcare. These 38 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com