
Sempra (SRE) Reaffirms Dividend As LNG Growth Keeps Valuation In Focus
Sempra (SRE) just reaffirmed its income story, with the board declaring a $0.6575 per share quarterly dividend, payable on October 15, 2026, to shareholders of record as of September 24.
Sempra’s share price has softened over the past quarter, with a 90 day share price return decline of 6.11%, even as its 1 year total shareholder return of 9.49% and 5 year total shareholder return of 49.39% point to steadier long run momentum.
Compare Sempra’s income profile with other regulated utilities by scanning our hand picked list of 6 dividend fortresses.
Sempra now offers a softer entry price alongside a confirmed dividend stream. Does that balance still reward new risk takers at today’s valuation levels?
Most Popular Narrative: 17.4% Undervalued
Sempra’s most followed valuation storyline pegs fair value at $103.50 per share, which sits well above the recent $85.47 close and frames the latest dividend move against a richer long term earnings picture.
The rollout and completion of major LNG export projects (ECA Phase 1 nearing completion, Port Arthur Phase 1 advancing, and strong commercial momentum for Phase 2) positions Sempra to benefit from sustained global demand for U.S. LNG as a transition fuel, significantly increasing future cash flows and long-term revenue generation.
Curious what sits behind that LNG driven cash flow story? The narrative leans on a specific revenue glide path, fatter margins, and a lower future earnings multiple than today. The full set of assumptions connects those threads into that $103.50 figure.
Result: Fair Value of $103.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Sempra story only holds if regulators and lawmakers remain supportive, and if LNG assets avoid becoming expensive, underused projects as policies and demand evolve.
Find out about the key risks to this Sempra narrative.
Another View On Sempra’s Valuation
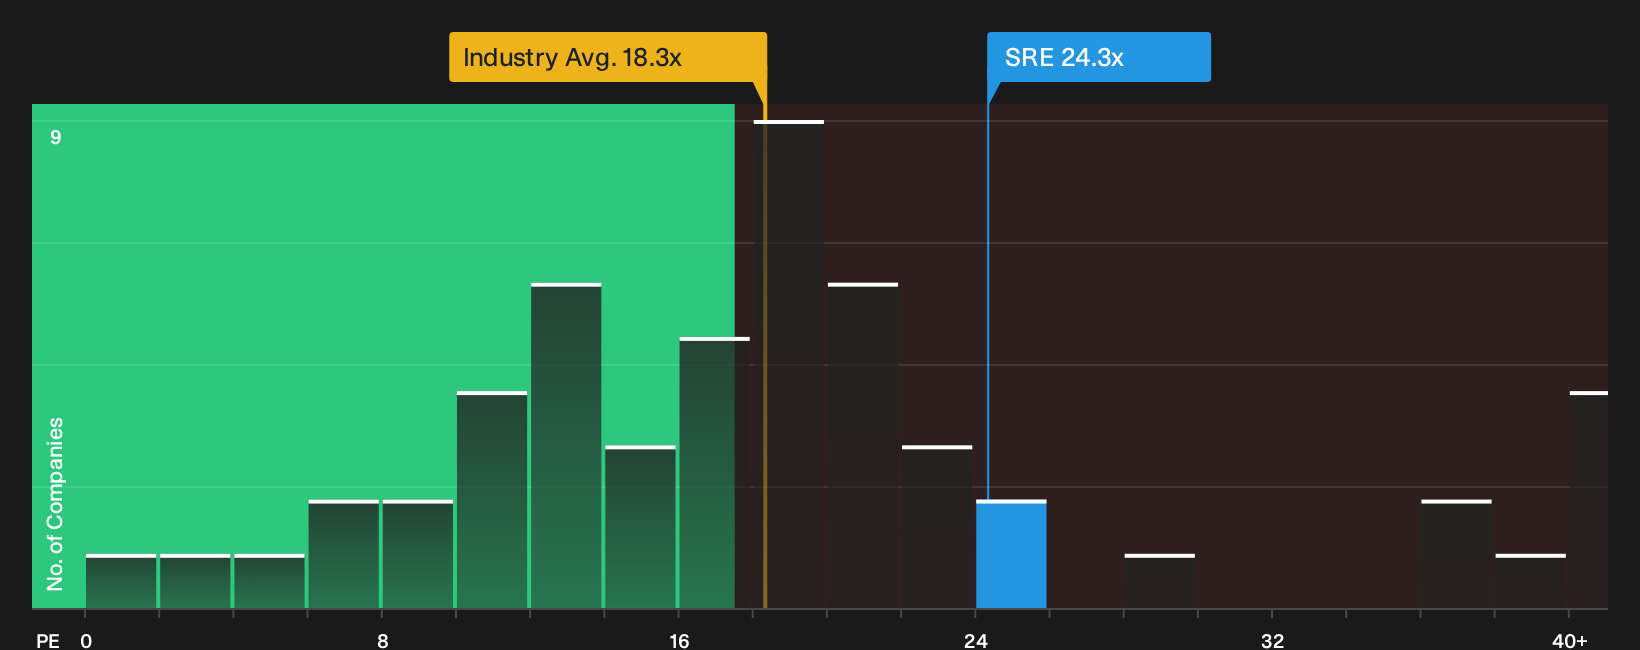
On simple earnings multiples, Sempra screens as expensive. The stock trades on a P/E of 24.7x versus 20.1x for its peers and 18.3x for the wider Integrated Utilities group. The fair ratio sits at 24.4x, which points to limited mispricing either way.
If the market eventually leans closer to that fair ratio or toward the sector averages, pricing risk appears more on the compression side than on a clear bargain. The key question is whether the income profile and LNG growth plans justify paying a premium at all.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of income support and valuation debate around Sempra can feel finely balanced. Move quickly, check the full data set, and weigh both sides of the story by reviewing the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Sempra?
If you rely only on Sempra, you risk missing other opportunities that fit your goals, so put a few minutes into widening your watchlist with targeted screens.
- Target resilient compounding potential by scanning a curated mix of quality companies on the 17 high quality undiscovered gems.
- Protect your downside first by filtering for companies with stronger finances through the list of solid balance sheet and fundamentals (24 results).
- Identify income candidates with yields that might complement Sempra by reviewing the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com