
Alaska Air Group (ALK) Faces Earnings Pressure, Is The Stock Fully Priced?
Why Alaska Air Group Earnings Expectations Matter Now
Alaska Air Group (ALK) is back under the microscope after earnings forecasts pointed to a year-over-year profit drop, even as projected sales for the upcoming quarter are higher. That tension is shaping how traders view the stock today.
Recent trading tells a cautious story for Alaska Air Group, with the share price down 14.6% over the past 30 days and 21.66% year to date. The 1-year total shareholder return has fallen 35.58%, while the 3-year total shareholder return is slightly positive. This hints that investors are reassessing both earnings risk and any longer term recovery narrative around the US$40.36 share price.
Compare Alaska Air Group's recent selloff and earnings pressure with a curated set of other carriers and travel plays that still screen for resilience using our list of solid balance sheet and fundamentals (24 results).
Alaska Air Group has sold off sharply, while analyst fair value estimates still point much higher. With that gap now wide open, how much of the earnings risk already appears priced in?
Most Popular Narrative: 9.1% Overvalued
Alaska Air Group's most followed valuation storyline pegs fair value at $37.00, which sits below the recent $40.36 close and frames the current earnings debate.
The assumed bearish price target for Alaska Air Group is $37.0, which represents up to two standard deviations below the consensus price target of $61.28. This valuation is based on what can be assumed as the expectations of Alaska Air Group's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
Read the complete narrative. Read the complete narrative.
The fair value story around Alaska Air Group leans heavily on a sharp swing from current losses to sizeable profits, paired with upgraded margins and a richer earnings multiple. This raises the question of which specific revenue path and profit profile would need to fall into place to justify that shift in valuation.
Result: Fair Value of $37.00 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, higher fuel costs and recent net losses could quickly challenge the Alaska Air Group recovery script if cost pressure lingers or demand softens further.
Find out about the key risks to this Alaska Air Group narrative.
Another View on Alaska Air Group Valuation
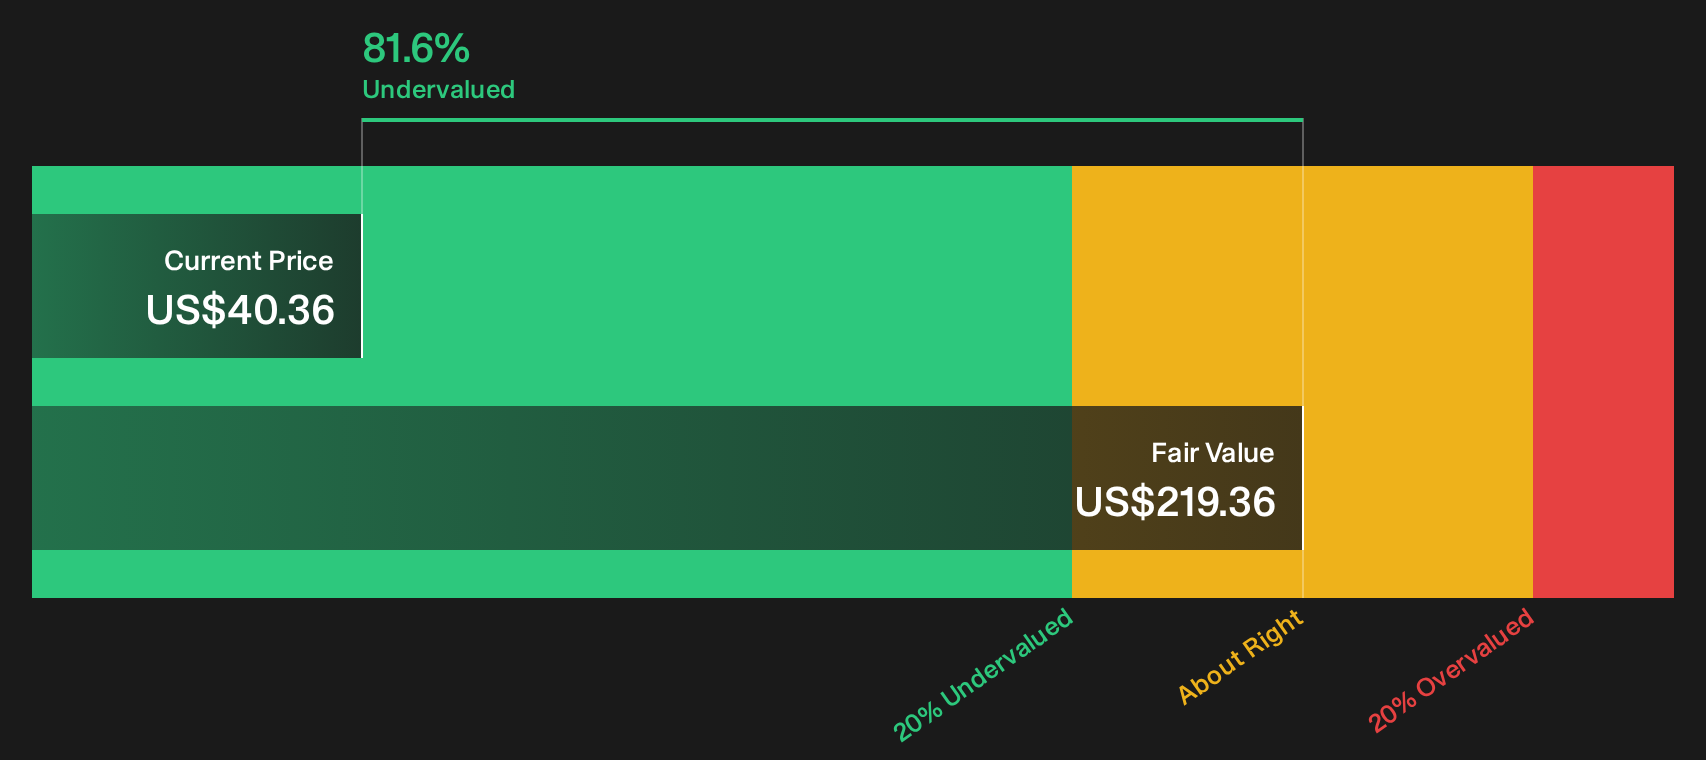
The bearish fair value of $37.00 frames Alaska Air Group as modestly overvalued, yet the SWS DCF model presents a very different picture. On that cash flow view, ALK at $40.36 trades around 81.6% below an estimated value of $219.36. This raises a simple question: Which story do you trust more, the narrative around earnings risk or the long term cash generation implied by our DCF model?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed about what all this means for Alaska Air Group right now? Take a closer look at the underlying data and weigh the 3 key rewards and 1 important warning sign.
Looking for more Alaska Air Group investment ideas?
If Alaska Air Group is on your radar, do not stop here. Broader ideas from the Simply Wall St screener could highlight opportunities you would otherwise miss.
- Tap into potential value by reviewing quality companies that currently look underpriced using our 31 high quality undervalued stocks.
- Target resilience and sleep better at night by focusing on businesses with strong finances through the 10 resilient stocks with low risk scores.
- Spot early-stage opportunities with solid fundamentals before they are widely talked about by scanning the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com