
3 Global Growth Companies With Insider Ownership Expecting Up To 81% Profit Growth
In recent weeks, global markets have experienced mixed performances as geopolitical tensions and fluctuating energy prices weigh on investor sentiment. Despite these uncertainties, growth stocks have managed to outperform their value counterparts, highlighting the potential opportunities in sectors driven by innovation and expansion. In this context, companies with high insider ownership can be particularly appealing as they often demonstrate strong alignment between management and shareholder interests, making them noteworthy contenders in an unpredictable market environment.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 126% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| Meitu (SEHK:1357) | 22.9% | 30.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| CD Projekt Red (WSE:CDR) | 35.2% | 43.4% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's uncover some gems from our specialized screener.
Metis TechBio (SEHK:7666)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Metis TechBio Co., Ltd. focuses on the research and development of AI-empowered nanomaterials for delivering active agents across carbon-based life forms in Chinese Mainland and the United States, with a market cap of HK$21.73 billion.
Operations: The company generates revenue of CN¥258.15 million from its research and development activities in new nano materials.
Insider Ownership: 23.2%
Earnings Growth Forecast: 82% p.a.
Metis TechBio demonstrates strong growth potential with forecasted revenue growth of 26.7% annually, outpacing the Hong Kong market. Despite recent volatility in its share price, the company is expected to become profitable within three years. Recent earnings showed significant sales increase to CNY 154.29 million, though net loss remains high at CNY 153.21 million. The deployment of their AI-driven NanoForge platform highlights ongoing innovation and commercialisation efforts in drug formulation development.
- Click to explore a detailed breakdown of our findings in Metis TechBio's earnings growth report.
- The valuation report we've compiled suggests that Metis TechBio's current price could be inflated.

Suzhou Dongshan Precision Manufacturing (SZSE:002384)
Simply Wall St Growth Rating: ★★★★★★
Overview: Suzhou Dongshan Precision Manufacturing Co., Ltd. manufactures and sells components for computer, communication, and electronic equipment both in China and internationally, with a market cap of CN¥357.37 billion.
Operations: The company's revenue is primarily derived from Electronic Circuit Products (CN¥27.09 billion), Precision Component Products (CN¥10.15 billion), and Optoelectronic Display Modules (CN¥5.66 billion).
Insider Ownership: 33.5%
Earnings Growth Forecast: 75.5% p.a.
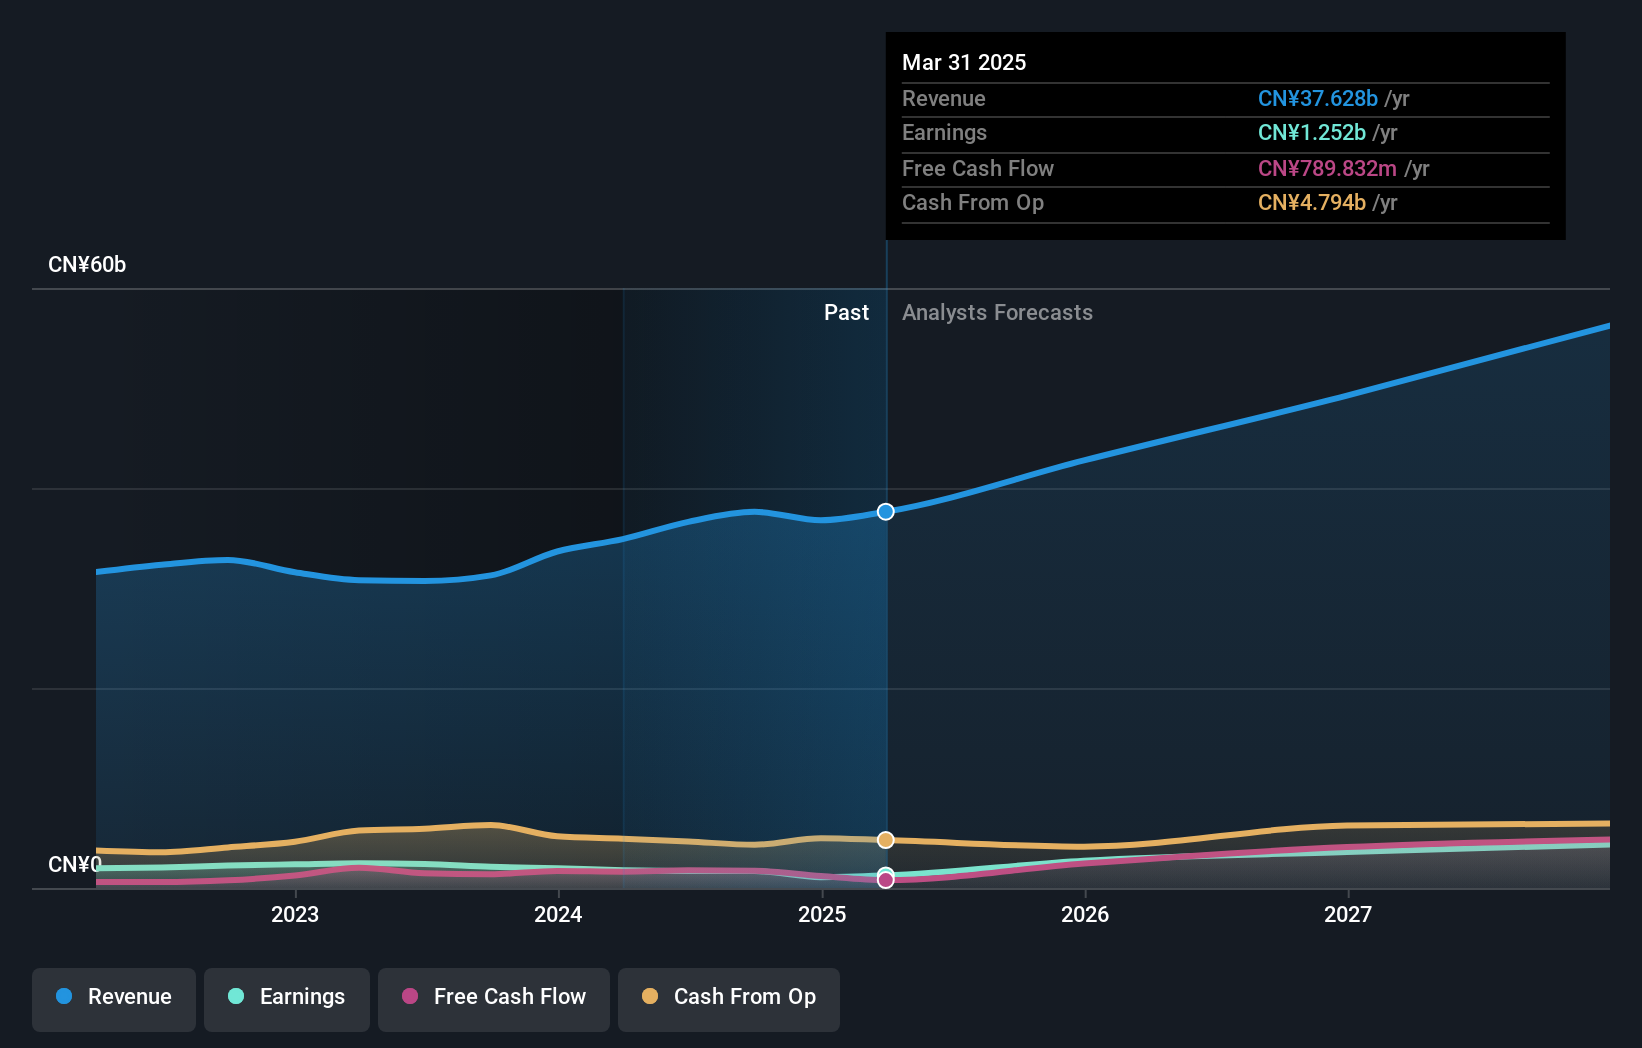
Suzhou Dongshan Precision Manufacturing shows robust growth potential with forecasted revenue growth of 42.5% annually, significantly outpacing the Chinese market. Despite recent share price volatility, its earnings are expected to grow substantially at 75.5% per year over the next three years. The company reported impressive half-year results with net income rising to CNY 2.96 billion from CNY 758 million a year ago and announced a share repurchase program worth up to CNY 300 million for employee incentives and equity plans.
- Click here and access our complete growth analysis report to understand the dynamics of Suzhou Dongshan Precision Manufacturing.
- Our valuation report unveils the possibility Suzhou Dongshan Precision Manufacturing's shares may be trading at a premium.
JX Advanced Metals (TSE:5016)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: JX Advanced Metals Corporation develops, manufactures, and sells materials made from copper and rare metals in Japan with a market cap of ¥3.72 billion.
Operations: The company generates revenue from the development, manufacturing, and sale of copper and rare metal materials in Japan.
Insider Ownership: 13%
Earnings Growth Forecast: 13.3% p.a.
JX Advanced Metals is positioned for moderate growth, with earnings expected to increase by 13.3% annually, surpassing the JP market's average. Despite a volatile share price, the stock trades below its estimated fair value. Recent guidance revisions highlight improved revenue and profit forecasts due to strong demand in AI data centers and favorable exchange rates. The company completed a significant share buyback but reduced its year-end dividend from JPY 25.00 to JPY 10.00 per share.
- Navigate through the intricacies of JX Advanced Metals with our comprehensive analyst estimates report here.
- According our valuation report, there's an indication that JX Advanced Metals' share price might be on the expensive side.

Make It Happen
- Dive into all 724 of the Fast Growing Global Companies With High Insider Ownership we have identified here.
- Looking For Alternative Opportunities? These 23 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com