
Should Income Investors Look At Altria Group, Inc. (NYSE:MO) Before Its Ex-Dividend?
Some investors rely on dividends for growing their wealth, and if you're one of those dividend sleuths, you might be intrigued to know that Altria Group, Inc. (NYSE:MO) is about to go ex-dividend in just 4 days. Typically, the ex-dividend date is one business day before the record date, which is the date on which a company determines the shareholders eligible to receive a dividend. The ex-dividend date is of consequence because whenever a stock is bought or sold, the trade takes at least one business day to settle. Accordingly, Altria Group investors that purchase the stock on or after the 15th of September will not receive the dividend, which will be paid on the 9th of October.
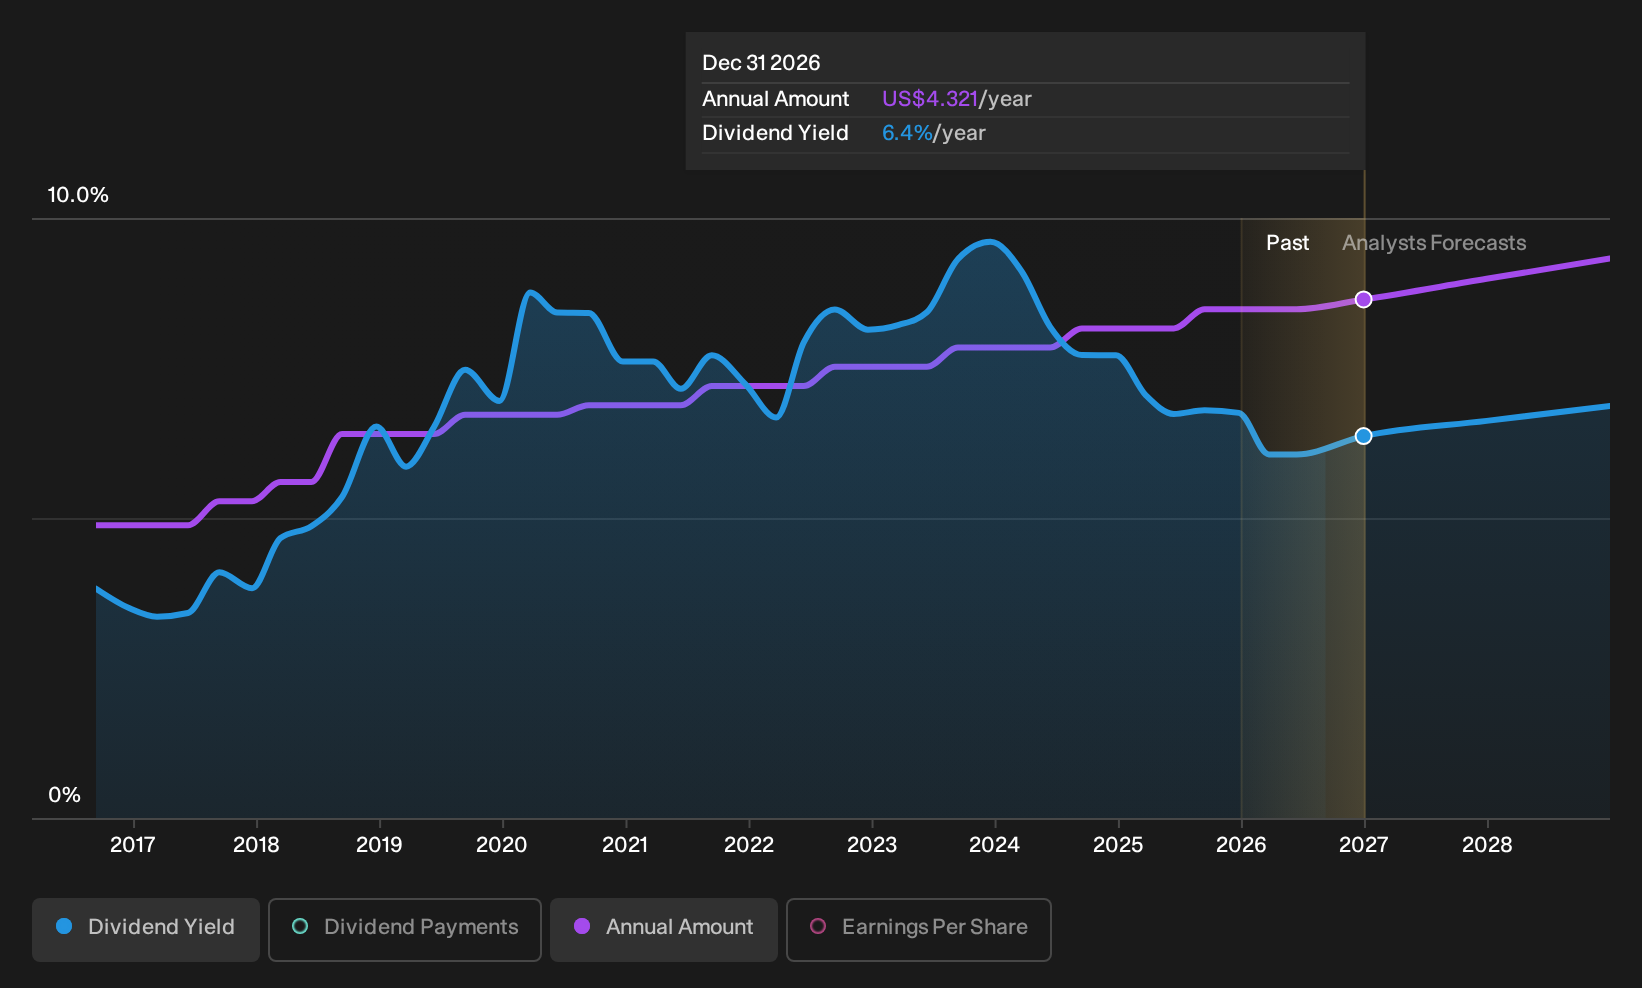
The company's next dividend payment will be US$1.11 per share. Last year, in total, the company distributed US$4.24 to shareholders. Last year's total dividend payments show that Altria Group has a trailing yield of 6.2% on the current share price of US$67.89. We love seeing companies pay a dividend, but it's also important to be sure that laying the golden eggs isn't going to kill our golden goose! So we need to check whether the dividend payments are covered, and if earnings are growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Its dividend payout ratio is 89% of profit, which means the company is paying out a majority of its earnings. The relatively limited profit reinvestment could slow the rate of future earnings growth. It could become a concern if earnings started to decline. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. Over the last year, it paid out more than three-quarters (78%) of its free cash flow generated, which is fairly high and may be starting to limit reinvestment in the business.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Altria Group
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. For this reason, we're glad to see Altria Group's earnings per share have risen 15% per annum over the last five years. It paid out more than three-quarters of its earnings in the last year, even though earnings per share are growing rapidly. We're surprised that management has not elected to reinvest more in the business to accelerate growth further.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. Since the start of our data, 10 years ago, Altria Group has lifted its dividend by approximately 6.5% a year on average. It's encouraging to see the company lifting dividends while earnings are growing, suggesting at least some corporate interest in rewarding shareholders.
Final Takeaway
Is Altria Group worth buying for its dividend? It's good to see earnings are growing, since all of the best dividend stocks grow their earnings meaningfully over the long run. However, we'd also note that Altria Group is paying out more than half of its earnings and cash flow as profits, which could limit the dividend growth if earnings growth slows. Overall, it's hard to get excited about Altria Group from a dividend perspective.
While it's tempting to invest in Altria Group for the dividends alone, you should always be mindful of the risks involved. In terms of investment risks, we've identified 2 warning signs with Altria Group and understanding them should be part of your investment process.
If you're in the market for strong dividend payers, we recommend checking our selection of top dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.