
How Investors Are Reacting To Intuitive Machines (LUNR) New Platform Contract
- Intuitive Machines announced that it previously secured a contract to build two IM 300 series spacecraft platforms for a new, undisclosed customer, opening an additional use case for its Palo Alto high volume satellite production facility.
- The award signals fresh demand for configurable IM 300 platforms that can be turned around on compressed timelines without interrupting existing customer programs. This development highlights Intuitive Machines' manufacturing scalability.
- We will look at how this new IM 300 contract and added market segment contribute to Intuitive Machines' broader investment narrative.
Scan other space and satellite players moving fast on configurable hardware by checking our curated list of 17 high quality undiscovered gems alongside Intuitive Machines' latest contract win.
Intuitive Machines Investment Narrative Recap
To own Intuitive Machines, you need to believe the company can turn complex space hardware into repeatable, higher volume services. The IM 300 satellite platforms are one piece of that story. This new contract points to incremental demand for configurable spacecraft that fit inside the existing Palo Alto line, which helps utilization without stretching the footprint. In the near term, the key swing factor still sits with execution on large government programs and lunar missions. The biggest risk remains the combination of ongoing losses, heavy fixed costs, and lumpy, milestone based revenue.
The most relevant backdrop to this IM 300 award is Intuitive Machines' push into vertically integrated satellite and lander manufacturing. That move has raised fixed costs and execution risk, yet it is also what makes a high volume facility in Palo Alto possible. The new order shows that management is at least finding commercial customers to put through that factory, which matters if you worry about underused capacity. It does not change the fact that the business is still unprofitable and that cash burn, contract timing, and facility utilization remain key near term catalysts.
Even so, there is a specific pressure point in the Intuitive Machines story that deserves a closer look before getting too comfortable with these new contracts...
Read the full Intuitive Machines narrative to see the case behind these numbers.
Intuitive Machines' analyst narrative points to revenues of US$1.5b and earnings of US$62.2 million by 2029, based on an assumed 63.6% yearly revenue growth rate and an earnings change of about US$172.1 million from a loss of US$109.9 million today to the forecast profit level.
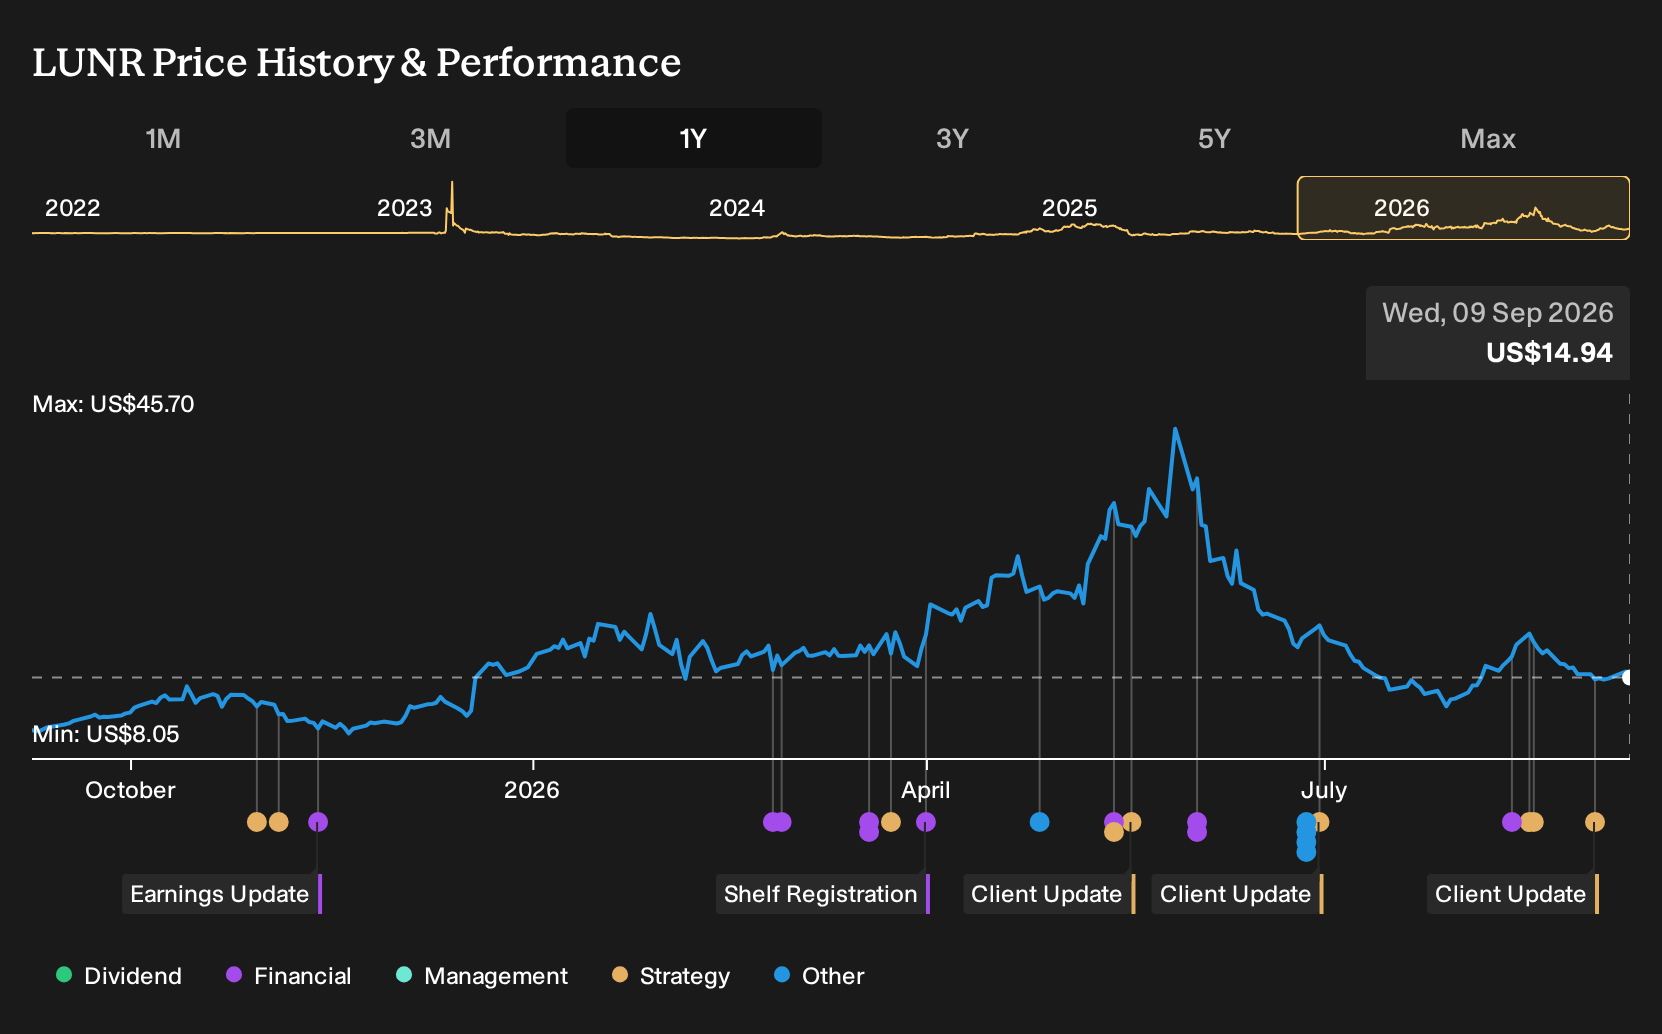
Intuitive Machines' forecasts point to fair value of $40.78 against a $14.94 share price, a 173% upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Intuitive Machines as a potential deep space communications powerhouse, not just a lunar contractor. Before this IM 300 contract, that group was already modeling about US$1.4b of revenue and US$127.4 million of earnings by 2029. You can now compare those upbeat assumptions with this fresh satellite win and decide whether their story still fits.
If you want a broader sanity check on where Intuitive Machines might sit on price versus expectations, review the 10 other fair value estimates for Intuitive Machines.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and research.
- A great starting point for your Intuitive Machines research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Intuitive Machines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuitive Machines' overall financial health at a glance.
Looking for more investment ideas beyond Intuitive Machines?
Once you have a view on Intuitive Machines, it often helps to compare it with other listed businesses that share similar qualities or offer a very different risk profile. The Simply Wall St Screener can surface companies that match the factors you care about most, so you can build a watchlist that actually reflects your own approach.
- If you want to hunt for companies that the market may be pricing cautiously, start with a focused set of 31 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- For investors who care most about balance sheet strength and financial resilience, filter for a list of solid balance sheet and fundamentals (24 results) and compare how they stack up next to Intuitive Machines.
- If you are searching for ideas off the beaten path, scan a curated group of 17 high quality undiscovered gems that might not yet be widely followed but still show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com