
Franco-Nevada (TSX:FNV) Posts Record First Half Results, Is The Stock Fully Valued?
Franco-Nevada (TSX:FNV) just reported record first half results, supported by firm precious metal and oil prices, while staying debt free and keeping about $4.3b available for new royalty and streaming deals.
The record first half has landed alongside strong share price momentum, with Franco-Nevada’s stock at CA$367.13 and a 30-day share price return of 9.45%. The 1-year total shareholder return of 34.37% and 3-year total shareholder return of 98.21% point to investors steadily rewarding the royalty model.
Scan other royalty driven miners and precious metal players showing similar momentum with our curated list of 35 elite gold producer stocks for context alongside Franco-Nevada.
Franco-Nevada has rallied hard and still trades at a small discount to analyst targets, even though a simple fair value model flags it as rich. Is that market caution misplaced, or exactly right at this stage?
Most Popular Narrative: 4.4% Undervalued
Franco-Nevada’s most followed valuation story pegs fair value at about CA$384 per share, slightly above the latest close at CA$367.13, which puts a small cushion between narrative and market pricing.
The company's strong balance sheet, high cash flow generation, and conservative financial management position it to capitalize on market dislocations and seize attractive, distressed or strategic royalty/streaming deals, enabling compounding returns and supporting higher net margins over time.
Want to see what sits behind that confidence in Franco-Nevada? The narrative leans on a specific mix of projected revenue expansion, margin strength, and a premium future earnings multiple that looks more like a growth stock than a traditional miner.
Result: Fair Value of CA$384.02 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, analyst assumptions could be knocked off course by weaker gold prices or setbacks at key assets like Cobre Panama and Candelaria that reduce royalty inflows.
Find out about the key risks to this Franco-Nevada narrative.
Another View: Franco-Nevada Looks Expensive On Earnings
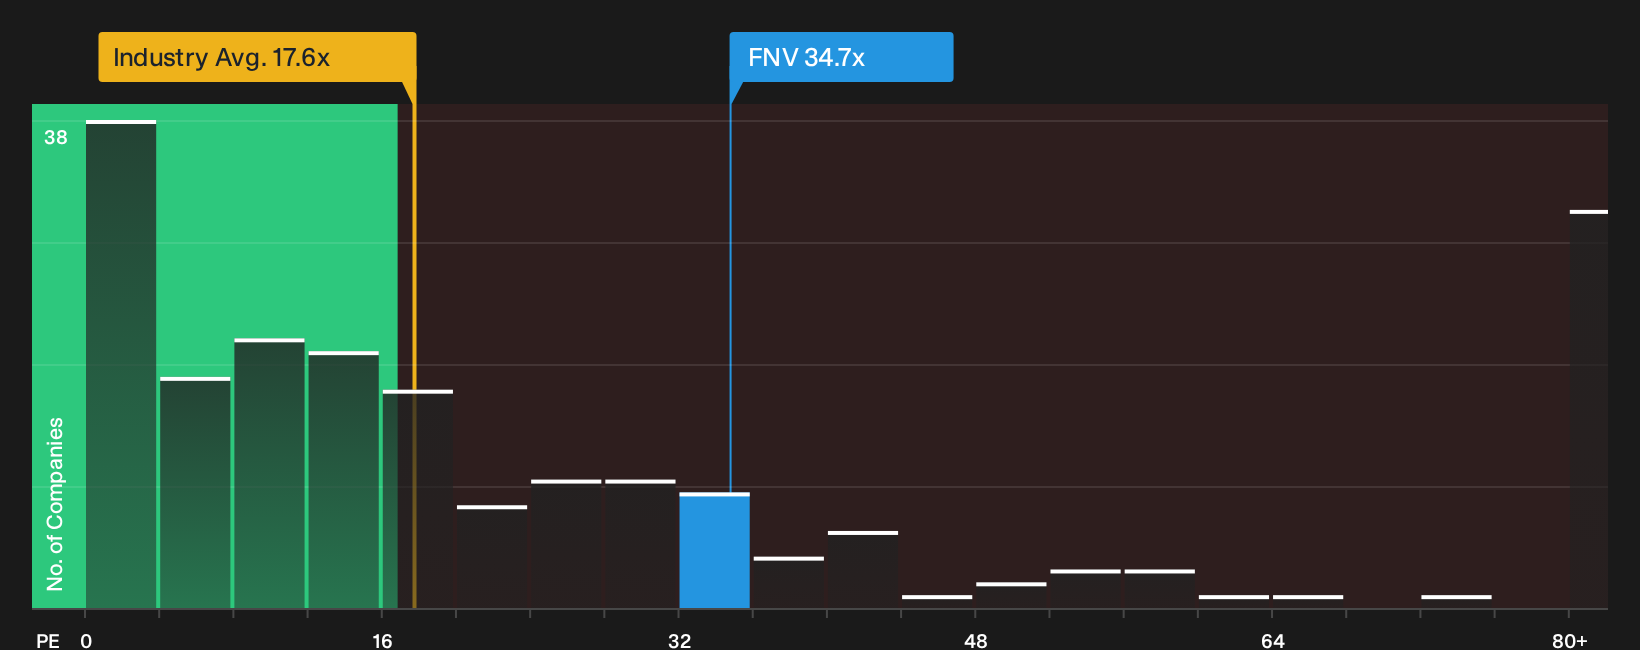
That 4.4% “undervalued” narrative bumps into a very different signal once the focus shifts to earnings. On a P/E of 34.7x, Franco-Nevada trades at roughly double the Canadian Metals and Mining industry on 17.6x and well above peers at 18.3x, while the fair ratio points closer to 18.8x. That creates meaningful valuation risk if sentiment or growth expectations cool from here.
It is worth seeing how those earnings based signals stack up against the rest of the valuation work in our breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Franco-Nevada is split. This is exactly when fresh eyes matter most, so move quickly, review the full data set, and weigh the 2 key rewards
Looking for more investment ideas beyond Franco-Nevada?
If Franco-Nevada has sharpened your focus, put that energy to work and line up your next ideas using targeted screens on Simply Wall St’s tools.
- Zero in on value opportunities before the crowd spots them by scanning our 7 high quality undervalued stocks that pair quality fundamentals with attractive pricing.
- Build a sturdier portfolio core by reviewing a list of solid balance sheet and fundamentals (7 results) that can better handle shocks when conditions change.
- Spot potential future leaders early by sifting through 9 high quality undiscovered gems with strong numbers but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com