
3 Reasons to Avoid DLTR and 1 Stock to Buy Instead
Dollar Tree has been treading water for the past six months, recording a small return of 2% while holding steady at $119.10. The stock also fell short of the S&P 500’s 13.1% gain during that period.
Is there a buying opportunity in Dollar Tree, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Dollar Tree Not Exciting?
We’re sitting this one out for now. Here are three reasons you should be careful with DLTR, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
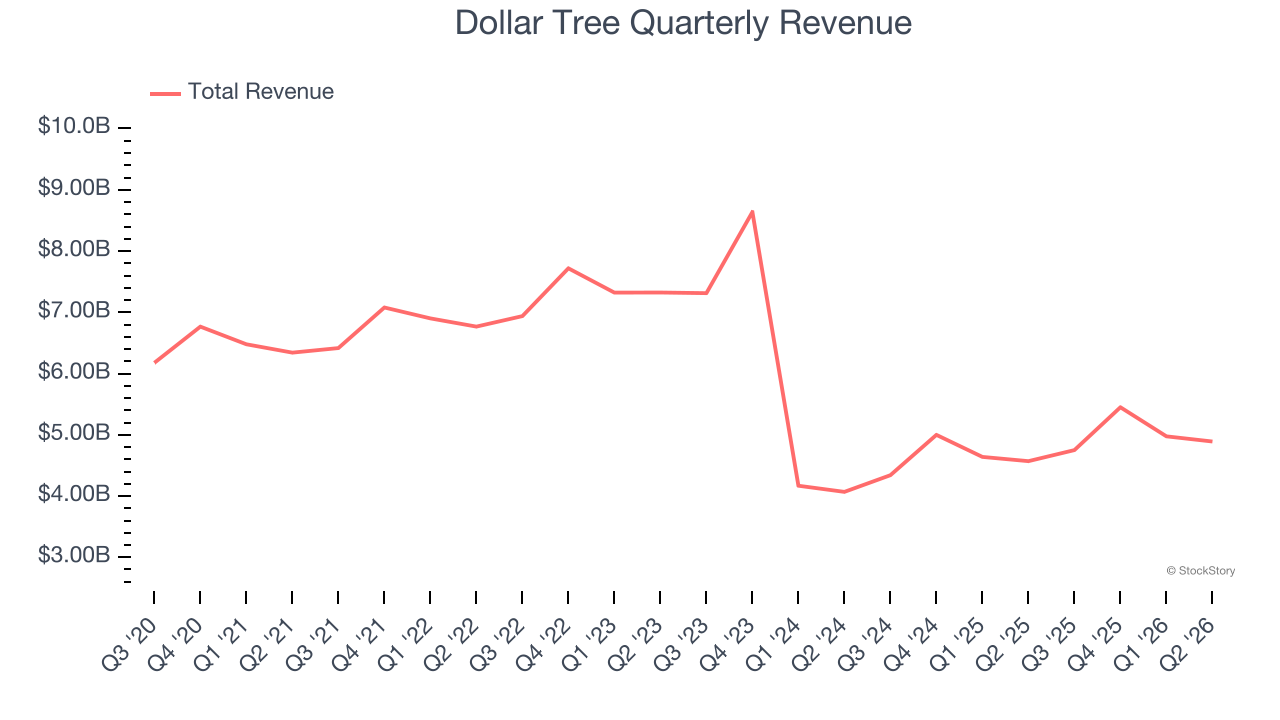
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last three years, Dollar Tree’s demand was weak and its revenue declined by 11.9% per year. This wasn’t a great result and signals it’s a lower quality business.
2. Low Gross Margin Reveals Weak Structural Profitability
We prefer higher gross margins because they not only make it easier to generate more operating profits but also indicate product differentiation, negotiating leverage, and pricing power.
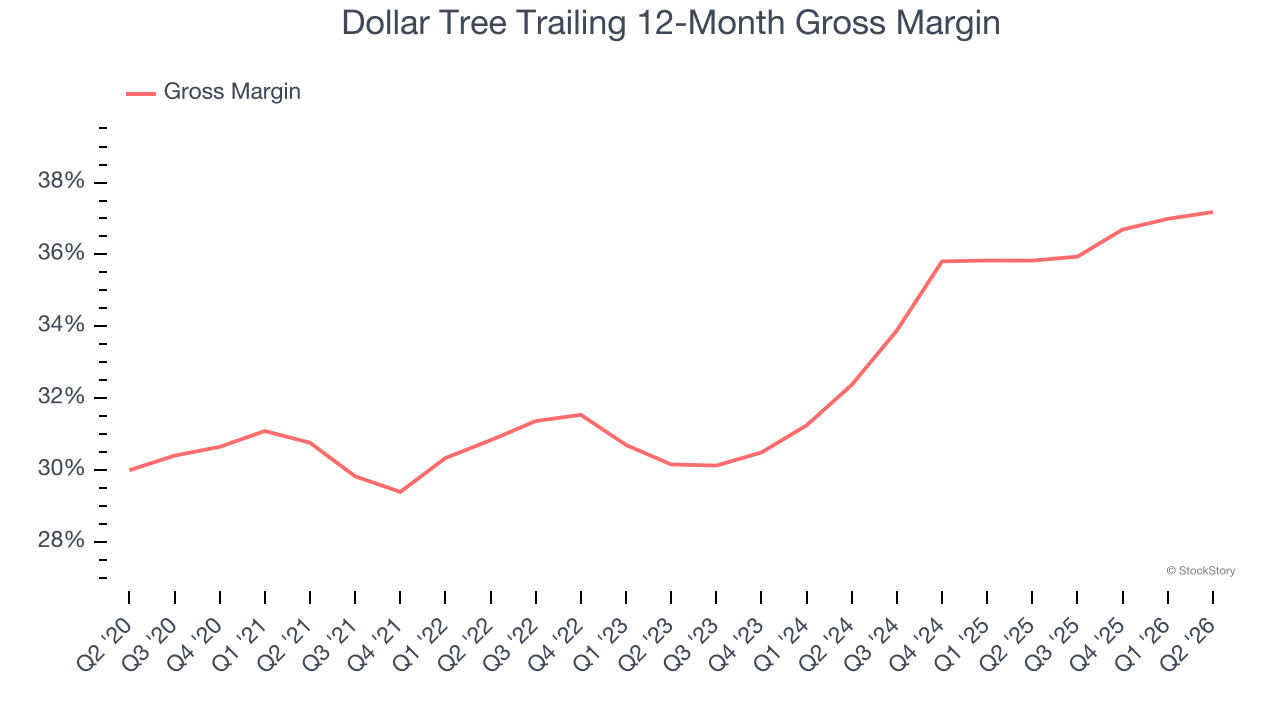
Dollar Tree has bad unit economics for a retailer, giving it less room to reinvest and grow its presence. As you can see below, it averaged a 36.5% gross margin over the last two years. That means Dollar Tree paid its suppliers a lot of money ($63.47 for every $100 in revenue) to run its business.
3. Previous Growth Initiatives Haven’t Impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Dollar Tree historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 6.9%, somewhat low compared to the best consumer retail companies that consistently pump out 30%+.
Final Judgment
Dollar Tree isn’t a terrible business, but it doesn’t pass our bar. With its shares underperforming the market lately, the stock trades at 18× forward P/E (or $119.10 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. Let us point you toward the Amazon and PayPal of Latin America.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.