
Will Flow Battery Tie Up Change ENEOS Stock Narrative
- In September 2026, XL Batteries announced an MOU with ENEOS Holdings to work on low cost, safe, scalable organic flow batteries for grid scale storage, starting with a joint feasibility study to assess long term commercial deployment.
- The focus on non toxic, abundant electrolytes gives ENEOS Holdings direct exposure to long duration storage technology that targets financing, safety, and real world deployment hurdles for large energy projects.
- Next, the analysis looks at how ENEOS Holdings’ push into organic flow batteries could influence its longer term investment narrative.
Scan grid-scale storage opportunities around ENEOS Holdings by comparing it with our hand picked 39 power grid technology and infrastructure stocks as transmission, storage, and flexibility needs expand.
ENEOS Holdings Investment Narrative Recap
For anyone holding ENEOS Holdings, the core belief is that a mature hydrocarbons group can gradually lean into power, gas, and storage while managing earnings swings tied to resource prices and timing effects. Recent profitability sits alongside analyst expectations for earnings and revenue to decline over the next few years, so the near term focus stays on stabilising cash flows and keeping refinery and power operations efficient. The XL Batteries MOU does not materially change that near term picture. The bigger immediate risk still sits in commodity prices, exchange rates, and the thinner contribution from JX Advanced Metals.
The XL Batteries agreement sits alongside earlier moves such as the Goi Thermal Power Plant ramp up and entry into the VPP supply demand balancing market. Together, these steps extend ENEOS Holdings further into electricity and storage where operational uptime, safety performance, and contract quality matter more than headline capacity. For you as a shareholder, the interest is in whether newer power and storage activities can play a larger role in offsetting volatility in petroleum products and exploration and production earnings without creating fresh execution or capex pressures.
Even so, the cleaner long term story around ENEOS Holdings and grid scale storage still has to contend with ...
Read the full ENEOS Holdings narrative to see the case behind these numbers.
ENEOS Holdings' current analyst storyline points to revenues of ¥11,654.2b and earnings of ¥318.6b by 2029, based on an assumed yearly revenue decline of 1.8% and an earnings drop of ¥369.6b from ¥688.2b today.
ENEOS Holdings' forecasts show a ¥1580 fair value compared with a ¥1463 share price, indicating an 8% upside to its current price that could narrow quickly.
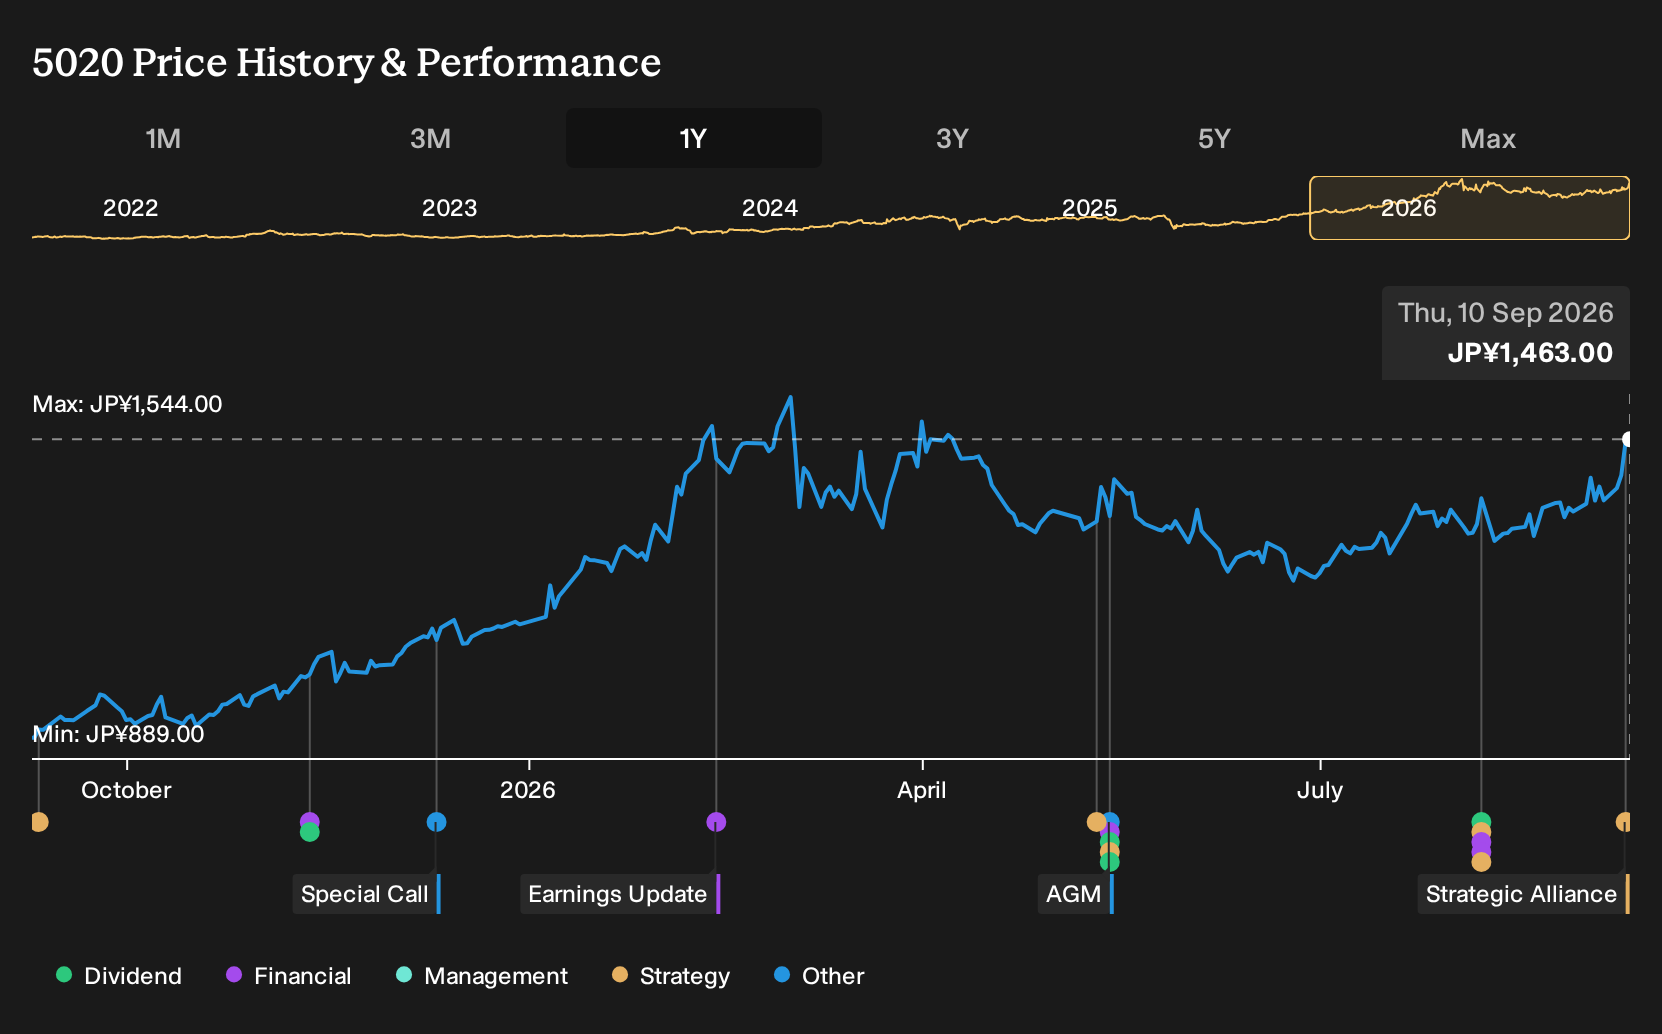
Exploring Other Perspectives
One alternate view on ENEOS Holdings leans heavily on upside from low carbon projects. Those bullish analysts were already pencilling in revenue of ¥15,770.6b and earnings of ¥371.3b by 2029, well above consensus. You can see how a move into organic flow batteries might push those optimistic scenarios even further, or force a rethink.
To balance the analyst view, it helps to compare ENEOS Holdings against 3 other fair value estimates for ENEOS Holdings to see how different investors frame the same cash flow path.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ENEOS Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ENEOS Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ENEOS Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond ENEOS Holdings?
Once the ENEOS Holdings story is clear in your mind, it can help to widen the lens and compare it with other opportunities that fit different risk and return profiles. The Simply Wall St Screener gives you a fast way to do that by filtering for balance sheet strength, income potential, or underappreciated quality.
- If capital preservation is high on your list, you could start with sturdier businesses using a 10 resilient stocks with low risk scores that aims to keep drawdowns in check.
- For investors focusing on value, a 17 high quality undervalued stocks can filter for companies with solid fundamentals trading below their assessed worth.
- If dependable cash distributions matter more to you than short term swings, you can focus on income focused candidates in a 18 dividend fortresses that screens for higher yield potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com