
Boot Barn (BOOT) Stock Looks Above Fair Value Despite Strong Returns
Boot Barn Holdings has given long term shareholders a strong ride, yet the current valuation checks point to a stock that screens on the expensive side rather than an obvious bargain. After a 3 year gain that still looks impressive in percentage terms, the recent pullback has not been enough to push the broader metrics into clear value territory.
- Over the past 3 years, Boot Barn Holdings has returned about 67.6%, which keeps long term performance well ahead of many retail peers even after the recent slide.
- Future expectations for store productivity and merchandise margins can support the current share price. Any slowdown in demand or pressure on operating costs may weigh on how much investors are willing to pay for the business.
- The broader valuation checks lean expensive, with Boot Barn Holdings scoring 2 out of 6 and not screening as a clear value opportunity on this framework.
The issue now is whether the recent share price weakness has brought Boot Barn Holdings closer to a reasonable entry zone, or whether the stock still implies expectations that are too high for cautious investors.
Compare Boot Barn Holdings with a curated set of retailers that score better on value checks by scanning 31 high quality undervalued stocks which may offer more grounded entry points.
Is Boot Barn Holdings Getting Expensive on Earnings?
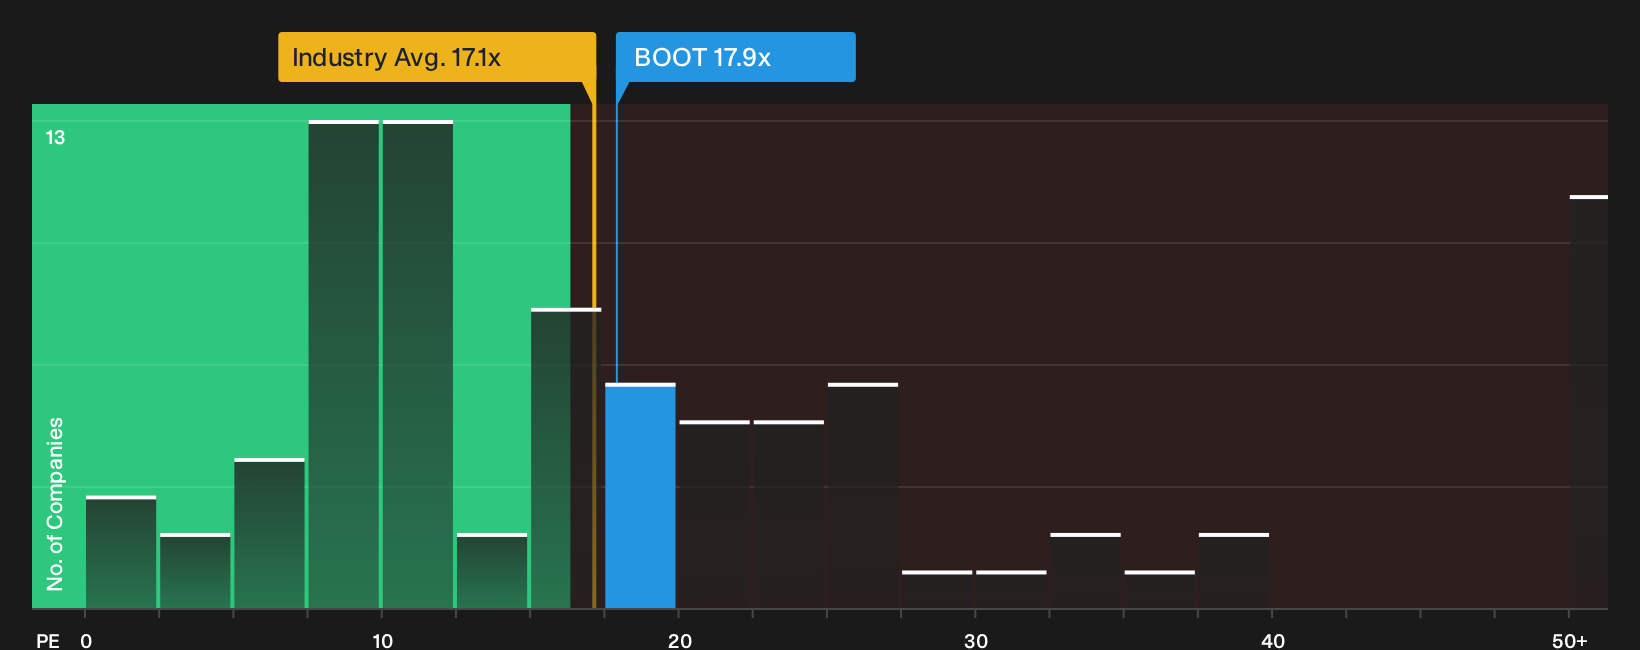
The P/E lens suits Boot Barn Holdings because earnings are a key anchor for how investors usually price a specialty retailer. On this measure, the stock trades on about 17.9x earnings, which sits above the peer average of 12.4x and slightly above the broader specialty retail industry on 17.1x. That sets Boot Barn in more premium territory than many direct competitors on this earnings yardstick.
The modelled fair P/E ratio for Boot Barn Holdings is 16.0x, based on its specific mix of risks, profitability and sector profile. The current multiple sits a little higher than that fair mark, which indicates that investors are paying more relative to what this framework suggests for the business. For anyone waiting for a clearer value entry, this spread suggests that recent share price softness has not fully reset the valuation on earnings yet.
On the P/E multiple, Boot Barn Holdings currently appears overvalued compared with both peers and its own modelled fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
The Boot Barn Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Boot Barn Holdings valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each is framed as a thesis about Boot Barn Holdings' business that can be tracked over time rather than a single snapshot, and they sit on Simply Wall St's Community page for investors who want to follow how those ideas progress.
One of the top community narratives on Boot Barn Holdings: 27% undervalued
"Boot Barn's aggressive store expansion strategy, with plans to open 60 new stores this fiscal year and a long-term goal to double its U.S. store count, could increase capital expenditures and lead to temporary occupancy cost pressures, potentially affecting net margins..."
Read one of the top narratives on Boot Barn Holdings
Do you think there's more to the story for Boot Barn Holdings? Head over to our Community to see what others are saying!
The Bottom Line
Boot Barn Holdings screens as overvalued on the main earnings multiple checks, so the current tag leans more like a quality premium than a clear bargain. That gap between the market P/E and the modelled fair ratio leaves less room for error if store productivity or merchandise margins soften. For holders, the question is whether the business can keep justifying that richer multiple. For anyone waiting on the sidelines, the crux is simple. It comes down to how confident you are that operating performance can sustain investor enthusiasm at this price.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com