
Has Constellation Brands (STZ) Fallen Far Enough To Look Undervalued?
Constellation Brands stock has had a rough few years, yet the broader valuation checks still suggest the shares lean cheap rather than expensive.
- Over the past 3 years, the share price has fallen about 50%, which signals a significant reset in how the market prices Constellation Brands.
- The key upside driver is whether the business can sustain healthy cash generation from its core brands, while a major risk is any sustained pressure on margins that keeps profitability under strain.
- The stock screens as broadly undervalued, with a high value score of 6 out of 6 checks, which points to cheaper pricing versus its fundamentals.
The issue now is whether that combination of a long share price slump and a strong value score means Constellation Brands is priced with a meaningful cushion, or if the weakness simply reflects justified concerns about the business.
Compare Constellation Brands with other beaten down bargains by scanning 31 high quality undervalued stocks, which pairs compressed valuations with solid underlying fundamentals.
Does Constellation Brands Look Undervalued on Earnings?
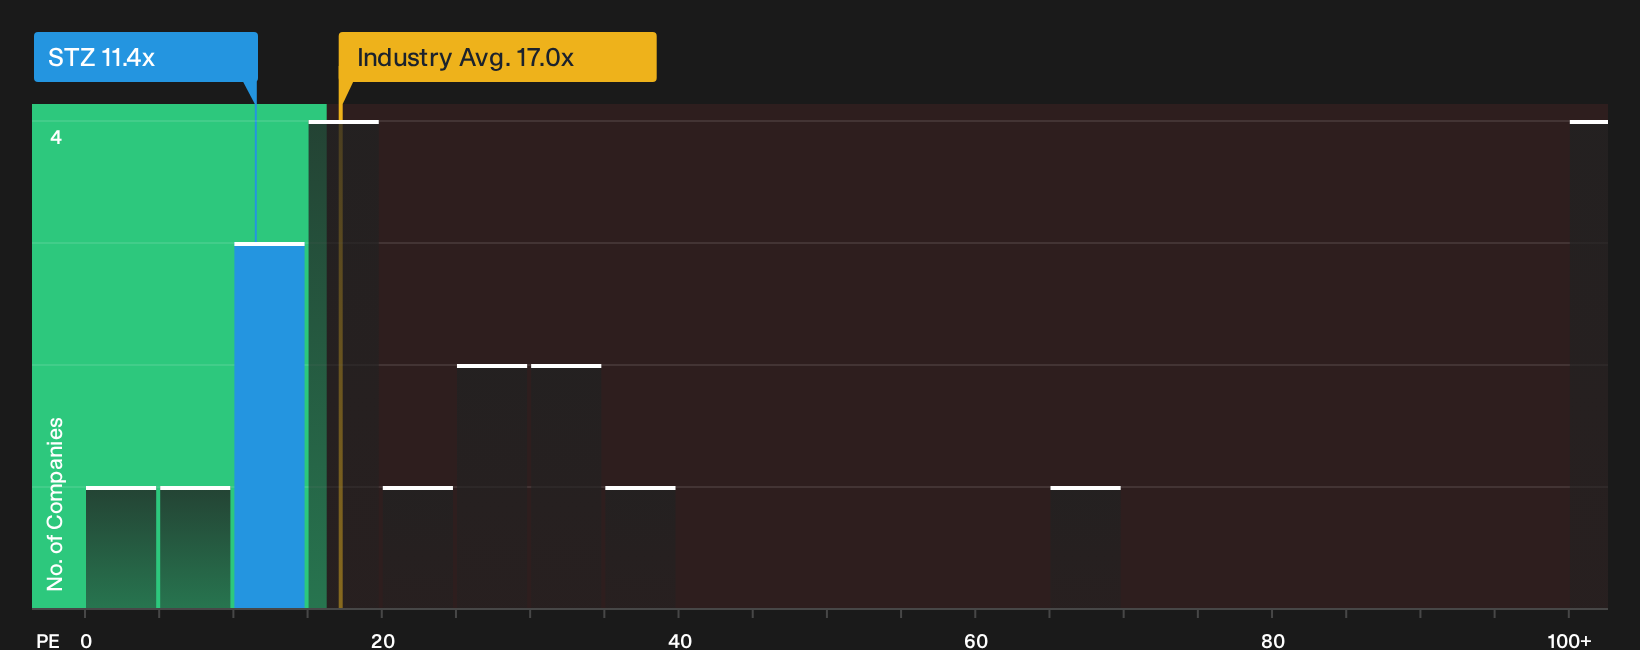
The P/E ratio suits Constellation Brands because earnings sit at the center of how most investors look at established consumer staples. On that score, the stock trades at about 11.4x earnings, which is well below the Beverage industry average of roughly 17.0x and the broader peer group on about 22.0x. The gap is wide enough that you are not just seeing a small discount for company specific issues.
A more tailored fair P/E multiple for Constellation Brands, which factors in its sector, profitability profile, size and risk, sits closer to 18.1x. The current 11.4x figure is meaningfully lower than that reference point. As a result, the market is pricing the business below what this framework suggests for its fundamentals. For investors who lean on earnings based valuation, Constellation Brands currently screens as attractively priced.
On a P/E basis, Constellation Brands stock appears undervalued relative to both its industry and a more customised fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Constellation Brands Narrative: What Would Justify Today's Price?
Constellation Brands Narratives on Simply Wall St pick up where the P/E puzzle leaves off and spell out what combination of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s market price. Instead of a single ratio or model output, they map the future that number quietly assumes so you can watch how Constellation Brands' actual performance lines up over time.
One of the top community narratives on Constellation Brands: 29% undervalued
"Despite current challenges, Constellation Brands' beer business is committed to maintaining best-in-class operating margins of 39% to 40% through disciplined innovation, distribution gains, and incremental marketing investments…"
Read one of the top narratives on Constellation Brands
Do you think there's more to the story for Constellation Brands? Head over to our Community to see what others are saying!
The Bottom Line
Constellation Brands looks cheap on earnings-based measures, and the broader valuation checks point in the same direction rather than flagging a clear trap. That gap only closes if you think margins stay under pressure or the market refuses to pay even an average P/E multiple for a mature beverage group. The crux is simple: either cash generation and profitability hold up well enough for the multiple to drift closer to peers, or the current discount proves to be the market correctly pricing in lasting margin strain.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com