
Pinnacle Financial Partners (PNFP) Draws Insider Support, Is The Stock Still Trading At A Discount?
Fresh insider buying has put Pinnacle Financial Partners (PNFP) back in the spotlight after CEO Kevin S. Blair picked up 2,565 shares in an open market purchase worth about US$14.8 million.
That purchase lands at a time when Pinnacle Financial Partners’ share price has eased, with the stock down 5.18% on a 1 month share price return and 1.57% on a 1 day share price return, even as the 3 month share price return is up 5.75% and the 3 year total shareholder return sits at 52.66%. This suggests that longer term holders have still seen solid gains while near term momentum has cooled.
Spot similar regional banking stories by scanning the hand picked list of solid balance sheet and fundamentals (24 results) that share traits with Pinnacle Financial Partners after this latest insider purchase.
Pinnacle Financial Partners now trades around US$99 while analyst targets cluster near US$120 and one intrinsic value model points to a much larger gap. Does that recent insider buy hint the share price is lagging the fundamentals?
Most Popular Narrative: 16.9% Undervalued
Pinnacle Financial Partners is pegged with a fair value of $119.25 in the most followed narrative, compared with a recent share price around $99.13. This frames insider buying against a valuation gap driven by earnings and revenue projections.
Migration-driven population and business growth in high-opportunity Sun Belt and Southeast markets continues to broaden Pinnacle's customer base, resulting in outsized loan and deposit growth even during challenging macro and rate cycles. This structurally supports double-digit revenue and net interest income growth.
Read the complete narrative. Read the complete narrative.
Want to see what underpins that fair value on Pinnacle Financial Partners? The narrative leans on aggressive revenue expansion, rising margins and a lower earnings multiple than many fast growing banks. Curious how those moving parts are expected to work together over time?
Result: Fair Value of $119.25 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Pinnacle Financial Partners story could change quickly if Southeastern loan demand softens or if commercial real estate stress increases credit losses and funding costs.
Find out about the key risks to this Pinnacle Financial Partners narrative.
Another View: Pinnacle Financial Partners Looks Expensive On P/E
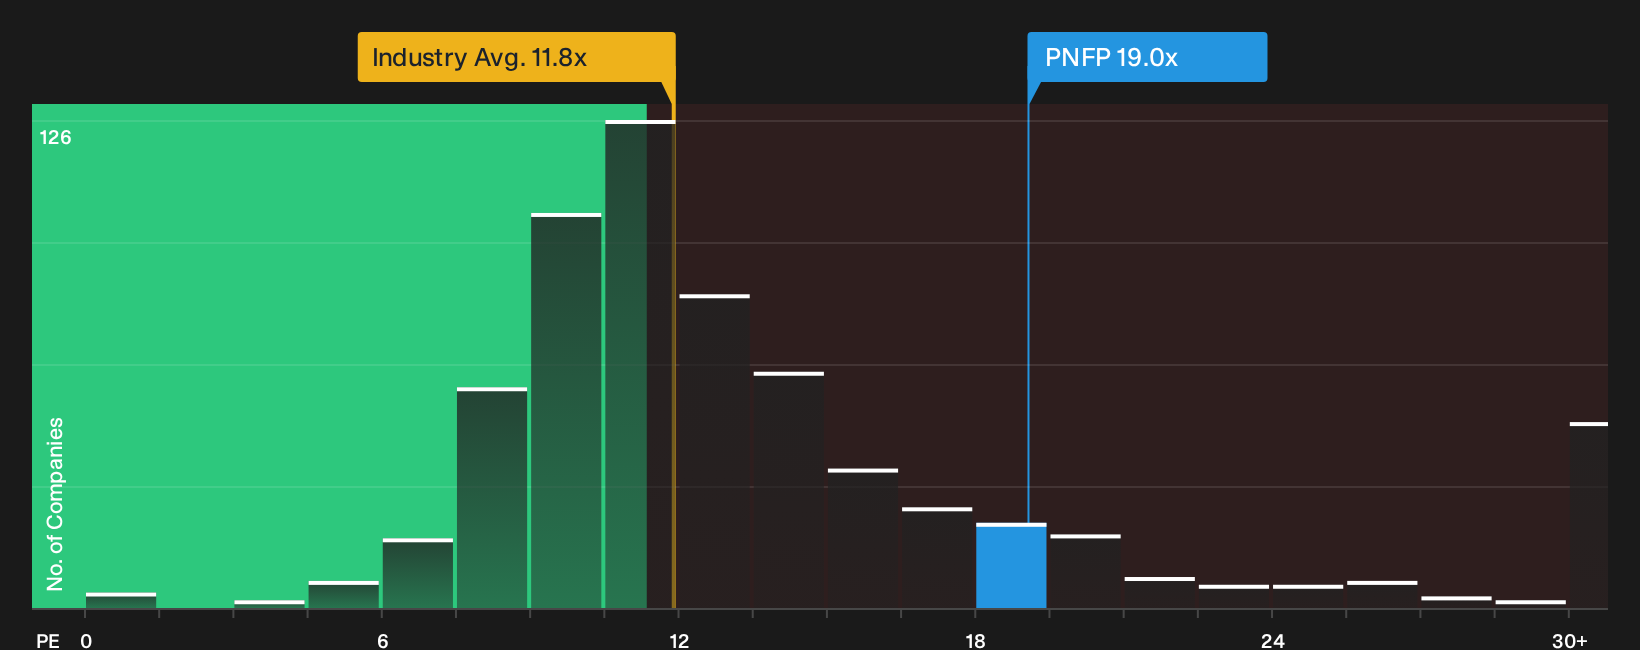
The SWS DCF model flags Pinnacle Financial Partners as undervalued, yet the simple P/E story reads very differently. PNFP trades on roughly 19x earnings, compared with about 11.9x for the US Banks industry and 11.4x for peer stocks, while the fair ratio is estimated at 21x.
So investors are weighing a stock that screens rich versus sector and peers, but still below that fair ratio the market could move toward over time. Is this a valuation buffer or a warning that expectations already carry a lot of good news?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk around Pinnacle Financial Partners can be confusing. Move quickly, review the data for yourself, and weigh both sides through the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Pinnacle Financial Partners?
If Pinnacle Financial Partners has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against fresh opportunities using targeted screeners.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (24 results) that prioritizes financial strength and durable fundamentals.
- Hunt for mispriced quality by scanning the 31 high quality undervalued stocks where strong businesses trade on what may be discounted valuations.
- Zero in on overlooked stories by checking the 17 high quality undiscovered gems that highlight quality companies many investors have not focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com