
OUTFRONT Media (OUT) Could Be 25% Undervalued On Its Digital Growth Narrative
OUTFRONT Media (OUT) is set to present at Citi’s 2026 Global TMT Conference in New York on September 8, 2026, with Chief Executive Officer Nick Brien scheduled to speak.
Recent trading has been choppy for OUTFRONT Media, with the share price slipping 4.7% over the past month and 8.7% over the last quarter, even after a 20.7% year to date share price return and a 58.2% total shareholder return over the past year. This points to longer term momentum holding up while shorter term sentiment cools ahead of events like the Citi conference.
Scan how OUTFRONT Media compares with other real estate plays showing momentum and value traits in our hand picked 31 high quality undervalued stocks.
OUTFRONT Media now trades well below both analyst targets and some fair value estimates, even after the recent pullback. Is that caution a reasonable read on risk, or a mispriced opportunity based on the numbers?
Most Popular Narrative: 24.7% Undervalued
On the narrative view, OUTFRONT Media’s fair value of $38 sits well above the recent $28.62 close, which puts the spotlight on what is driving that gap.
OUTFRONT's ongoing digital conversion of static billboards and transit assets to digital displays enables higher ad rotation, dynamic content, and premium pricing, directly supporting accelerated top-line growth and long-term margin expansion. The company's enhanced focus on data analytics, programmatic buying, and improved audience measurement (via investment in ad tech and centralized operations) positions it to capture more digital ad budgets, driving higher occupancy rates and increased revenue per asset.
Read the complete narrative. Read the complete narrative.
Want to see why this framework points to higher earnings, fatter margins, and a richer future multiple for OUTFRONT Media? The key is how digital billboards, ad tech, and capital recycling are woven together in the cash flow math. Curious which revenue and margin paths are baked into that $38 figure and how the discount rate shapes today’s implied upside? The full narrative lays out those moving parts in detail.
Result: Fair Value of $38 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the OUTFRONT Media story can break if advertiser budgets continue shifting toward social and online formats, or if high fixed lease costs start to squeeze flexibility.
Find out about the key risks to this OUTFRONT Media narrative.
Another View: OUTFRONT Media Through The Earnings Lens
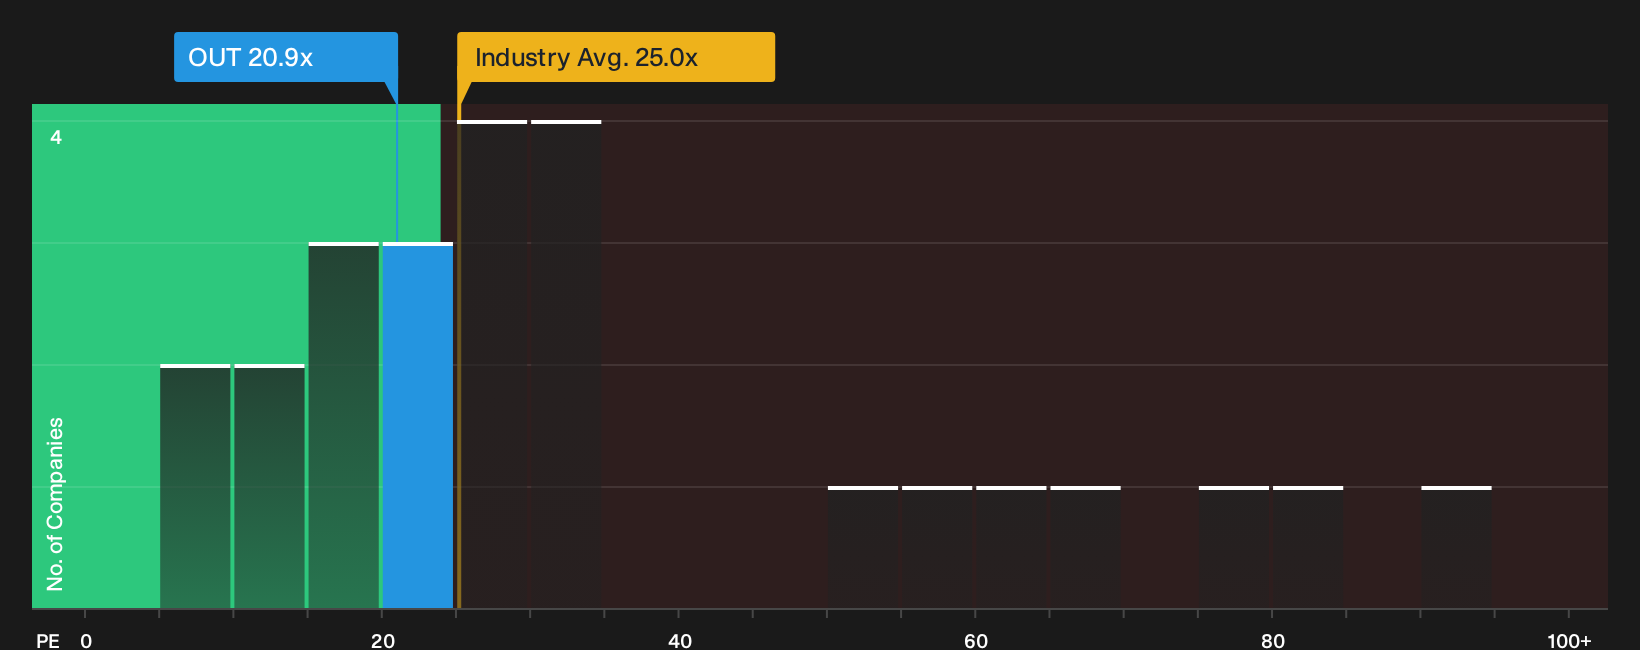
The SWS fair ratio tells a different story. OUTFRONT Media trades on a P/E of 20.9x, richer than peer averages at 15.9x yet well below an estimated fair ratio of 37x. That mix of cheaper than fair and pricier than peers raises a simple question. Is the risk in the multiple or in the assumptions behind it?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across OUTFRONT Media’s valuation and narrative can feel messy, so move fast, review the key data points, and weigh both potential upside and the concerns flagged in the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond OUTFRONT Media?
Do not stop with OUTFRONT Media. Use the screener to zero in on fresh opportunities that fit your own risk, return, and income preferences.
- Target potential mispricings by scanning a focused set of companies that flag a value tilt and stronger fundamentals through the 16 high quality undiscovered gems.
- Strengthen portfolio resilience by filtering for businesses with cleaner finances and sturdier funding profiles using the list of solid balance sheet and fundamentals (23 results).
- Pull in reliable cash flow ideas by honing in on higher yielding payers that still pass quality checks with the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com