
Dynatrace (DT) Stock Could Be Undervalued On Cash Flow But Overvalued On Earnings
Dynatrace presents investors with a clear valuation puzzle right now, because the Discounted Cash Flow (DCF) intrinsic value estimate points to meaningful upside while the broader checks and market multiples lean toward a richer price tag.
- The share price is down about 29% over 5 years, which means anyone buying today is doing so after a long period of underperformance rather than on the back of a fresh rally.
- Recent earnings strength and higher profitability targets can support the intrinsic value case. However, any stumble in execution or slower customer spending would quickly matter for what investors are willing to pay.
- The stock screens as overvalued on market multiples and has a low value score, scoring 2 out of 6 checks, so on the wider toolkit it leans more expensive than cheap.
The issue now is whether Dynatrace's current price offers enough compensation for the mixed signals between the intrinsic value estimate and the richer read from market multiples.
Compare Dynatrace's mixed valuation signals with hand-picked alternatives by scanning 31 high quality undervalued stocks, which also pair fundamental strength with more conservative pricing.
Does Dynatrace Look Undervalued on Cash Flow?
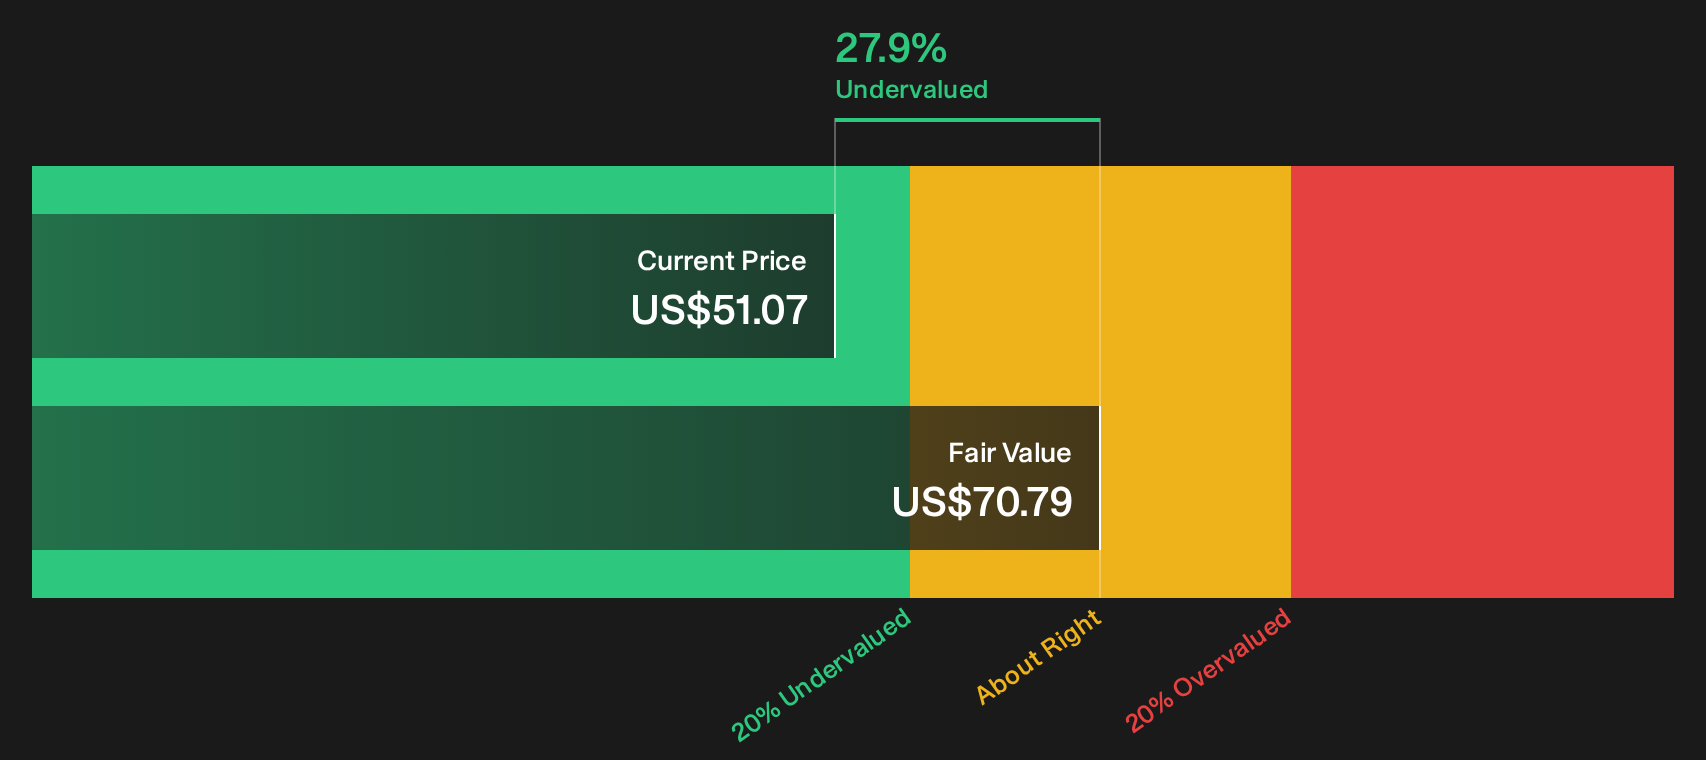
The Discounted Cash Flow (DCF) model values Dynatrace by projecting future free cash generation and discounting it back to today. On this framework, the latest twelve month free cash flow sits at about $564.9 million, with the model assuming that cash flows keep growing rather than shrinking. That stream of projected cash converts into an estimated intrinsic value of roughly $70.79 per share.
Compared with the current market price, the DCF output implies Dynatrace trades at about a 27.9% discount, so the stock appears undervalued on this method. Recent earnings results and raised margin guidance help explain why the cash flow profile used in the model looks supportive, even though the share price has not fully caught up. Because the first quarter 2027 earnings and higher guidance point to stronger cash generation in the model, the market’s hesitation keeps the price below what the DCF output suggests.
On this Discounted Cash Flow view, Dynatrace stock screens as undervalued relative to the cash it is expected to produce.
Our Discounted Cash Flow (DCF) analysis suggests Dynatrace is undervalued by 27.9%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Has Dynatrace Run Too Far on Earnings?
P/E suits Dynatrace because profit, not just revenue or assets, is what investors are currently rewarding in software.
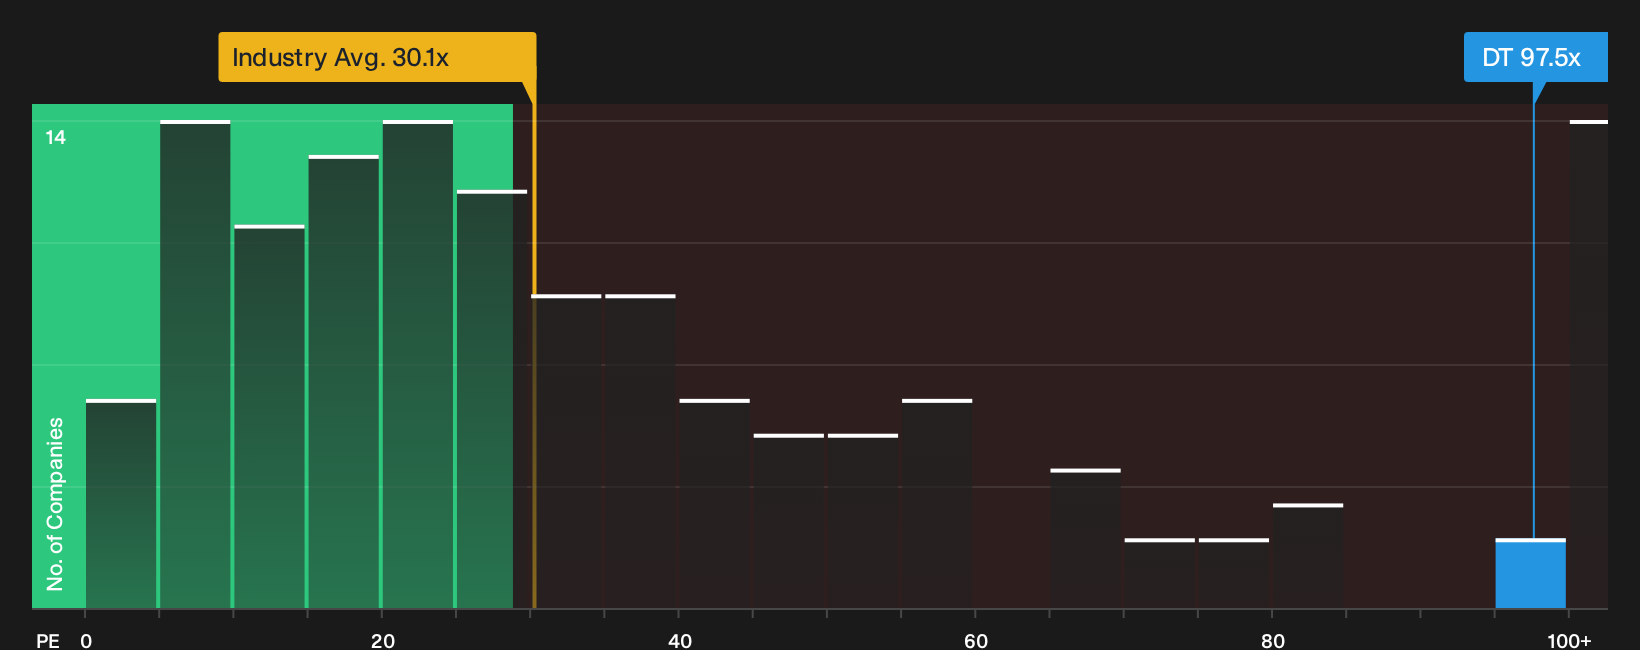
The stock trades on a P/E of about 97.5x, which is far richer than the broader Software industry on roughly 30.1x and well above the peer group near 53.7x. The Fair Ratio model, which looks at factors such as growth profile, margins, size and risk, suggests a multiple closer to 37.0x would be more in line with those fundamentals. That gap indicates investors are paying a high premium for Dynatrace earnings today.
Strong recent earnings and raised guidance help explain why buyers are willing to pay a higher price, yet the current P/E remains well beyond both sector norms and the tailored Fair Ratio marker.
On the P/E lens, Dynatrace stock currently screens as clearly overvalued relative to both the industry and its modeled Fair Ratio benchmark.
See what the numbers say about this price — find out in our valuation breakdown.
The Dynatrace Narrative: What Would Justify Today's Price?
Dynatrace Narratives on Simply Wall St pick up where this valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Instead of a single output from a ratio or model, these scenarios describe the future that output depends on, so you can watch how Dynatrace's actual results compare with the assumptions.
Community views on Dynatrace could hardly be further apart, with one side framing it as a mispriced compounder and the other as a crowding risk around AI observability.
Bull case: 34% undervalued
"Dynatrace has positioned itself as the "CFO’s Choice", the only platform capable of delivering massive cost savings through tool consolidation while offering the most precise AI for the Global 1000…"
Read the full Bull Case to see why Dynatrace could be undervalued
Bear case: 42% overvalued
"While deeper integrations with hyperscalers and partners such as AWS, Azure, GCP and ServiceNow expand Dynatrace’s reach, these ecosystems also host alternative observability and AI tools…"
Read the full Bear Case to see why Dynatrace could be overvalued
Do you think there's more to the story for Dynatrace? Head over to our Community to see what others are saying!
The Bottom Line
Dynatrace presents a clean split in valuation. The Discounted Cash Flow (DCF) intrinsic value estimate points to meaningful upside, while the P/E and other checks lean toward an overvalued stock on earnings and sentiment. That gap comes from what each lens cares about: intrinsic value is anchored in long term cash generation and funding needs, whereas the multiples view reflects what investors are currently prepared to pay for growth and AI exposure. The key question is whether Dynatrace can sustain the cash flow and margin profile implied in the intrinsic value work without a stumble in execution that would justify the richer multiple instead of the discount.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com