
Elanco (ELAN) Stock Still Looks Cheap Despite Its 93% Run
Elanco Animal Health has delivered a 93.2% gain over the past three years, yet the current share price of US$23.17 still screens as cheap against its own cash flow based intrinsic value estimate. The stock now presents a clear valuation puzzle for investors who are weighing that historical return against models that flag it as potentially undervalued.
- Over the last three years, Elanco Animal Health has returned 93.2%, which puts recent performance firmly in the spotlight as investors reassess what is already priced in.
- Future cash generation from the animal health portfolio can support the current valuation. However, any setback in turning reported profits into steady free cash flow may limit how much the market is willing to pay.
- The broader checks lean cheap, with Elanco Animal Health screening as undervalued on 6 of 6 valuation tests, according to a value score of 6.
The issue now is whether that combination of strong three year returns and an intrinsic value estimate that sits below the market price still leaves enough room for Elanco Animal Health to be considered a bargain today.
Scan beyond Elanco Animal Health and compare this valuation setup with a curated list of other stocks that screen as potentially cheap on cash flow using the 31 high quality undervalued stocks.
Is Elanco Animal Health a Bargain on Cash Flow?
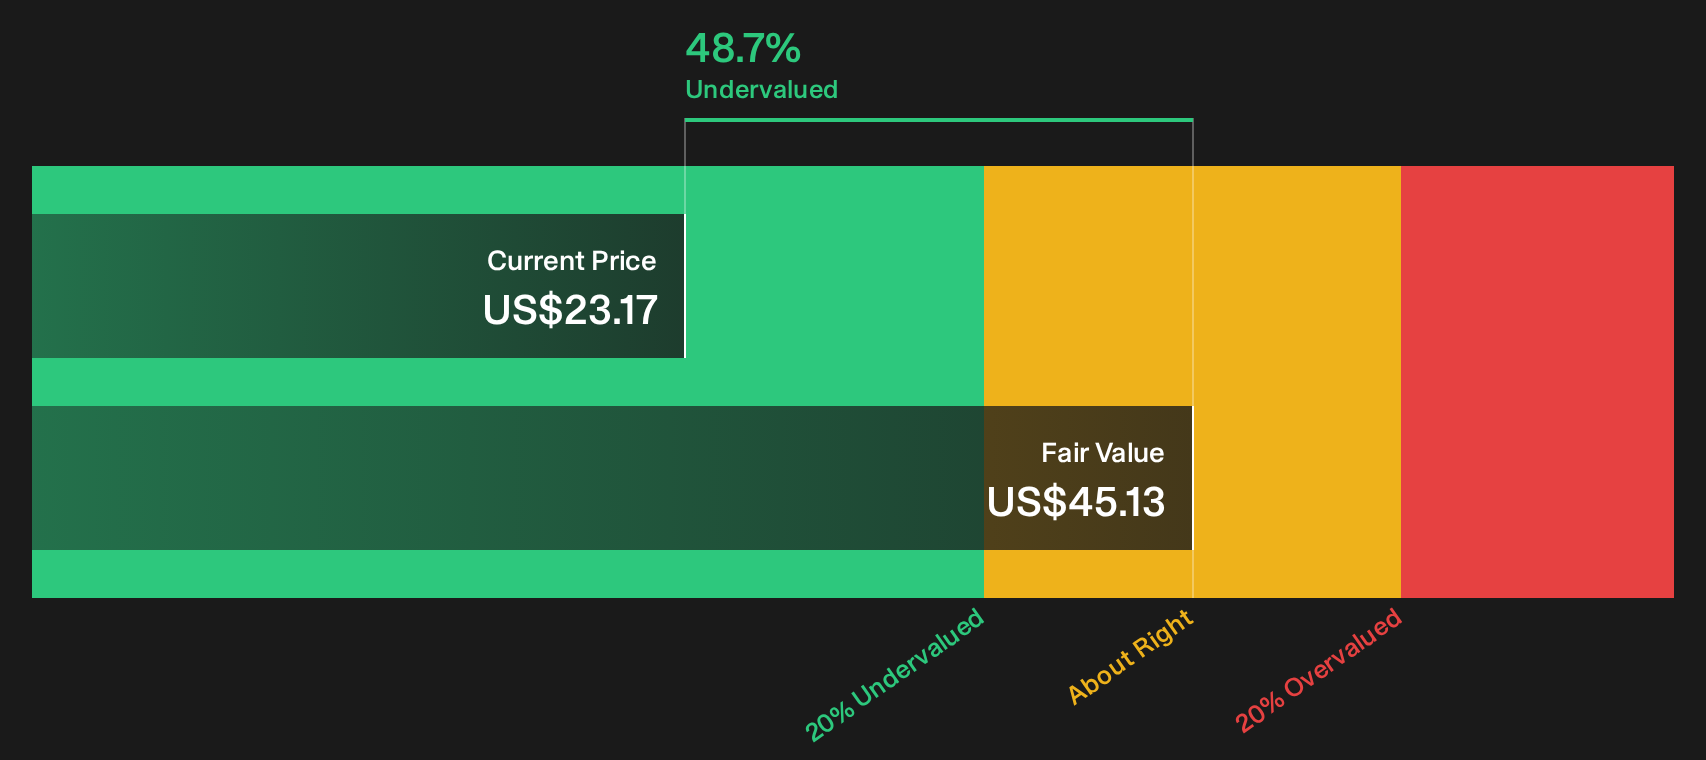
The Discounted Cash Flow (DCF) approach here focuses on what Elanco Animal Health can generate in cash rather than on its accounting earnings. Over the latest twelve months, the group produced free cash flow of about $397.9 million, which underpins a model that assumes growing cash generation rather than a shrinking base. On those projections, the two stage free cash flow to equity framework points to an estimated intrinsic value of about $45 per share.
Measured against the current share price of $23.17, that DCF outcome implies Elanco Animal Health trades at a meaningful discount, with the model indicating the stock is 48.7% undervalued. The gap suggests the market is applying a far lower value to the animal health cash flows than this cash based estimate would support.
On this DCF view, Elanco Animal Health currently appears undervalued relative to its projected cash generation.
Our Discounted Cash Flow (DCF) analysis suggests Elanco Animal Health is undervalued by 48.7%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is Elanco Animal Health Still Cheap on Sales?
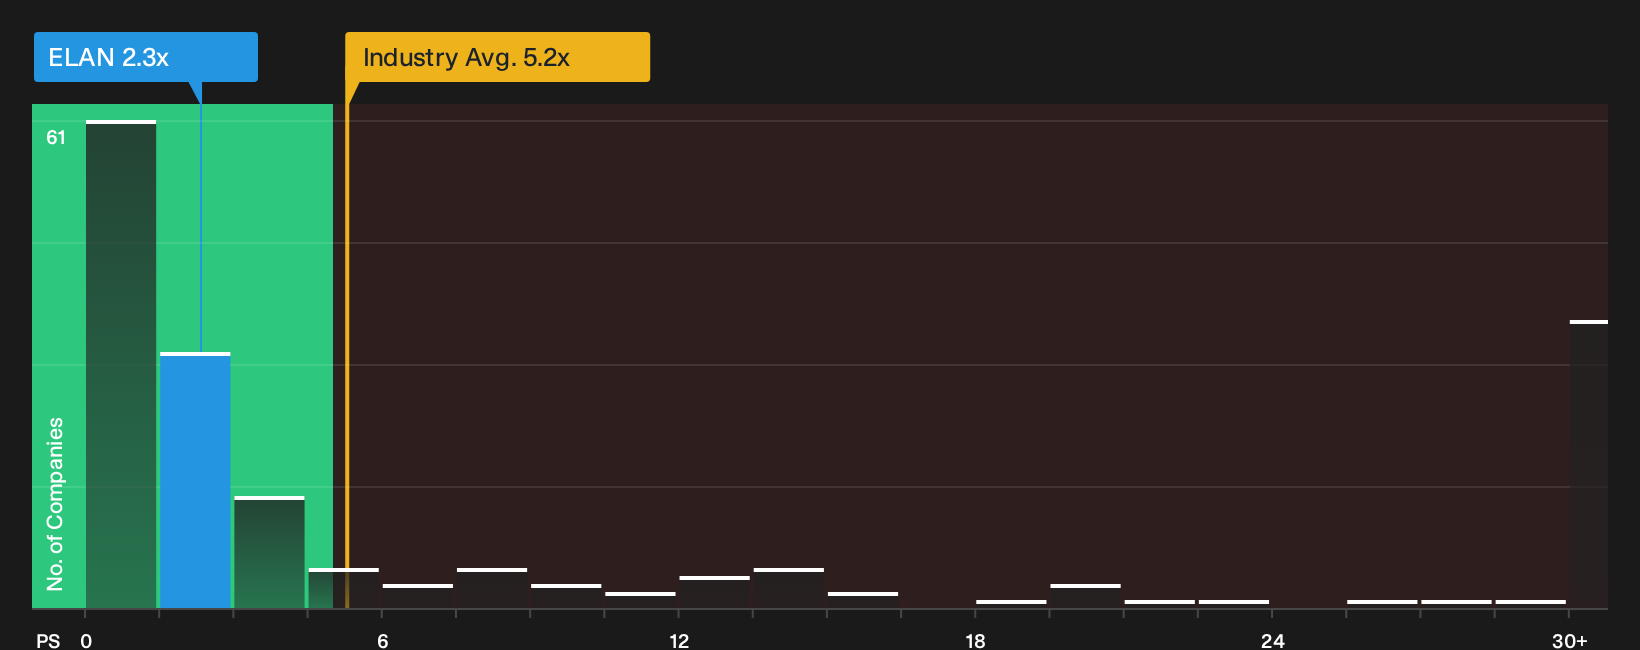
The P/S ratio suits Elanco Animal Health because revenue is often a cleaner anchor than earnings for a business that still reports accounting losses. At the moment the stock trades on about 2.3x sales, which sits well below the pharmaceuticals industry average of 5.2x and under the peer group on roughly 5.3x.
A tailored fair P/S multiple for Elanco Animal Health is estimated at about 4.6x, based on the company’s sector, profitability profile, size and risk. That is almost double the current P/S ratio. The gap indicates that the market is pricing Elanco’s revenue stream at a sizeable discount to what this framework suggests could be reasonable.
On this P/S yardstick, the Elanco Animal Health stock appears undervalued compared with both its sector and a more tailored fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Elanco Animal Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Elanco Animal Health valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties its number to a clear view on how Elanco Animal Health's growth path, profitability and risk profile could evolve, giving you a reference point to revisit as fresh information emerges.
One of the top community narratives on Elanco Animal Health: 26% undervalued
"Operational focus on product launches and divesting non-core businesses such as the Aqua division has enabled debt reduction and increased investment capacity..."
Read one of the top narratives on Elanco Animal Health
Do you think there's more to the story for Elanco Animal Health? Head over to our Community to see what others are saying!
The Bottom Line
Elanco Animal Health screens as undervalued on both the Discounted Cash Flow (DCF) view and on sales based multiples, so the current gap to intrinsic value and peer pricing is hard to ignore. The broader valuation checks also lean supportive, which keeps the focus on whether cash conversion and margins can justify that intrinsic value estimate. The real fork in the road is simple: either free cash flow and profitability stay robust enough for the market to close some of that discount, or the current pricing proves to be the correct warning about execution and cash generation risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com