
Learn Why The Bull Case For A. O. Smith Stock Could Change Following Earnings Beat
- A. O. Smith recently reported quarterly results with revenue slightly ahead of analyst estimates and full year EPS guidance above prior expectations, highlighting cost discipline and steady demand across its core water heating and treatment lines.
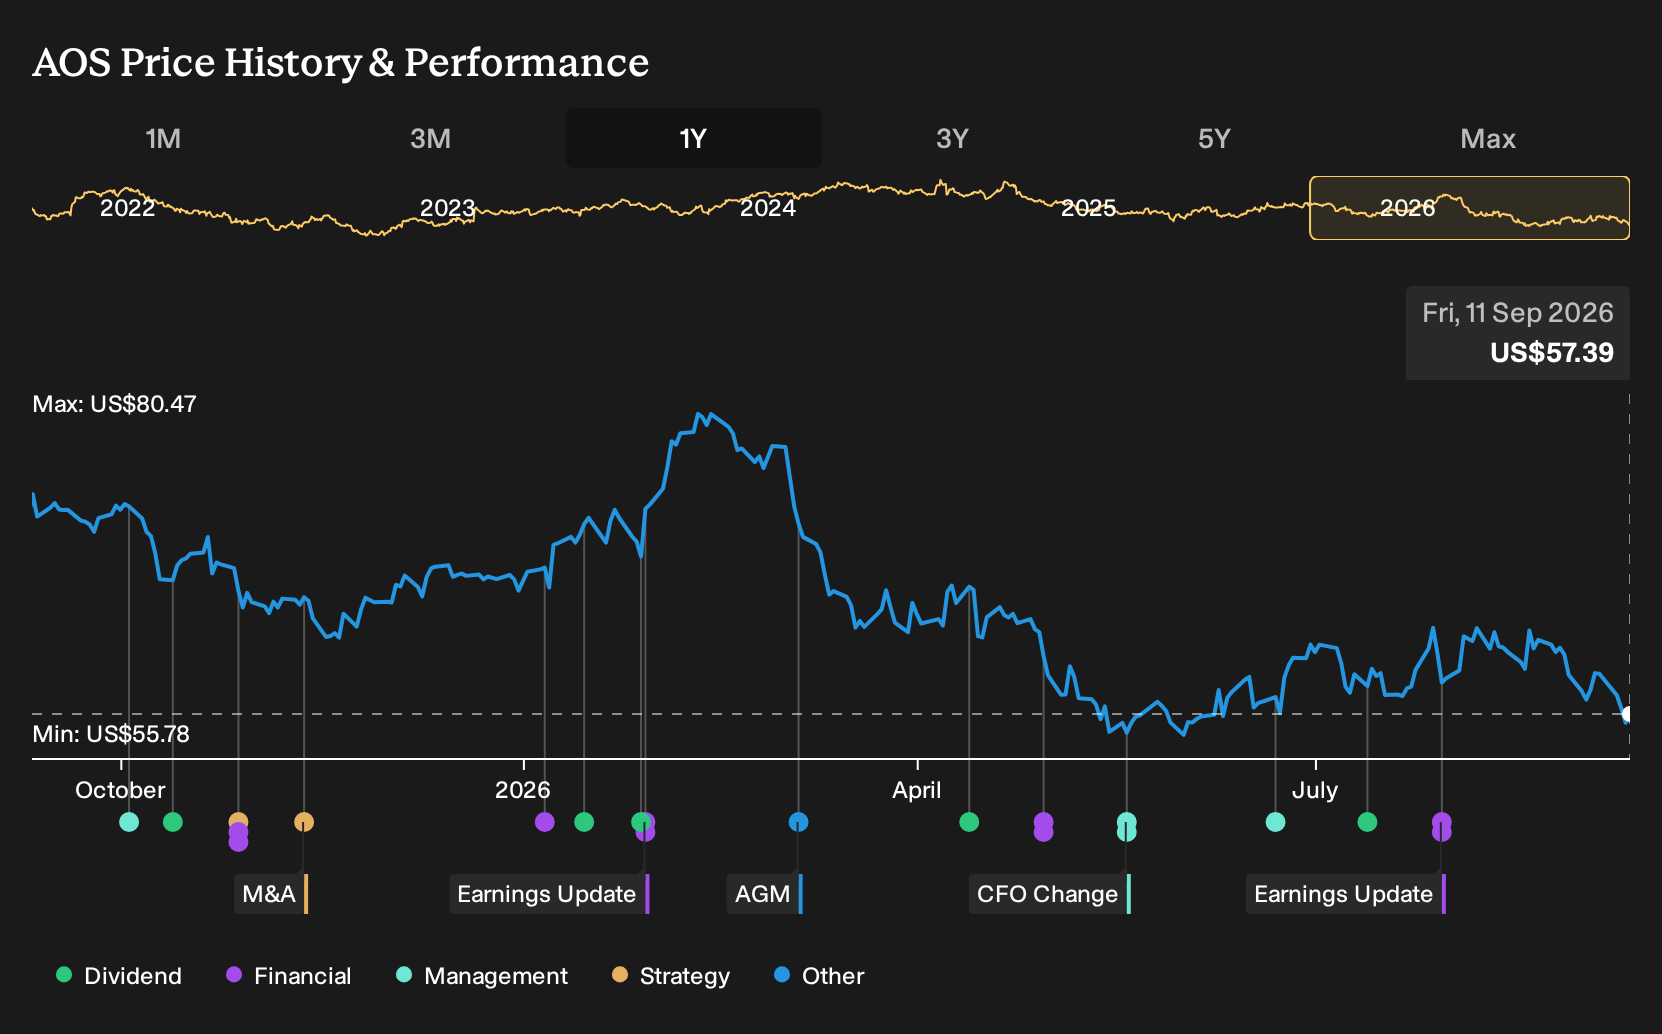
- The market reaction focused less on the earnings beat and more on A. O. Smith's slower revenue expansion versus peers, which underscores how relative growth expectations now influence how investors weigh its efficiency, product mix, and geographic diversification efforts.
- We will examine how A. O. Smith's investment narrative is shaped by earnings that topped guidance while revenue trailed faster growing peers.
Compare how A. O. Smith stacks up on quality and resilience by scanning our hand picked 11 resilient stocks with low risk scores for other businesses with sturdier profiles when growth expectations tighten.
A. O. Smith Investment Narrative Recap
To own A. O. Smith, you need to be comfortable with a story built on durable replacement demand, steady cash generation, and gradual product mix improvement rather than rapid expansion. The latest quarter backs up that profile, with Q2 revenue slightly ahead of expectations and full year EPS guidance raised. In the short term, the key catalyst remains execution on efficiency and pricing so that higher costs and modest volume trends do not erode profitability.
The biggest risk still sits in the combination of a mature North American heater market and uncertainty in China and other international regions. Recent results did not materially change that risk balance. North America replacement demand, channel reshaping in water treatment, and competitive pressure abroad all remain central to how resilient A. O. Smith looks over the next few quarters.
The most relevant recent development is the tighter full year EPS guidance that now sits above prior estimates. That signal rests on cost discipline and product mix, not on an aggressive focus on faster revenue expansion. For you as a shareholder, it frames the near term story around margin quality and execution rather than large volume swings.
This guidance update also links directly to the key catalysts analysts have highlighted in A. O. Smith: higher efficiency and smart products, ongoing channel realignment, and operational improvement. These factors now have to do more work to support earnings when top line growth trails some peers. If those projects stay on track, the company has levers to support profitability even if external demand remains uneven.
A. O. Smith's current earnings sit at $527.6 million, with analysts expecting $611.6 million by 2029. This implies about $4.3 billion in revenue and a 4.2% yearly revenue growth rate for that year. That outlook assumes earnings increase by roughly $84 million from earnings today to reach the consensus forecast in 2029.
Learn why A. O. Smith's fair value points to a 23% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view leans heavily on A. O. Smith’s operational excellence story. The most optimistic analysts were penciling in revenue of about $4.4b and earnings of $646.3m by 2029, compared with the $4.3b and $611.6m baseline. Those projections came before this Q2 update, so opinions may shift as you compare both narratives.
Explore 4 other A. O. Smith fair value estimates, including one that suggests there could be as much as 48% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your A. O. Smith research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for A. O. Smith. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A. O. Smith's overall financial health at a glance.
Looking for more A. O. Smith style investment ideas?
Once you have a view on A. O. Smith, it can help to compare it with other businesses that share some of the same qualities around resilience, balance sheets, or income potential. The Simply Wall St Screener lets you do that in a structured way so you are not relying on headlines or hype to build your watchlist.
- If capital preservation and steadier profiles matter most to you, start with a curated group of resilient businesses through the 11 resilient stocks with low risk scores.
- For income focused investors who want yield without ignoring fundamentals, filter for companies that match your payout and quality criteria using the 6 dividend fortresses.
- If you prefer to get in early on under the radar opportunities, broaden your research with a carefully filtered 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com