
Gimv (ENXTBR:GIMB) Earnings Jump Puts Valuation Back In Focus
Earnings jump puts Gimv in focus
Gimv (ENXTBR:GIMB) has moved into the spotlight after reporting half year net income of €148.34 million and basic earnings per share of €4.03, both higher than the prior period.
The latest half year figures arrive as Gimv's share price edges higher, with a 1 day share price return of 2.25% and a 1 month share price return of 3.53%, while the 3 year total shareholder return of 26.11% points to momentum that has built gradually over time rather than in a single earnings reaction.
Scan other privately focused and niche financials that show similar earnings traction to Gimv by starting with the hand picked 618 high quality undiscovered gems.
After that strong half year result and a steady share price climb, the real tension for Gimv investors now sits in the numbers. Does the current valuation still leave enough upside to justify the risk?
Price-to-earnings of 5.7x: Is it justified for Gimv?
On a simple snapshot, Gimv trades on a P/E of 5.7x, which looks inexpensive when set against the recent half year earnings jump and the current share price of €45.5.
The P/E ratio compares what investors pay for each euro of earnings. For an investment group like Gimv, which reports sizeable profit from its portfolio, that metric gives a quick sense of how much of those earnings are being recognised in the market price.
Gimv's recent record shows earnings growth of 39.8% over the past year, ahead of its 5 year average of 15.8% per year, and margins that have moved from 73.5% to 77.9%. In that context, a single digit P/E can indicate that the market is applying a cautious filter to those profits, especially given the high level of non cash earnings flagged in the data.
The comparison with peers is even starker. Gimv's 5.7x P/E sits far below both the peer group average of 36.9x and the wider European capital markets industry on 13.5x. That kind of gap suggests investors are valuing each euro of Gimv earnings far more conservatively than similar businesses, which may reflect how they view the sustainability or quality of those profits rather than their size.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 5.7x (UNDERVALUED)
Still, Gimv's reliance on valuing private holdings and its broad exposure across consumer, health and industrial themes could quickly challenge the current earnings picture if conditions shift.
Find out about the key risks to this Gimv narrative.
Another view on Gimv's value
The P/E points to a cheap Gimv, but the SWS DCF model goes further and values the shares at €70.84 versus the current €45.5, which implies the stock trades at a sizeable discount. If both earnings and cash flow signals point lower than fair value, what risk is the market still pricing in?
Look into how the SWS DCF model arrives at its fair value.
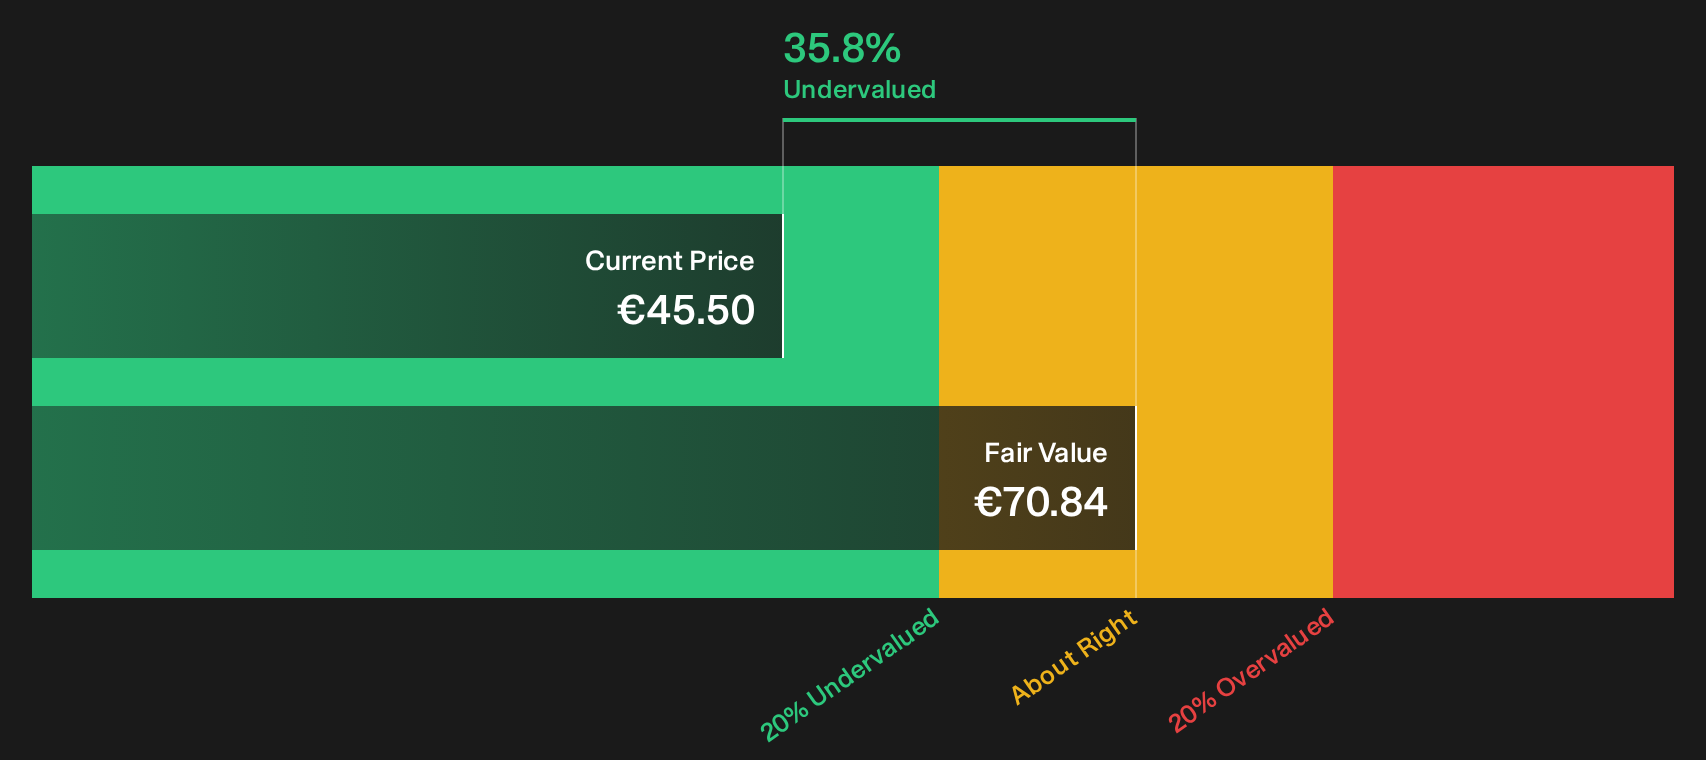
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Gimv for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Surprised by how mixed the message around Gimv feels after that earnings jump and discount to fair value. Use the full data set, stress test your own thesis, and then weigh up the 2 key rewards and 2 important warning signs.
Looking for more Gimv style investment ideas?
If Gimv has sharpened your focus on value and quality, do not stop here. The next set of ideas could reshape how you build your portfolio.
- Target potential mispricing by scanning a focused set of higher quality opportunities through the 183 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies in the 164 dividend fortresses that pair yield with resilience.
- Prioritise resilience and capital protection by filtering for businesses in the 97 resilient stocks with low risk scores before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com