
10x Genomics (TXG) Stock Looks Expensive Despite Fresh AI Pathology Optimism
10x Genomics has delivered a very strong 1 year gain while the broader valuation checks still flag the stock as expensive rather than a clear bargain.
- The share price return over the past 12 months is 442.6%, which puts 10x Genomics among the more extreme recent movers in the market and raises the bar for what needs to go right next.
- The newly announced collaboration with Lunit on AI enabled pathology analysis can support optimism around long term demand, while execution risk in scaling the single cell business, highlighted by recent broker commentary, may weigh on how much investors are willing to pay.
- The broader valuation framework, where 10x Genomics is assessed as undervalued in 0 of 6 checks, points to a stock that currently leans expensive rather than offering an obvious discount to fundamentals.
The issue now is whether 10x Genomics' recent share price surge leaves enough valuation cushion to justify the risks around future growth and execution.
Spot similar high-momentum stories to 10x Genomics and pressure test their valuations against fundamentals with a curated list of 31 high quality undervalued stocks.Is 10x Genomics Getting Expensive on Sales?
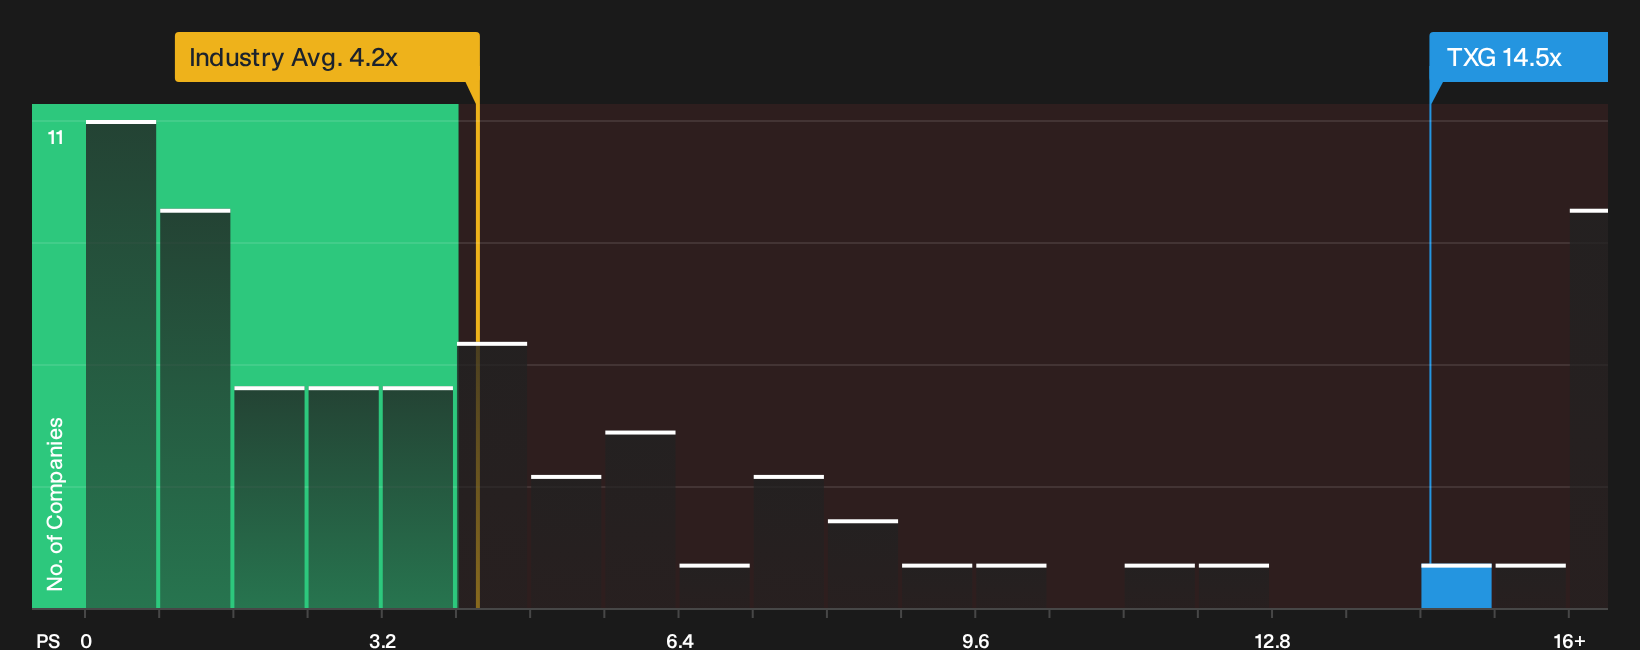
P/S can be a useful lens for 10x Genomics because the business is still loss making on a P/E basis but already generating meaningful revenue. On this metric, the stock trades on a P/S ratio of 14.5x, compared with a Life Sciences industry average of 4.2x and a peer group closer to 5.5x. That is a substantial premium for each dollar of current sales.
The fair P/S ratio, which adjusts for the company’s risk profile, margins and growth expectations, is 6.4x. Against that benchmark, 10x Genomics is valued at more than double the level that framework would imply. Despite the recent Lunit collaboration increasing enthusiasm around the long term opportunity in oncology tools, the current pricing already reflects a significant degree of optimism about future execution.
On a P/S basis, 10x Genomics appears clearly overvalued relative to both tailored fair value estimates and sector benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
The 10x Genomics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for 10x Genomics pick up where the valuation checks leave off and explain which combinations of future growth, profitability and earnings power would need to occur for the stock to be worth materially more or materially less than today’s price on the Community page. Instead of relying on a single ratio or model output, they unpack the specific future path that figure assumes so you can monitor over time whether that story is actually playing out.
One of the top community narratives on 10x Genomics: 38% overvalued
"Macroeconomic pressures, shrinking pricing power, product shifts, and ongoing losses are undermining revenue growth, margin stability, and the path to profitability..."
Read one of the top narratives on 10x Genomics
Do you think there's more to the story for 10x Genomics? Head over to our Community to see what others are saying!
The Bottom Line
On current multiples, 10x Genomics screens as overvalued, with the market already assigning a rich price tag to each dollar of sales. The crux is simple: enthusiasm around long term demand in areas like oncology tools needs to translate into sustained revenue traction and better economics in the single cell business. For investors, the key question is whether execution can tighten enough to justify holding that premium, or whether any stumble in growth or product adoption forces the valuation to compress back toward sector norms.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com