
Quantinuum (QNT) After CHIPS Funding Win Still Looks Undervalued On The Bull Case
Quantinuum (QNT) shares are back in focus after the company finalized a US$100 million funding agreement with the U.S. Department of Commerce’s CHIPS R&D Office, aimed at quantum semiconductor research and manufacturing.
Quantinuum’s latest CHIPS funding win lands after a choppy run for the stock, with the share price down 31.66% over the past 30 days and 18.80% year to date. The 1-day share price return of 0.74% hints that selling pressure may be easing as investors digest fresh deals with Aramco and a busy conference schedule.
Scan beyond Quantinuum and compare this CHIPS backed quantum story with other potential beneficiaries across 89 AI infrastructure stocks.
Quantinuum now trades at a steep discount to both analyst targets and intrinsic value estimates after a sharp pullback. Is that gap a genuine opportunity, or a warning that the market’s caution still has teeth?
Most Popular Narrative: 50.3% Undervalued
On the most followed narrative, Quantinuum’s fair value of $98.75 sits far above the last close at $49.03, which puts a spotlight on the growth assumptions behind that gap.
The CHIPS R&D letter of intent for up to US$100 million and joint development with a global electronics manufacturer support scaled manufacturing and a diversified supply chain. This can improve cost efficiency and help protect net margins as system volumes and complexity rise.
Want to know what kind of revenue ramp, margin shift and earnings multiple need to line up for that valuation to stack up? The narrative leans on rapid top line expansion and a future profit profile that looks very different from today. The full story connects those projections into one number that sits almost twice the current Quantinuum share price.
Result: Fair Value of $98.75 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, this Quantinuum story can shift quickly if the heavy Q2 2026 GAAP loss, or any delay in the Sol and Apollo roadmap, stretches the investment phase.
Find out about the key risks to this Quantinuum narrative.
Another View on Quantinuum’s Valuation
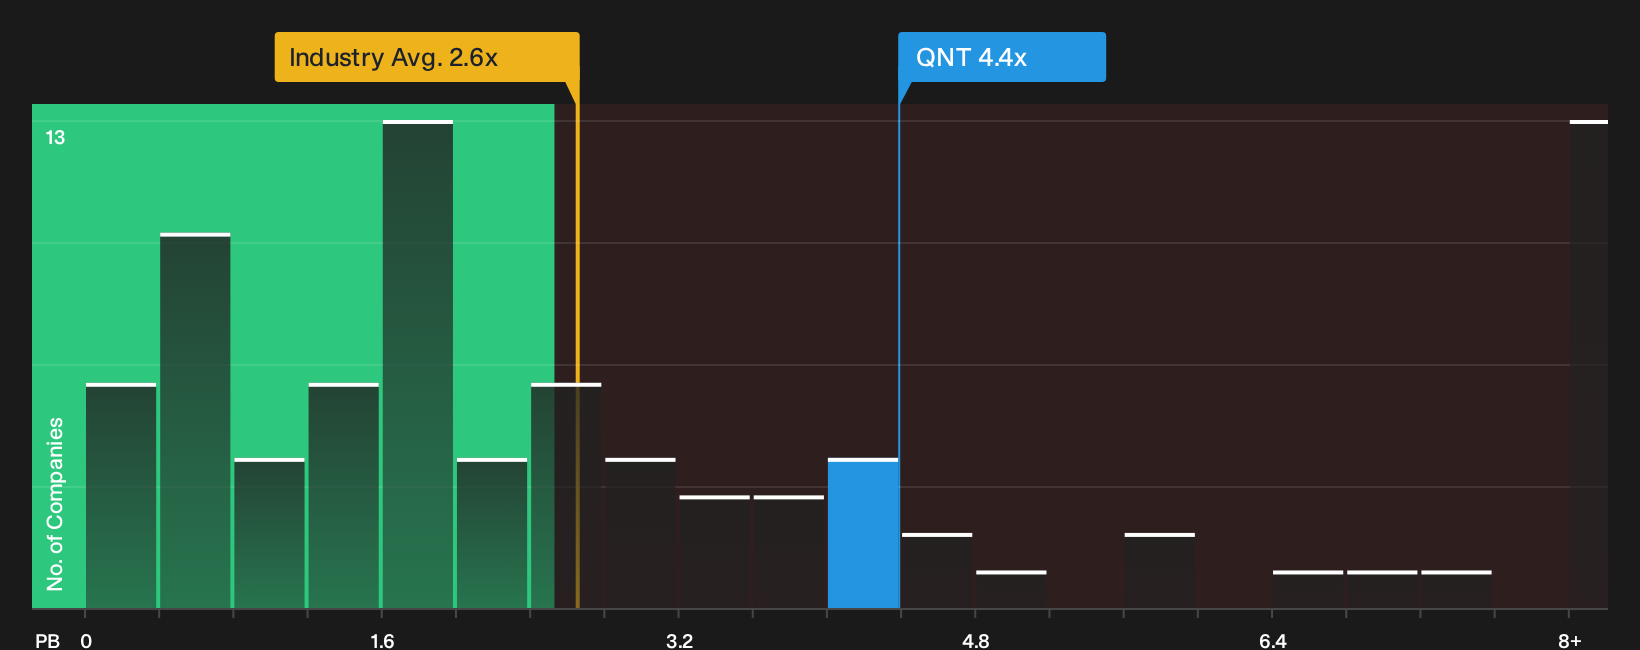
On multiples, Quantinuum looks expensive, with a P/B of 4.4x versus 2.6x for the US IT sector and 2.1x for peers. That premium means less room for error if expectations disappoint, even with the stock trading below fair value estimates. Which signal do you lean on: the relative valuation multiples or the fair value estimates?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Quantinuum so far? If you want to move fast and rely on your own judgment, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more Quantinuum style ideas?
If Quantinuum has sharpened your thinking, do not stop here. Fresh opportunities often emerge where strong fundamentals, cleaner balance sheets and sharper pricing power intersect.
- Target companies with strong cash generation and marked-down share prices by scanning the 31 high quality undervalued stocks.
- Focus on resilience first by checking out the 11 resilient stocks with low risk scores before capital flows into the next crowded theme.
- Hunt for future leaders that are still off most radars by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com