
How Data Center Demand Will Impact Cummins Stock (CMI)
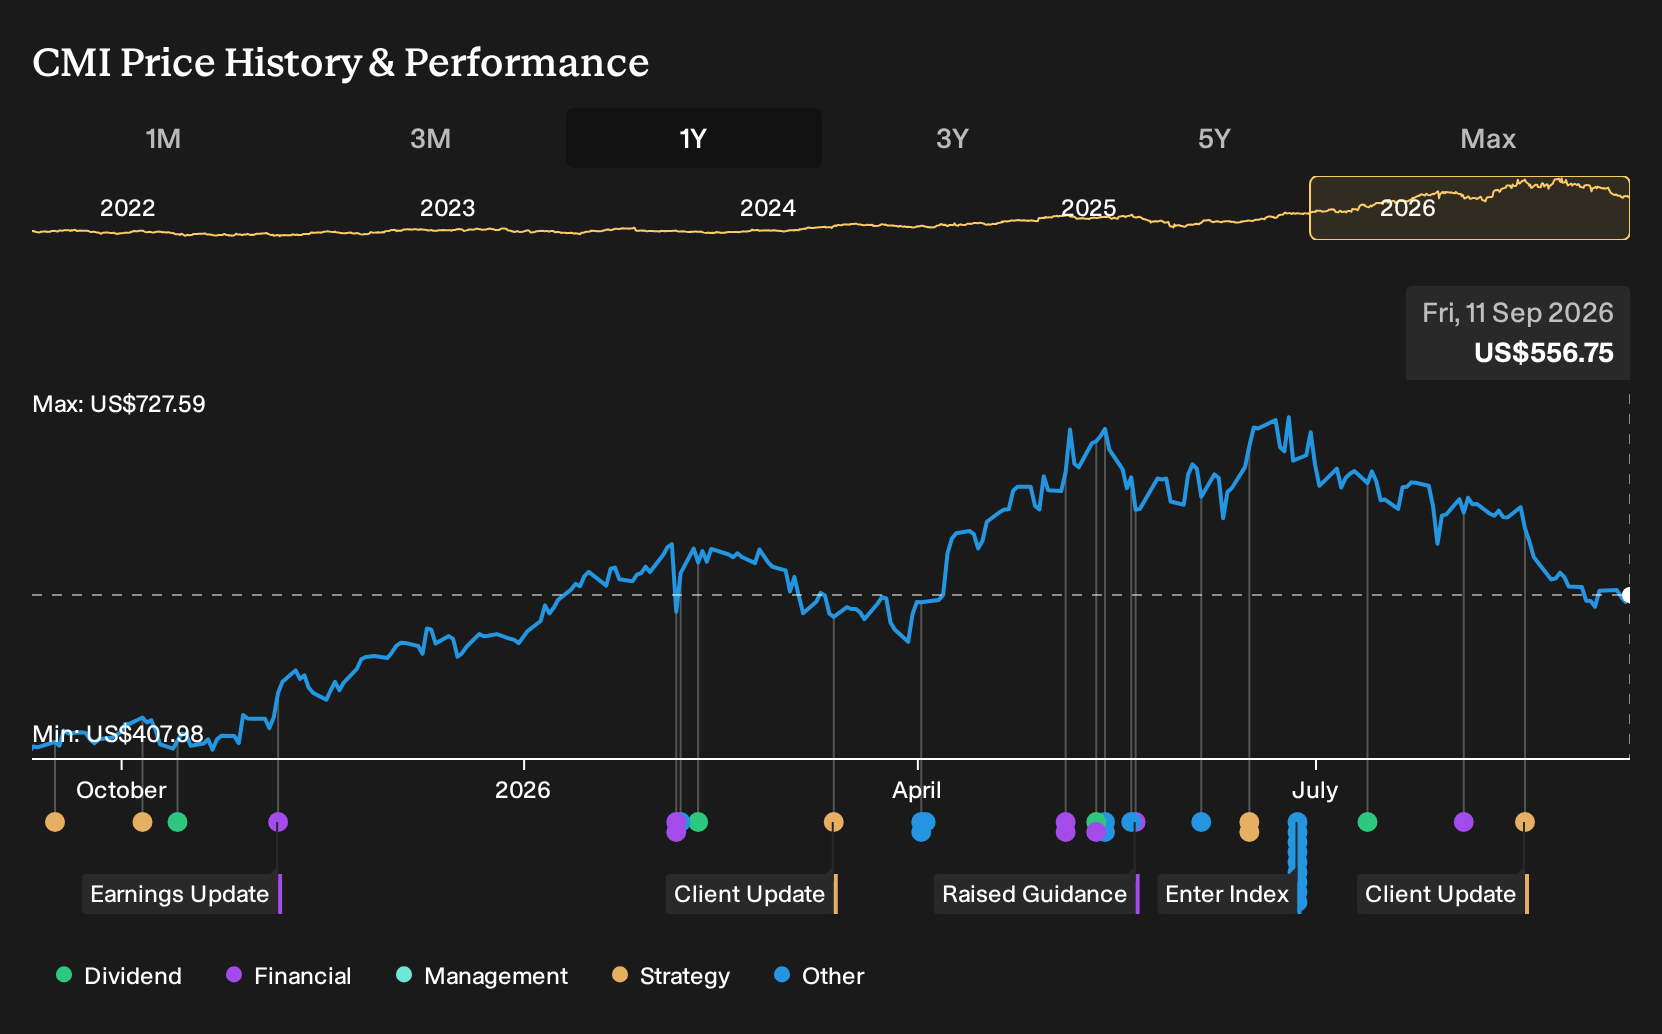
- Cummins' August 5 Q2 2026 earnings update reported revenue above expectations while adjusted EPS missed forecasts, with management emphasizing strong power generation demand tied to data center projects.
- The highlight for long term followers is Cummins leaning into power generation, where data center related orders are reshaping the mix beyond traditional truck exposure.
- We will look at how Cummins' investment narrative is influenced by surging data center driven power generation demand flagged in the earnings discussion.
Scan other power grid suppliers riding the same data center wave as Cummins through our curated list of 39 power grid technology and infrastructure stocks.
Cummins Investment Narrative Recap
To own Cummins, you need to be comfortable with a business in transition. The engine and truck related units still matter, but the real swing factor is how effectively Power Systems and data center driven generation can offset softer North American truck demand and regulatory uncertainty around EPA27 and tariffs.
The August Q2 update underlined that point. Revenue beat but adjusted EPS missed, which keeps execution in focus rather than changing the core near term story. The key catalyst is still converting Cummins' multiyear power generation backlog into high quality margins. The main risk remains a prolonged slump in heavy and medium duty truck cycles combined with rising competition in cleaner power solutions.
The most relevant recent development is management's commentary on strong power generation demand tied to data centers during the August 5 Q2 2026 call. That message matters because Cummins is leaning on Power Systems to balance cyclicality in engines and components while also funding Accelera and other low emission bets.
For you as a shareholder, the hinge issue is execution. Cummins needs to bring planned capacity expansions online, work through its two year plus backlog efficiently, and keep costs in check as it manages regulatory and tariff complexity. If the firm delivers on those operational tasks, data center linked orders could remain a central catalyst while it works through truck market and Accelera profitability risks.
Cummins data center story through the numbers
Cummins' narrative projects US$44.2b revenue and US$5.3b earnings by 2029. This assumes revenue grows at 9.3% per year and earnings rise by about US$2.6b from the current US$2.7b level.
Uncover how Cummins' fair value indicates a 34% potential upside to its current price, which could narrow quickly if data center sentiment spreads across the sector.
Exploring Other Perspectives
Power generation capacity expansion is the big swing factor in the more optimistic Cummins story. The highest analysts leaned on those projects and HELM platforms to justify revenue reaching about US$49.7b and earnings near US$6.2b by 2029. You can treat today’s data center update as a fresh test of those pre news assumptions.
Explore 3 other Cummins fair value estimates, including one that suggests as much as 62% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cummins research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cummins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cummins' overall financial health at a glance.
Looking for more investment ideas beyond Cummins?
If the Cummins story has you thinking about portfolio balance, use the Simply Wall St Screener to line up a broader watchlist built around the traits that matter most to you.
- For investors who want quality at a discount, start with a focused group of 31 high quality undervalued stocks that combine strong fundamentals with prices that screen as attractive.
- If resilience and capital protection come first for you, narrow your search to 11 resilient stocks with low risk scores that score well on stability and financial strength.
- When the goal is long term compounding from under the radar opportunities, cast a wider net across 16 high quality undiscovered gems that pair sound balance sheets with room to grow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com