
Does Margin Improvement Change The Bull Case For DHT Holdings Stock (DHT)?
- DHT Holdings has recently reported that revenue and EBITDA margins over the past five years have moved in a way that points to efficient scaling, with consistent free cash flow margins supporting both reinvestment in the fleet and returns to shareholders.
- The business has also increased its share of the very large crude carrier market this cycle, suggesting that operational execution and disciplined capital use are helping DHT Holdings capture more trade volumes without sacrificing profitability.
- We will now look at how DHT Holdings' stronger EBITDA margins could reshape the investment narrative for investors watching this tanker owner.
DHT Holdings Investment Narrative Recap
To own DHT Holdings, you need to be comfortable with a crude tanker operator that leans into operating leverage. The big picture is simple. Earnings strength hinges on VLCC day rates, disciplined fleet deployment and how well management keeps operating costs in line. Recent margin gains and free cash flow support that story, but they do not remove the cyclicality risk.
In the near term, the key swing factor is how VLCC demand and voyage activity translate into day rates and utilization. The biggest risk is that sector oversupply or weaker crude flows squeeze those rates while DHT Holdings continues to return a large share of net income. That could limit flexibility if conditions soften.
With no fresh company announcements tied directly to this latest margin update, the most relevant reference point is still DHT Holdings' commitment to high dividend payouts alongside fleet renewal. Management has been distributing 100% of ordinary net income as quarterly dividends, even as the business invests in modern VLCCs.
For you, that combination ties the investment case and the risks together. Strong EBITDA and free cash flow can support generous distributions when the cycle is firm. At the same time, analysts expect revenue and earnings to decline over the next three years. If tanker rates roll over, that payout policy could become the pressure point and catalyst for any reset in expectations.
DHT Holdings' narrative projects US$429.6 million revenue and US$234.2 million earnings by 2029. This assumes revenue declines at 13.3% per year and earnings decrease by US$97.3 million from US$331.5 million today.
Uncover why DHT Holdings' fair value indicates an 8% potential downside to its current price that leaves little room for error.
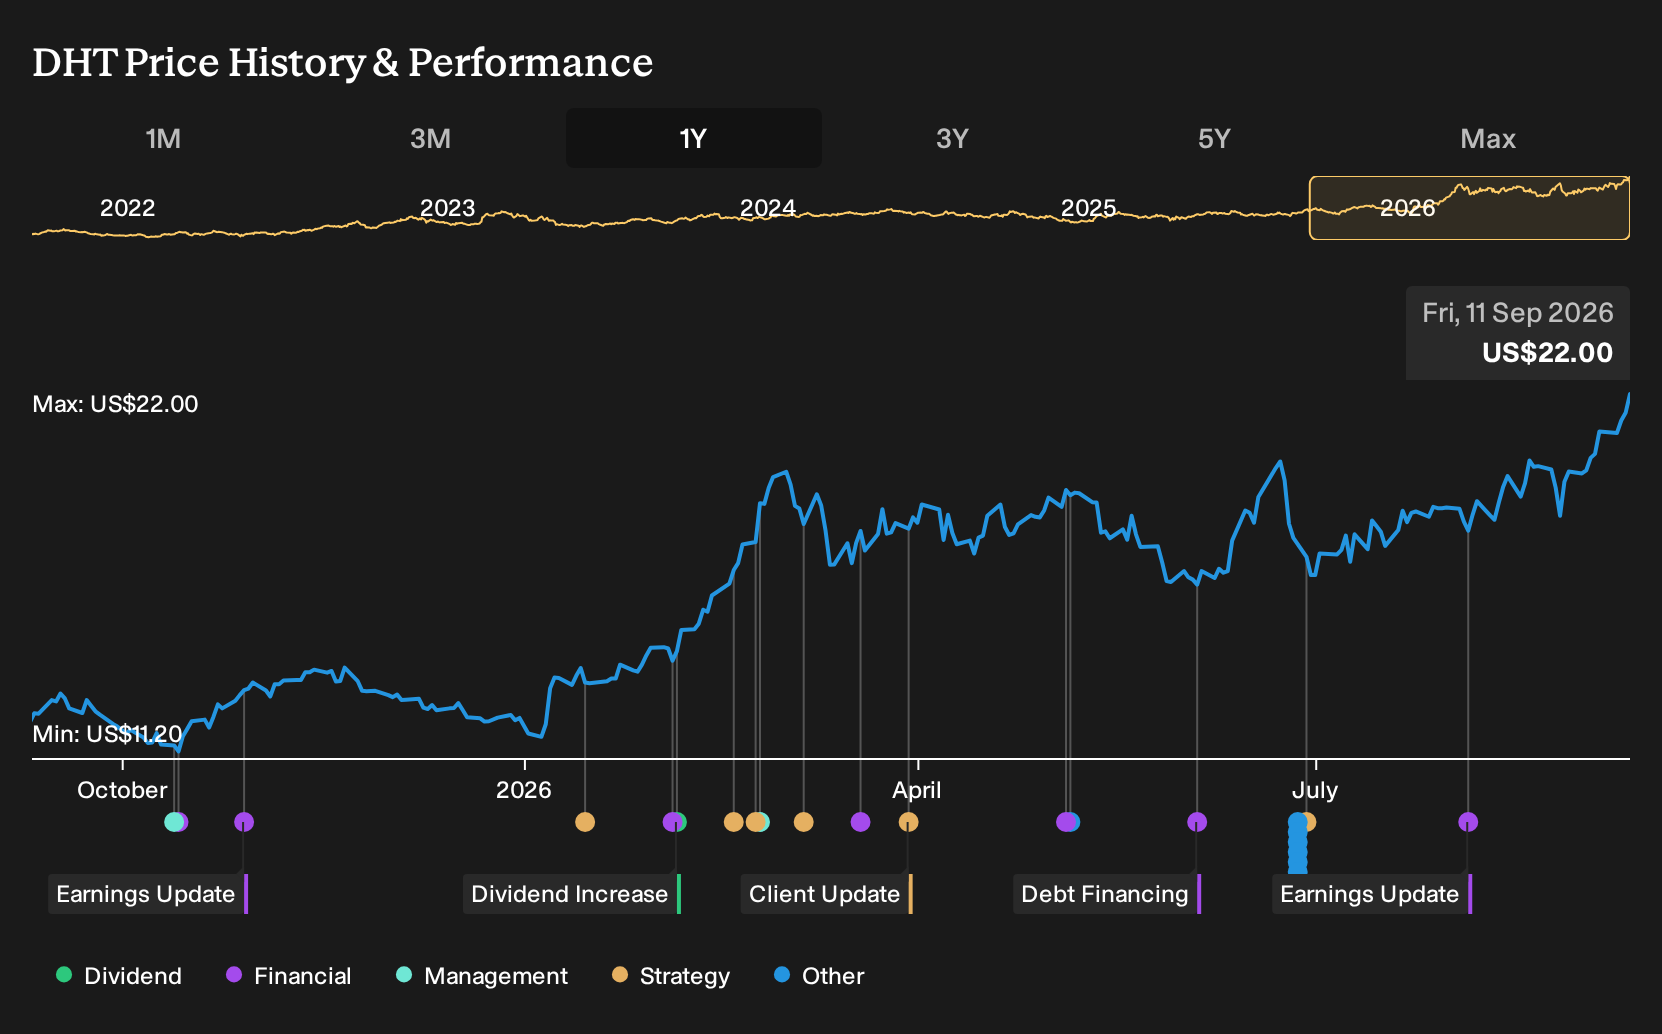
Exploring Other Perspectives
One alternate angle on DHT Holdings focuses on earnings risk from heavier spot exposure. The most pessimistic analysts were already modeling revenue of about US$411.3 million and earnings of roughly US$203.1 million by 2029, with margins easing. That is a much harsher story than consensus and could shift again once this latest news is fully absorbed.
Explore 5 other DHT Holdings fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DHT Holdings research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DHT Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DHT Holdings' overall financial health at a glance.
Looking for more DHT Holdings style ideas?
If the DHT Holdings story has you thinking about where else efficient capital use and resilient cash generation might show up, the Simply Wall St Screener can help you scan the market in a structured way rather than relying on headlines or hunches.
- For investors who want income to do more of the heavy lifting, start with companies that offer strong payouts by checking out 6 dividend fortresses.
- If capital protection matters most to you, concentrate on businesses with healthier balance sheets by reviewing the list of solid balance sheet and fundamentals (23 results).
- When you want something less crowded, focus on underfollowed opportunities with solid fundamentals by filtering through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com