
Is Viavi Solutions (VIAV) Fully Valued As It Showcases AI And Optical Test Products?
Viavi Solutions (VIAV) drew fresh attention after using the ECOC 2026 conference in Malaga to showcase a broad suite of high speed Ethernet, AI fabric, and optical connectivity test products.
The ECOC showcase lands at a time when Viavi Solutions has seen the 1-year total shareholder return surge 222.11%, while the share price is up 113.50% year to date to US$38.75, even after a 30 day share price return that declined 10.11% and a 90 day share price return that fell 27.52%. This suggests long term momentum has been strong, but near term enthusiasm has cooled as investors reassess growth potential and risks.
Scan beyond Viavi Solutions and compare this momentum story with other hand picked 89 AI infrastructure stocks shaping the next wave of high speed data and AI networking.
After a huge run and a sharp pullback, Viavi Solutions sits at US$38.75 with investors split. Is most of the easy upside already gone, or does the current valuation still leave room?
Most Popular Narrative: 36.9% Undervalued
Analysts following Viavi Solutions see a fair value well above the recent $38.75 share price, which puts a lot of weight on future execution.
Viavi is experiencing robust and sustained demand across the data center ecosystem, with customers updating optical connectivity to 400G, 800G, and now 1.6T enabling multi-year upgrade cycles and expanding its total addressable market, which should drive structural revenue growth through 2026 and beyond.
Curious what turns those upgrade cycles into a fair value near $61? The narrative leans heavily on faster top line expansion, fatter margins, and a richer earnings multiple baked into the long range model.
Result: Fair Value of $61.43 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Viavi Solutions carries real execution risk if wireless test demand remains weak and sector wide valuation pressure on AI related optical stocks persists or worsens.
Find out about the key risks to this Viavi Solutions narrative.
Another View on Viavi Solutions Valuation
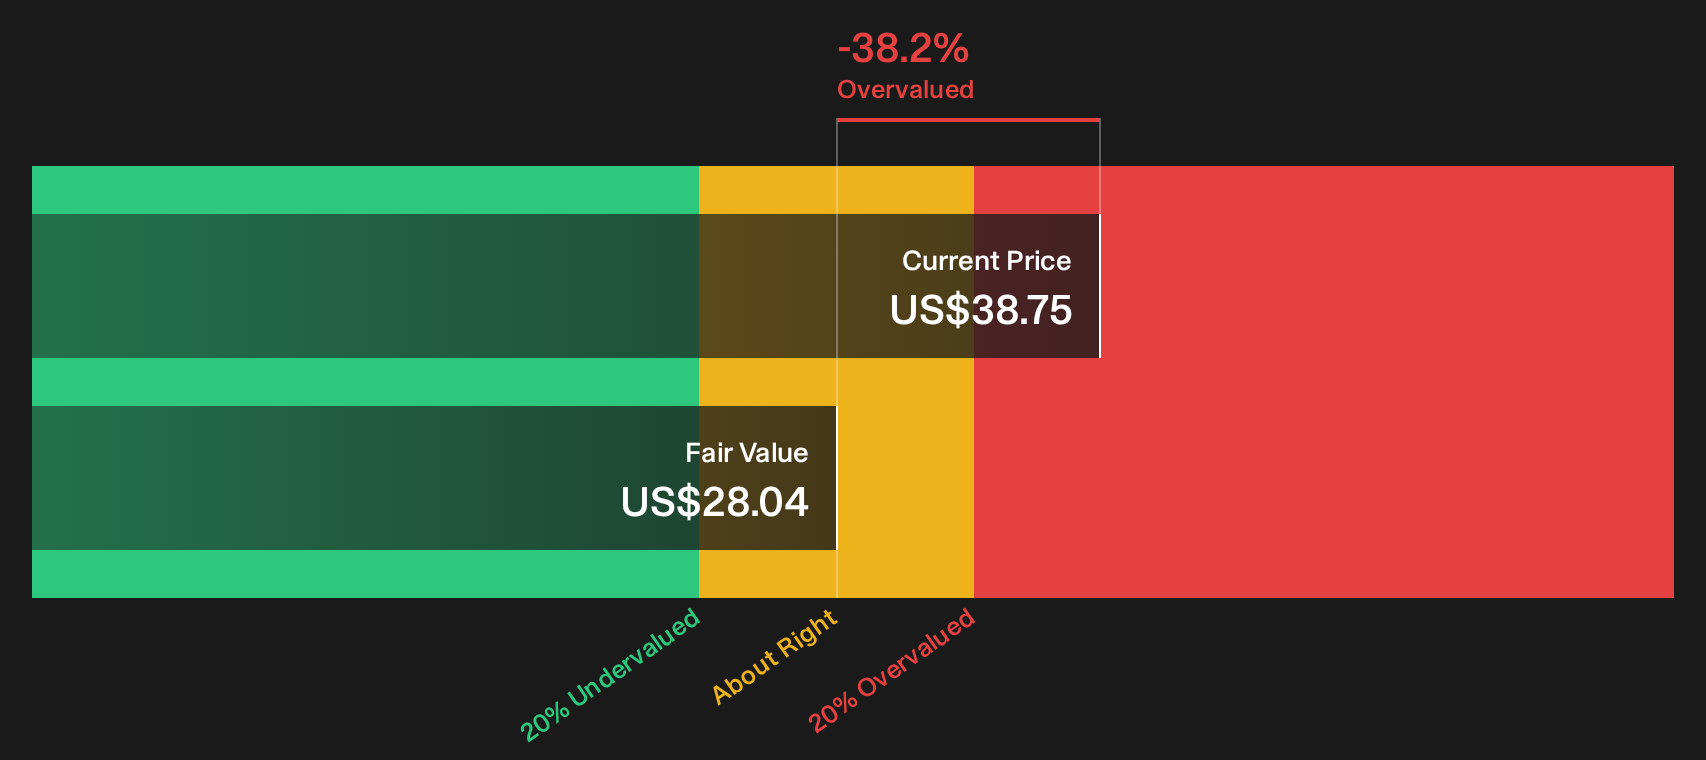
The analyst narrative presents Viavi Solutions as 36.9% undervalued based on future earnings power and a rich P/E a few years out. The SWS DCF model tells a different story. Using that approach, the current $38.75 price sits above an estimated value of $28.04. This suggests the stock may be overvalued and highlights the importance of deciding which set of assumptions you consider more reliable.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Viavi Solutions can feel confusing, so consider reviewing the numbers yourself and weighing both sides of the story. To see the full balance of potential upside and downside risks in one place, review the 2 key rewards and 2 important warning signs.
Looking for more Viavi Solutions sized ideas?
If Viavi Solutions has you thinking harder about where to put fresh capital next, do not stop here. The next opportunity could already be on a curated screener list.
- Target dependable income streams by scanning 6 dividend fortresses built around companies with yields that can play a bigger role in your portfolio cash flow.
- Hunt for quality at a discount through the 16 high quality undiscovered gems that pair solid fundamentals with quieter investor attention.
- Strengthen portfolio resilience by focusing on the 11 resilient stocks with low risk scores that aim to balance returns with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com