
InnovAge Holding (INNV) Following Profitability Turn And 2027 Outlook Is It Fully Valued
Why InnovAge Holding’s latest earnings matter to investors
InnovAge Holding (INNV) just posted fourth quarter results that shifted the business from a small loss to a US$8.29 million profit, while management also outlined revenue expectations for fiscal 2027.
The quarter that ended June 30, 2026 came with US$261.95 million in revenue, up from US$221.42 million a year earlier. Earnings per share from continuing operations moved to US$0.06, compared with a basic and diluted loss of US$0.01 per share in the prior period.
Investors have reacted strongly to InnovAge Holding’s return to profitability and fiscal 2027 revenue guidance, with the share price at US$10.75 and a year to date share price return of 107.13%. The 1 year total shareholder return of 136.26% points to powerful momentum that has built over the past several quarters rather than just the past few days.
Spot emerging momentum stories around InnovAge Holding by scanning our hand picked 16 high quality undiscovered gems that share improving fundamentals and strengthening investor interest.After a 107% year to date jump and a share price now near analyst targets, InnovAge Holding presents a straightforward question: Is this a moment to lean in, or a time to wait for a cheaper shot at the story, as the valuation section explores?
Most Popular Narrative: 7.5% Overvalued
Analysts following InnovAge Holding see fair value at $10 per share using a 7.24% discount rate, which sits slightly below the recent $10.75 close.
Enrollment growth is accelerating, supported by strong underlying demand for care models that allow seniors to remain at home, directly benefiting from the expanding 65+ demographic in the U.S.; this positions the company for robust future revenue expansion.
Read the complete narrative. Read the complete narrative.
Want to see what backs that view? The narrative leans heavily on a steady climb in top line, a sharp swing in profitability, and a future earnings multiple that assumes investors stay comfortable with this healthcare model.
Result: Fair Value of $10 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, InnovAge Holding faces real pressure from rising care and compliance costs, as well as from losses tied to new center openings that could weaken the upbeat narrative.
Find out about the key risks to this InnovAge Holding narrative.
Another view of InnovAge Holding’s valuation
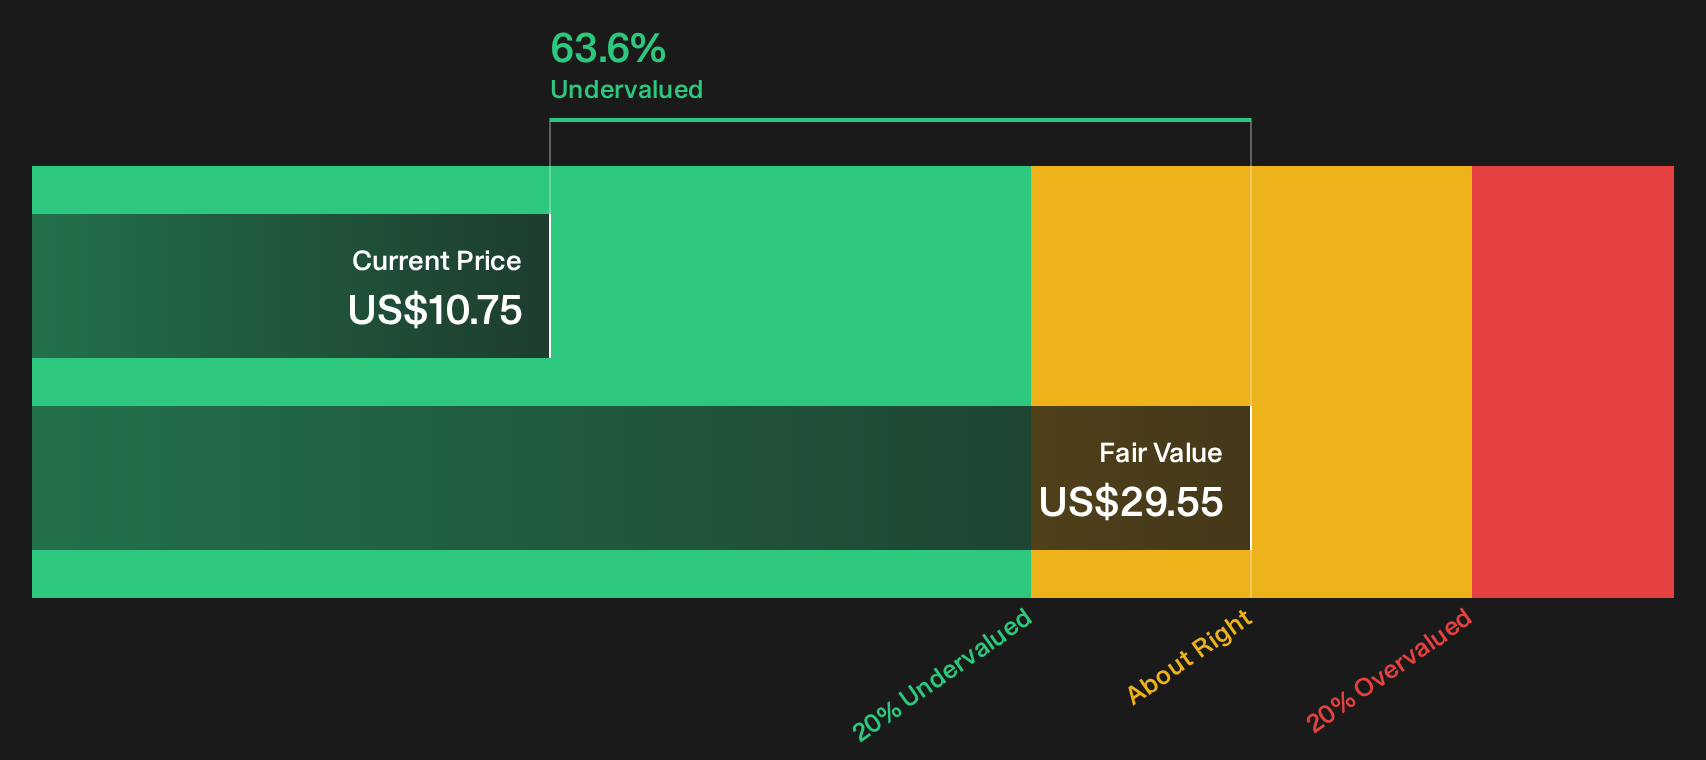
The analyst narrative frames InnovAge Holding as about 7.5% overvalued around $10 per share, based on future earnings and an implied P/E of roughly 11x. A different lens tells a very different story. Our DCF model suggests the stock trades well below an estimated future cash flow value of $29.55, which points to a wide gap between price and long term cash generation. That raises a simple question for investors: Which signal carries more weight in your process, earnings multiples or cash flows?
Our DCF model is fully laid out so you can see every moving part yourself, rather than relying only on the headline number. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around InnovAge Holding is clearly optimistic right now. Move quickly, review the full data set, and pressure test every bullish talking point against your own checklist using the 3 key rewards.
Looking for more investment ideas beyond InnovAge Holding?
If InnovAge Holding has sharpened your focus, do not stop here. A few minutes with targeted screeners can surface opportunities you would otherwise never see.
- Hunt for mispriced quality by scanning a 31 high quality undervalued stocks that align solid fundamentals with compressed valuations and cleaner balance sheets.
- Prioritise resilience by filtering for 11 resilient stocks with low risk scores that score well on financial strength and business stability, so setbacks are less likely to derail your plan.
- Get ahead of the crowd by digging into a 21 elite penny stocks with strong financials where improving fundamentals meet early stage interest, before attention and liquidity potentially ramp up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com