
Doova Launch Might Change The Case For Investing In Tuya (TUYA)
- Tuya Smart used IFA 2026 to showcase its latest physical AI portfolio, including the debut of Doova, an AI home companion robot for independently living seniors, alongside AI Home, AI Energy, AI Robot ecosystems, and a full-stack Matter offering.
- The breadth of Tuya's physical AI, energy management, and developer tools at IFA 2026 highlights a push toward higher-value services that tie hardware, software, and recurring platforms into a single operating model.
- This article examines how Tuya's investment narrative is influenced by Doova's senior-focused AI companion role within a broader physical AI push.
Tuya Investment Narrative Recap
To own Tuya, you need to believe its AI cloud and physical AI push can keep drawing developers and hardware partners into a single, sticky ecosystem. The near term focus is on whether products like Doova and AI Energy convert into higher value, recurring software and services, not just one off hardware wins.
The key short term catalyst remains execution on higher margin SaaS and value added services while sustaining the recent profit improvement and revenue growth. The biggest risk still sits with hardware heavy exposure and global trade and supply chain uncertainty. The IFA news does not fundamentally change those near term drivers or threats yet.
Among the IFA announcements, Doova matters most for Tuya’s story. It takes the AIoT platform into senior care, home monitoring, and smart home control in a single device, which directly tests whether the firm can turn complex, multi device living spaces into one coherent subscription style experience over time.
For catalysts, Doova is a proof point for Tuya’s physical AI thesis and its ability to support higher value services on top of a broad device base. It also exposes the business to more competition, regulatory questions around data and safety in elder care, and the usual hardware margin pressure if copycat products flood cost sensitive markets.
Tuya's current analyst narrative points to revenues of $466.4 million and earnings of $92.7 million by 2029, based on an assumed 12.4% yearly revenue growth rate and an earnings increase of about $30.1 million from $62.6 million today.
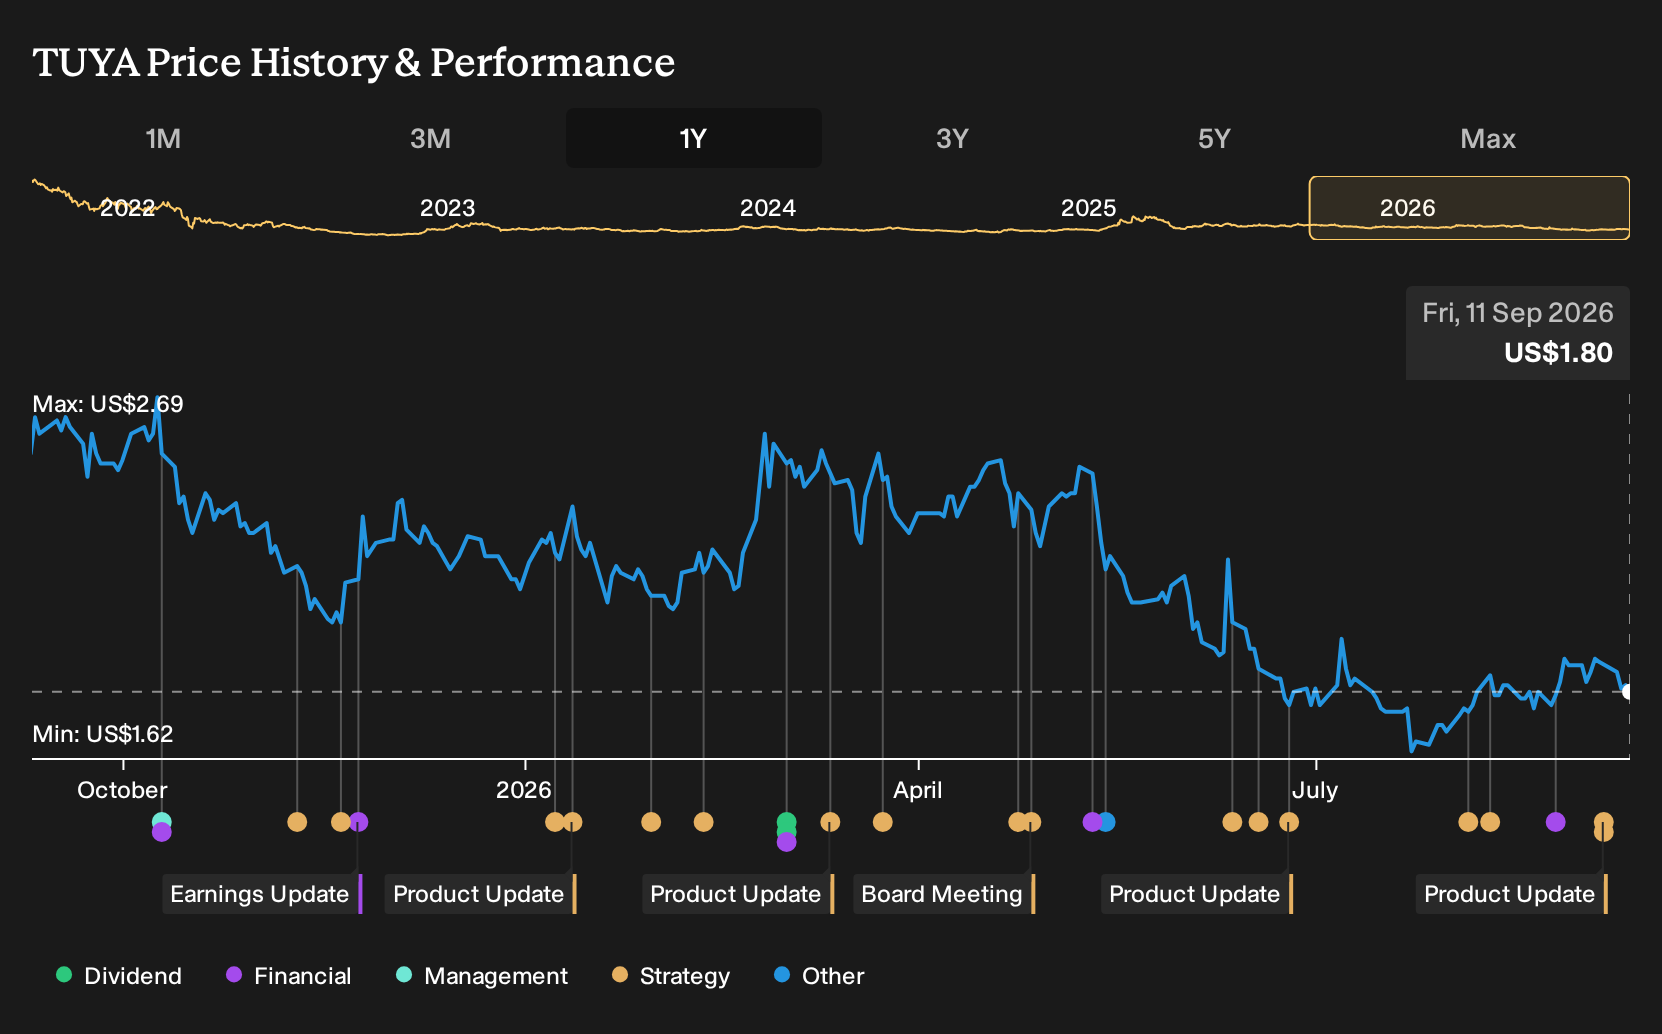
Uncover why Tuya's fair value points to a 90% potential upside to its current price that may not remain available for long.
Exploring Other Perspectives
One alternate view focuses on Tuya’s dependence on a small pool of premium PaaS customers. Under this more cautious lens, analysts were only penciling in revenue of about $478.4 million and earnings of $96.8 million by 2029 before the Doova news. That is a tighter, more reserved story. Use it as a prompt to compare multiple narratives yourself.
Explore 5 other Tuya fair value estimates, including one that suggests it could be worth just $2.25!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tuya research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Tuya. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tuya's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tuya?
If Tuya's physical AI and smart home angle has sharpened your thinking, it can help to compare it with other businesses that fit clear financial themes. The Simply Wall St screener gives you a way to filter the wider market down to a short list that matches the kind of balance sheets, income profiles, or payout styles you want to focus on next.
- If capital preservation is a priority, start by scanning a pool of companies that score well on resilience and financial risk using the 11 resilient stocks with low risk scores.
- For readers hunting for quality at a reasonable entry point, filter for companies that combine stronger fundamentals with valuations that may look appealing through the 31 high quality undervalued stocks.
- Income focused investors who care about consistency as much as yield can zero in on potential cash generators through a curated set of 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com