
Dauch (DCH) Stock Looks Discounted After a 25% Five Year Slump
Dauch comes to this valuation check-up with a mixed record. The stock has declined 25% over the past 5 years, yet the current market multiples and broader checks still lean toward the shares looking cheap rather than fully priced in.
- The 25% share price decline over 5 years leaves recent buyers effectively underwater and raises the question of whether the current level already reflects the past setbacks.
- Future earnings power can support the present tag if management converts revenue into steadier cash flow, while execution missteps or heavier capital needs may cap how much investors are willing to pay for the stock.
- The broader valuation checks lean cheap, with Dauch scoring a high value rating of 5 out of 6 tests that compare the share price to fundamentals.
The issue now is whether Dauch's current valuation reflects a genuine discount or simply matches the company’s recent track record.
Compare Dauch's value score and long term share price pullback with a curated list of 31 high quality undervalued stocks that also trade on what may be discounted fundamentals.
Is Dauch a Bargain on Sales?
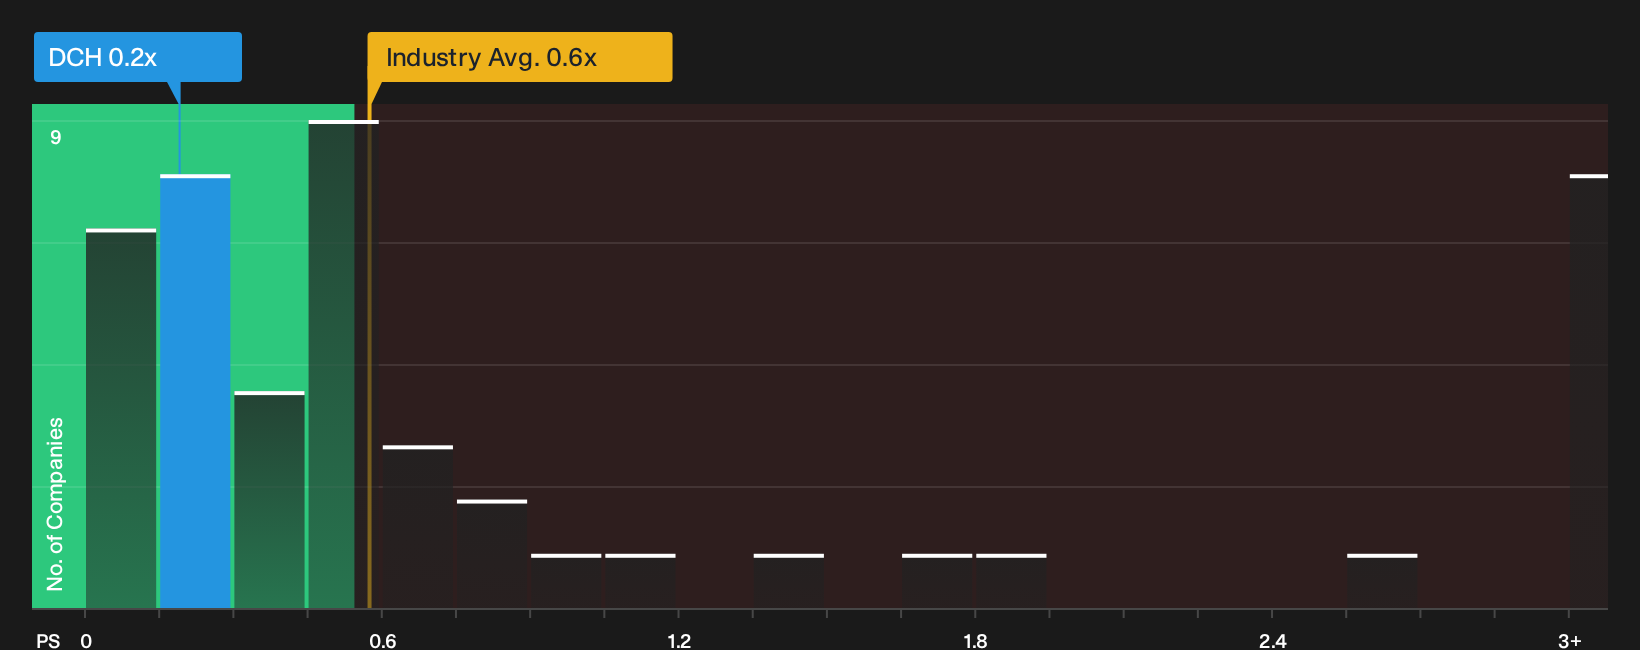
P/S works well for Dauch because investors are still weighing the revenue base against uneven free cash flow. On this yardstick, the stock trades on a P/S of about 0.2x, compared with an Auto Components industry average of roughly 0.6x and a peer group closer to 1.0x. That is a large gap for a company that still generates meaningful top line, even if cash generation has been lumpy.
The fair P/S ratio implied by the broader model is about 0.5x. This already reflects Dauch's specific risks and business profile. The current multiple sits well below that level, which indicates that investors are assigning a deep discount to the shares relative to what the framework suggests for the business and its sector.
On the preferred P/S measure, Dauch appears undervalued compared with both its tailored fair ratio and the wider Auto Components group.
See what the numbers say about this price — find out in our valuation breakdown.
The Dauch Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Dauch one step further by spelling out which patterns in growth, margins and earnings would need to hold for the shares to be worth meaningfully more or less than today’s price. These Narratives sit on the stock’s Community page. Each scenario links Dauch's potential catalysts and key risks to a specific fair value estimate so you can watch over time which story the business actually tracks.
One of the top community narratives on Dauch: 7% undervalued
"The acquisition of Dowlais, strategic EV investments, and strong localization efforts position AAM for diversified growth, operational efficiencies, and resilient profitability amid evolving industry trends..."
Read one of the top narratives on Dauch
Do you think there's more to the story for Dauch? Head over to our Community to see what others are saying!
The Bottom Line
Dauch screens as undervalued on its preferred P/S yardstick, which points to investors pricing in a heavy margin of caution around cash conversion and execution. The gap between the current multiple and the modelled fair ratio only closes if the business turns its existing revenue base into more reliable free cash flow. That is the crux of the debate from here. The key question is whether the discount reflects a genuine opportunity or whether the market is correctly bracing for bumpier profitability and ongoing capital demands.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com