
Is Rising French Bond Yields Altering The Investment Case For Dior Stock (ENXTPA:CDI)?
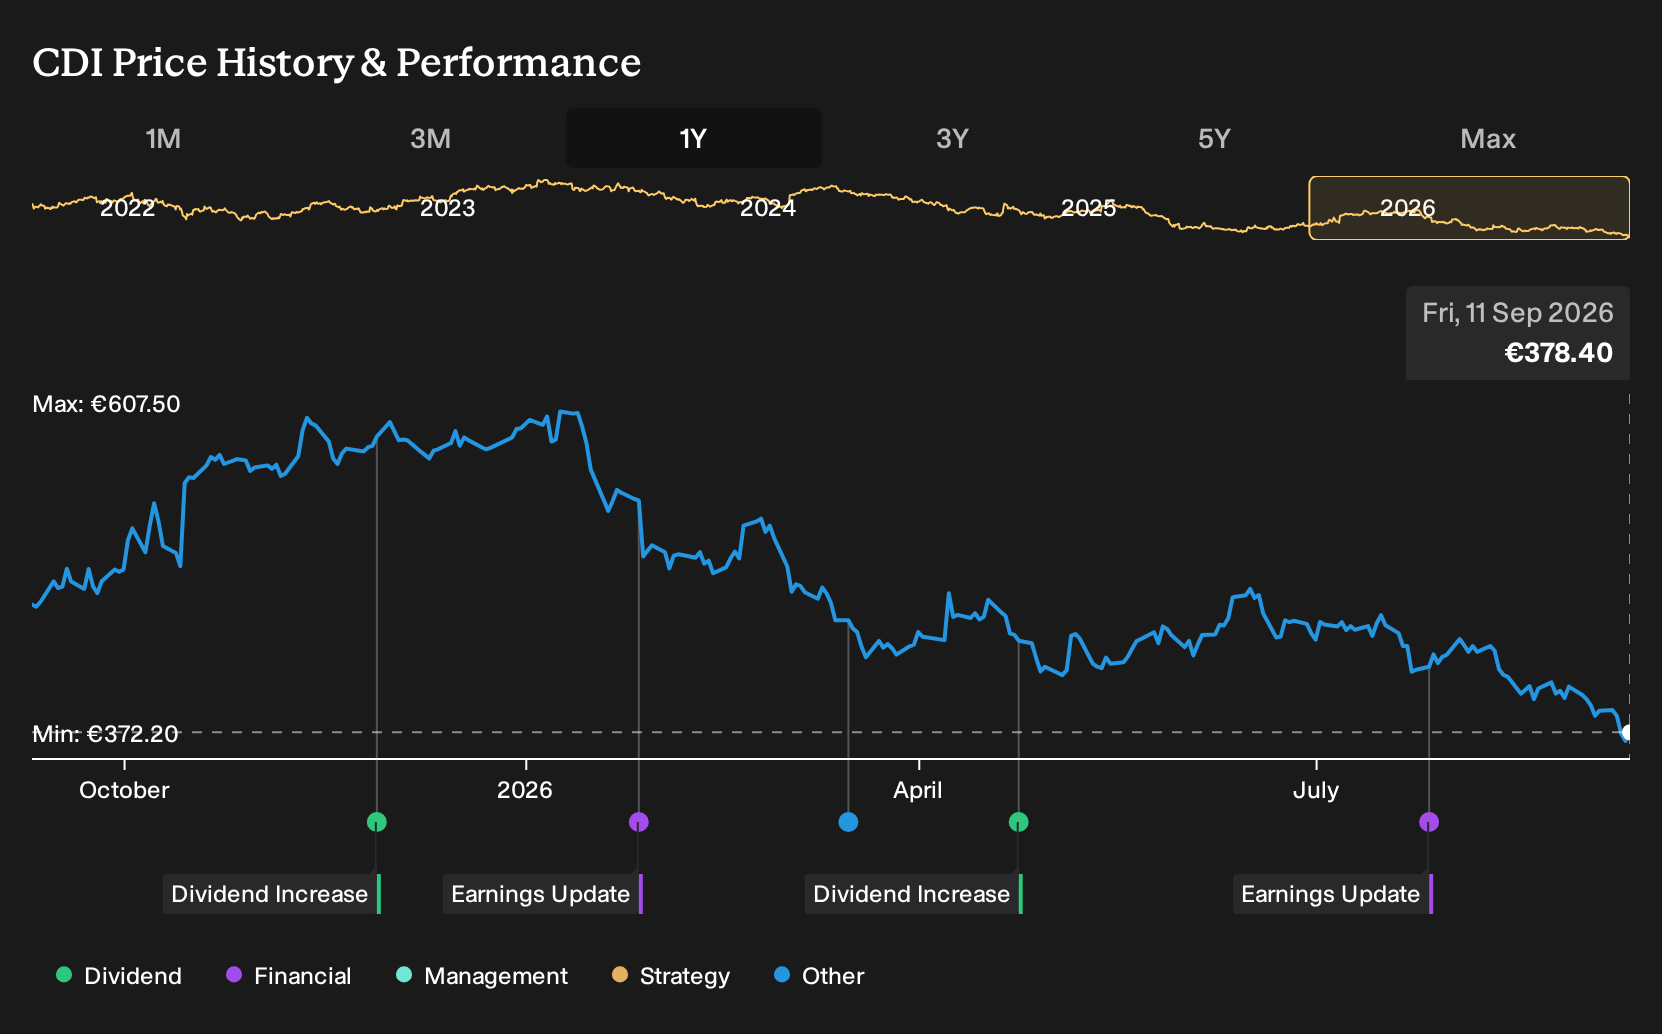
- Christian Dior was caught in a broad pullback in French luxury stocks after French 10-year government bond yields reached 4.1% and concerns persisted over demand from China.
- The reaction highlights how closely Dior’s valuation and investor expectations are tied to sector-wide sentiment on global high-end spending, rather than company-specific news alone.
- We will now look at how this sector-driven pressure from rising French bond yields might influence Christian Dior’s broader investment narrative.
Scan how other high-end names react to similar macro shocks by reviewing our curated 185 high quality undervalued stocks, which combines quality fundamentals with more grounded expectations.
What Is Christian Dior's Investment Narrative?
The big belief behind Christian Dior is simple. You need to think global luxury demand holds up across fashion, accessories, beauty, wines and spirits, and high end retail, even as cycles turn. This is a sprawling group with €79,641.0m in revenue across multiple product categories and regions. Execution is mostly about keeping brands desirable, managing pricing power, and running a heavy physical store footprint alongside e commerce efficiently.
The latest drop in Christian Dior’s share price after French 10 year yields hit 4.1% and worries around China resurfaced sits squarely in that context. It looks more like pressure on sentiment than a direct hit to day to day operations or near term catalysts. The bigger watchpoints remain earnings that have edged down 1.6% per year over five years, an unstable dividend record, and reliance on higher risk external funding.
Even so, there is a less comfortable angle to this story that only really comes into focus when you look at how that funding intersects with ...
There's only one way to know the right time to buy, sell or hold Christian Dior. Head to Simply Wall St's company report for the latest analysis of Christian Dior's Fair Value.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly €414 to about €971, which is a wide bracket for Christian Dior. That spread already shows how far opinions can stretch. These figures also predate the recent French bond yield move, so treat them as one reference point and compare with other angles before acting.
Explore 2 other Christian Dior fair value estimates, including one that suggests it could be worth just €413.95.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Christian Dior research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Christian Dior. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Christian Dior's overall financial health at a glance.
Looking For More Investment Ideas Beyond Christian Dior?
If the Christian Dior story has you thinking about where else to put capital to work, the Simply Wall St Screener can help you compare different opportunities using the same consistent set of fundamentals.
- For investors who want potential upside without stretching quality too far, review a curated pool of undervalued companies through the 185 high quality undervalued stocks.
- If capital preservation is a priority, focus on businesses that pair resilience with measured risk using the 98 resilient stocks with low risk scores.
- For those hunting beyond the usual large caps, scan a focused universe of strong fundamentals with the 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com