
Pharvaris (PHVS) Could Be Deeply Undervalued As Phase 3 HAE Data Strengthens Its Case
Pharvaris (PHVS) put fresh clinical data in front of investors after its CHAPTER-3 Phase 3 trial of deucrictibant XR met all primary and secondary endpoints in preventing hereditary angioedema attacks.
Pharvaris shares, now trading at $38.02, have been on a strong upswing, with a 90 day share price return of 23.76% and a year to date share price gain of 43.58%. The 1 year total shareholder return of 63.88% points to momentum that has been building rather than fading.
Spot fresh momentum in Pharvaris and then scan for other potential breakout stories across rare-disease and high-impact therapeutics with 16 high quality undiscovered gems.Pharvaris now trades at a steep discount to both analyst targets and estimated fair value after the CHAPTER-3 surge. Is that gap offering mispricing, or is it simply reflecting the risk that still sits in the story?
Preferred Price-to-Book Multiple of 7.7x: Is it justified?
Pharvaris now trades on a P/B ratio of 7.7x, which looks rich next to both its own lack of current revenue and the sector it belongs to.
The price to book figure compares the market value of the equity with the net assets on the balance sheet. For a late stage biopharmaceutical group like Pharvaris, that often means investors are paying well above the accounting value of cash and development assets in anticipation of future products and potential cash flows.
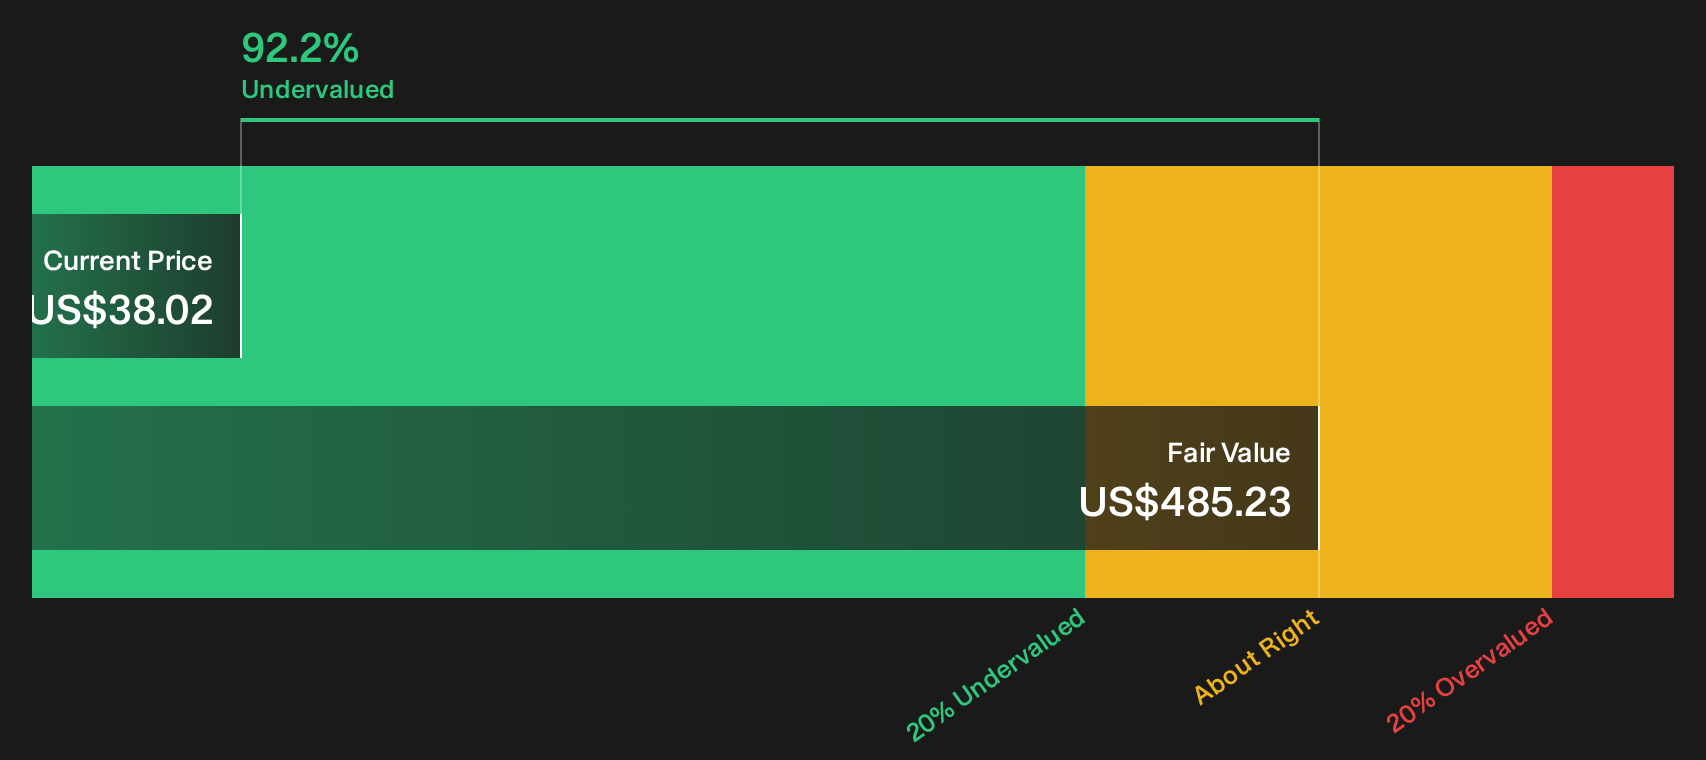
Pharvaris is currently loss making, with a reported net income loss of $170.9m and less than $1m in sales, so this premium P/B level reflects expectations that are not yet matched by current earnings. The SWS DCF model also points to a very large gap between the last close of $38.02 and an estimated future cash flow value of $485.23, which is far above the level implied by the accounting book value.
Set against peers, that 7.7x P/B compares to a 3.2x average for similar companies and 2.4x for the broader US pharmaceuticals group. This represents a strong premium for a business that still reports zero revenue. Investors are effectively paying several turns more on book value than the sector in exchange for exposure to Pharvaris's late stage hereditary angioedema program and the growth forecasts embedded in analyst models.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 7.7x (OVERVALUED)
Still, the Pharvaris story carries real uncertainty around ongoing losses of €170.9m and the execution risk tied to a single late stage deucrictibant program.
Find out about the key risks to this Pharvaris narrative.
Another View on Pharvaris Valuation
The P/B discussion presents Pharvaris as expensive, yet the SWS DCF model suggests the opposite. On that cash flow lens, the stock at $38.02 sits well below an estimated value of $485.23, which frames the shares as deeply undervalued rather than stretched.
For anyone weighing which signal to trust, the gap between book-based pricing and cash flow estimates raises a simple question: Is the market overpaying for assets today, or underpricing the long-term deucrictibant cash flow story that the DCF is pointing to?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pharvaris for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Volatile or undervalued, Pharvaris clearly splits opinion and the only way to weigh that tension properly is to study the numbers yourself and then compare that with our read on the 2 key rewards and 1 important warning sign.
Looking for more Pharvaris style investment ideas?
If Pharvaris has sharpened your interest in high impact opportunities, do not stop here. Use the Simply Wall St screener to spot other compelling setups before they move.
- Target potential bargains by scanning our hand picked universe of quality companies trading below estimated value through the 31 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with robust yields and payout records using the 6 dividend fortresses.
- Prioritise resilience by filtering for companies with healthier balance sheets and stronger fundamentals via the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com