
How Boxer Shutdown Will Impact Alamo Group (ALG) Investors
- Alamo Group has already ceased production of its Boxer branded product line following a portfolio review, and expects to record approximately US$7.0 million to US$10.0 million of related charges in the third quarter of 2026, driven by factors such as inventory valuation and equipment returns.
- The decision to exit Boxer products signals management’s willingness to prune underperforming offerings. This could reshape future product mix and cost structure, as well as how investors assess the quality of Alamo Group’s earnings.
- We will examine how Alamo Group's investment narrative is affected by the Boxer line shutdown and the projected third quarter impairment charges.
Compare how Alamo Group’s portfolio clean-up stacks up against other machinery players tightening their product focus by reviewing our hand picked 38 robotics and automation stocks for your next ideas list.
Alamo Group Investment Narrative Recap
To own Alamo Group, you need to believe the core equipment franchises in Vegetation Management and Industrial Equipment can keep generating solid orders from government, infrastructure, and contractor customers, even if certain niches underperform. The Boxer shutdown looks contained. The non cash US$7.0 million to US$10.0 million charge is meaningful for optics but small relative to a US$1.7b revenue base.
The more important near term swing factor still sits in execution across Vegetation Management and the large Industrial Equipment backlog, not this one product exit. A key risk remains softer spending from municipalities or industrial clients, which could magnify any internal missteps as the newer management team beds in and the CEO transition plays through.
The Boxer announcement on 8 September 2026 ties directly into that bigger story. Management is trimming a line that appears non core within a much broader portfolio that includes mowers, forestry tools, sewer cleaners, street sweepers, and snow equipment. The expected impairment is mainly accounting rather than cash, so it affects reported earnings quality more than near term liquidity.
On potential catalysts, the more interesting angle is what this implies for future product mix as Alamo Group focuses on areas with stronger demand and better contribution to margins. The risk side is that repeated portfolio write downs could chip away at confidence in capital allocation, especially with analysts already watching for execution issues during an active M&A pipeline and leadership transition.
Alamo Group's current analyst narrative points to US$1.9b in revenue and US$191.8 million in earnings by 2029, built on assumed yearly top line expansion of 4.7% and an earnings increase of about US$90.6 million from US$101.2 million today.
Uncover why Alamo Group's fair value indicates a 24% potential upside to its current price that may not last much longer.
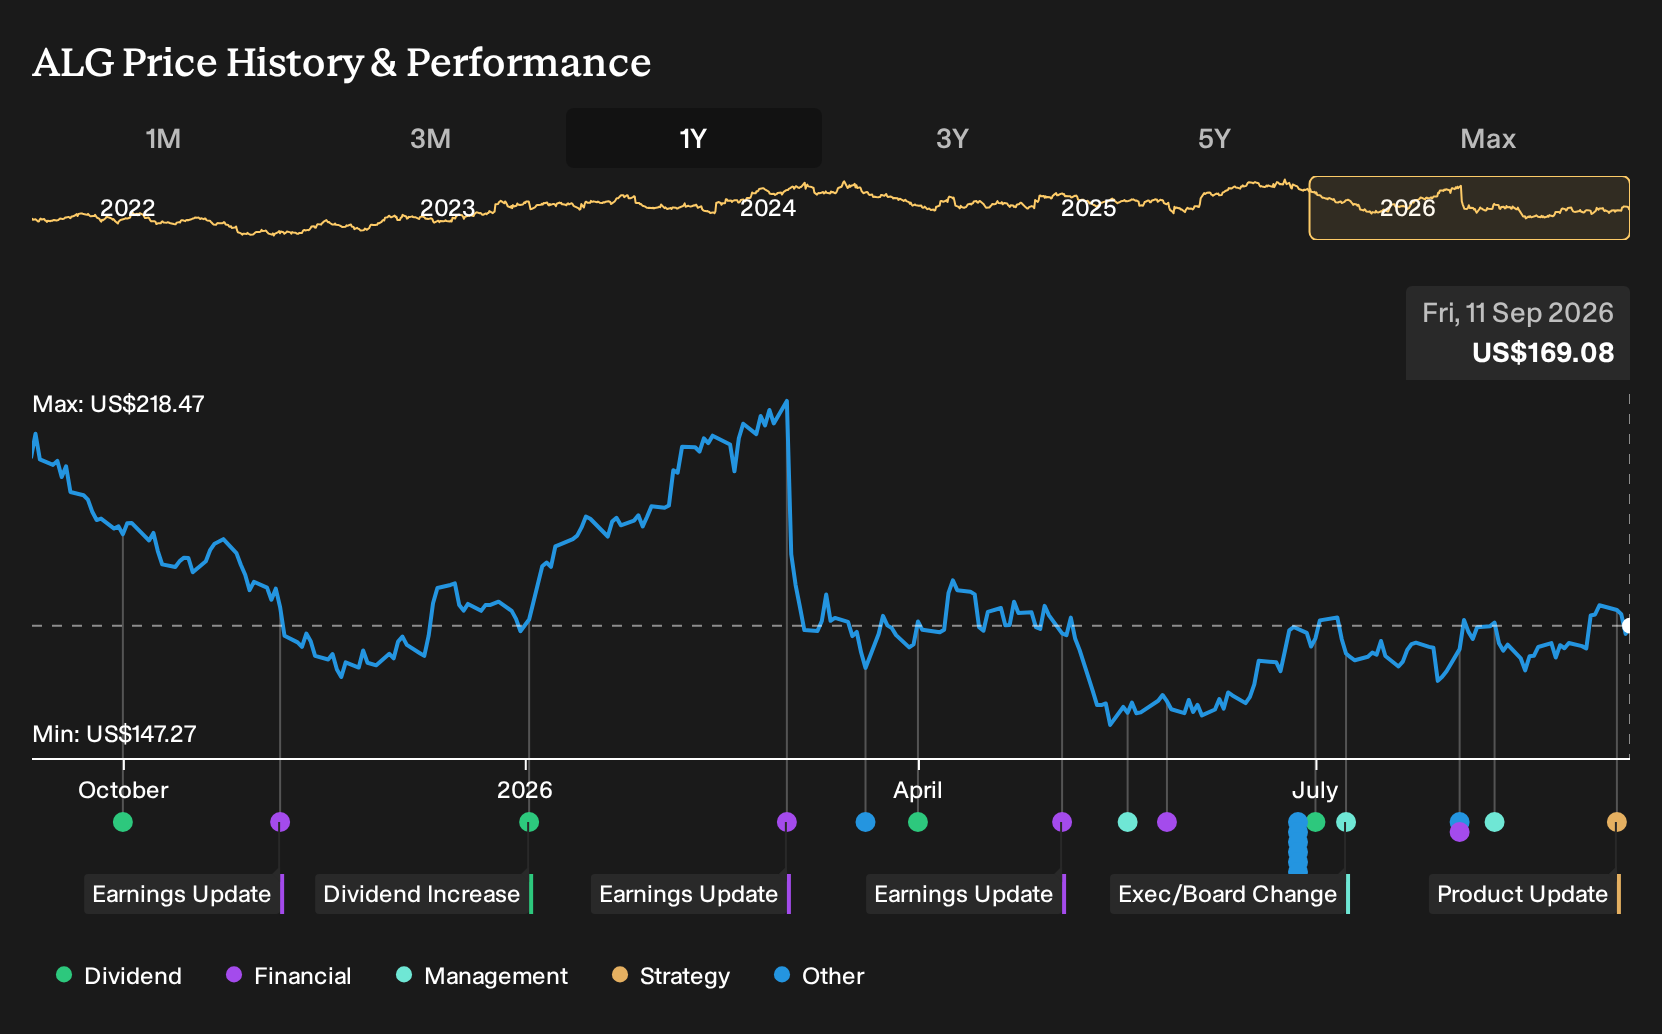
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$140 and about US$210, which hints at very different return expectations for Alamo Group. Some members focus on Industrial Equipment momentum and cash strength. Others flag Vegetation Management, municipal spending exposure, and the CEO transition as reasons to be more cautious. Use that spread to pressure test your own thesis.
Explore 2 other Alamo Group fair value estimates, including one that suggests as much as 24% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alamo Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alamo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alamo Group's overall financial health at a glance.
Looking For More Ideas Beyond Alamo Group?
Once you have a view on Alamo Group, it can help to cross check that thesis against other opportunities that fit your risk profile and return goals. The Simply Wall St Screener is built for exactly that, letting you filter the market by fundamentals rather than headlines.
- For investors hunting for higher income potential, scan for stocks that resemble yield-focused fortresses using our 6 dividend fortresses.
- If capital protection and steadier profiles matter more to you, narrow in on companies with stronger balance sheets through the list of solid balance sheet and fundamentals (23 results).
- When you want something off the beaten path with quality metrics to back it up, source fresh ideas from the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com