
Capri Holdings (CPRI) Screens 38% Undervalued, Is The Selloff Overshooting Fair Value?
Capri Holdings (CPRI) has moved sharply in recent sessions, with the share price closing at $13.89 on 12 September 2026. Recent returns show mixed momentum across the past week, month and past 3 months.
The latest bounce in Capri Holdings sits against a tougher backdrop, with the share price down 43.05% year to date and the 1-year total shareholder return declining 32.08%. This points to fading momentum and a market that is still reassessing the company’s risk and valuation profile.
Compare Capri Holdings' sharp reset with other consumer stocks that still screen well on quality and valuation by scanning our curated list of 31 high quality undervalued stocks today.
Capri Holdings now trades at a steep gap to both analyst targets and one intrinsic value estimate, raising a simple question: Is the recent selloff overshooting fair value, or are the models still playing catch up to the risk?
Most Popular Narrative: 38.4% Undervalued
On the most followed narrative, Capri Holdings screens at a wide gap between the $22.53 fair value estimate and the $13.89 last close. This puts the focus squarely on whether the earnings and margin path in that story holds up.
Supply chain optimization, targeted cost efficiencies, and strategic pricing initiatives are expected to offset tariff headwinds by fiscal 2027, supporting sustainable gross margin expansion and operating earnings growth.
Read the complete narrative. Read the complete narrative.
Want to see what is baked into that $22.53 figure? The narrative leans on a very specific mix of revenue stabilisation, margin repair, and a lower future earnings multiple. The exact blend of those assumptions might surprise you.
Result: Fair Value of $22.53 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the whole Capri Holdings story can crack if tariff costs bite harder than expected or if Michael Kors and Jimmy Choo struggle to reignite demand.
Find out about the key risks to this Capri Holdings narrative.
Another View on Capri Holdings Valuation
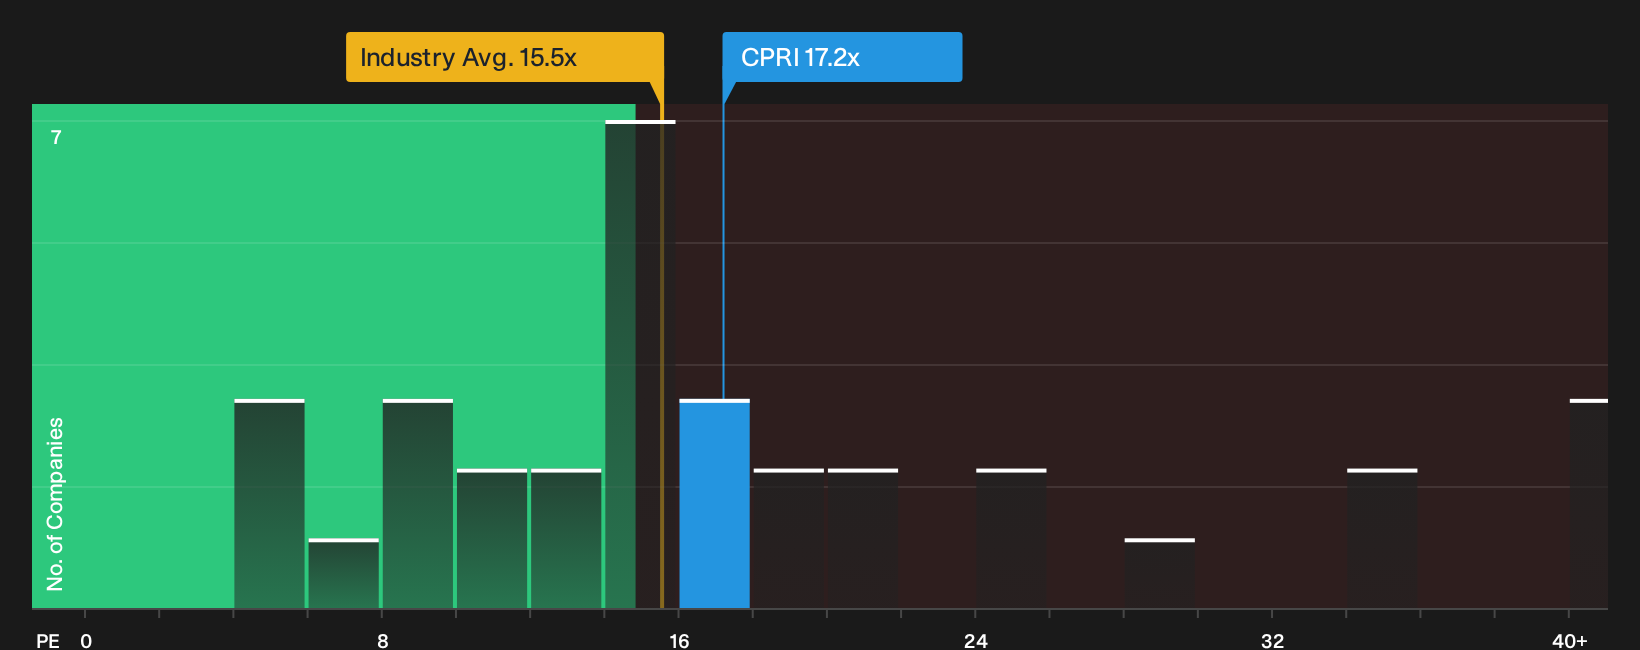
On the flip side of that $22.53 fair value narrative, Capri Holdings currently trades on a P/E of 17.2x versus 16.2x for peers and 15.3x for the wider US Luxury group. The fair ratio estimate sits at 22.2x. Is this a mispriced laggard or just a riskier equity story that deserves a cheaper tag?
See what the numbers say about this price gap and how it could close or widen in future by reviewing our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or a reset in progress: either way Capri Holdings now sits at a point where sentiment and numbers are pulling in different directions. Act quickly and stress test that gap yourself by weighing up the 3 key rewards and 2 important warning signs.
Looking for more Capri Holdings style investment ideas?
If Capri Holdings has you reassessing your watchlist, now is the moment to scan for fresh opportunities before the next wave of moves passes you by.
- Target reliable cash generators by running through a 6 dividend fortresses that focuses on income potential backed by meaningful payouts.
- Hunt for resilient balance sheets using a list of solid balance sheet and fundamentals (23 results) so you are not caught off guard when conditions turn tougher.
- Spot potential future leaders early through a 16 high quality undiscovered gems that filters for strong fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com