
Nova (NVMI) Starts A $200 Million Buyback But Is The Valuation Case Still Intact
Nova (NasdaqGS:NVMI) has put a fresh US$200 million share repurchase program on the table, funded with existing cash, after its board signed off on a new buyback plan on September 2, 2026.
At a share price of US$371.81, Nova has seen momentum cool in the short term, with the 30 day share price return down 9.65% and the 90 day share price return down 36.23%. However, the 1 year total shareholder return of 26.85% and 3 year total shareholder return of more than 3x still point to a strong longer term payoff for investors who stayed in through earlier swings and are now weighing the new buyback and recent joint venture news against that track record.
Scan the market for other hand picked chip equipment players with strong fundamentals and recent price pressure by checking the list of solid balance sheet and fundamentals (23 results) alongside Nova.
Novo's repurchase plan and recent slide in the share price point in different directions. The question now is whether the current valuation reflects business strength or just a reset in sentiment.
Most Popular Narrative: 30.1% Undervalued
Analysts following Nova see fair value at $532, well above the last close of $371.81, and frame that gap around earnings power and metrology demand.
The accelerating complexity of semiconductor devices, driven by AI, larger die sizes, advanced nodes, and heterogeneous packaging, continues to fuel demand for Nova's advanced metrology solutions across both logic/foundry and memory segments, which is poised to lift long-term revenue growth as global digitization trends expand.
Curious what kind of revenue curve and profit profile need to sit behind that valuation gap. The narrative leans on faster compounding, richer margins, and a premium multiple to tie Nova's current price to that $532 figure.
Result: Fair Value of $532 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Nova story can wobble if key advanced node customers cut or delay capex, or if newer tools like ELIPSON and METRION see slower adoption.
Find out about the key risks to this Nova narrative.
Another View On Nova’s Valuation
That 30.1% analyst discount is only one lens. Our DCF model paints a different picture, with Nova trading at $371.81 against an estimated future cash flow value of $146.67, which screens as expensive rather than cheap. So which lens should drive your own work on the stock?
Look into how the SWS DCF model arrives at its fair value.
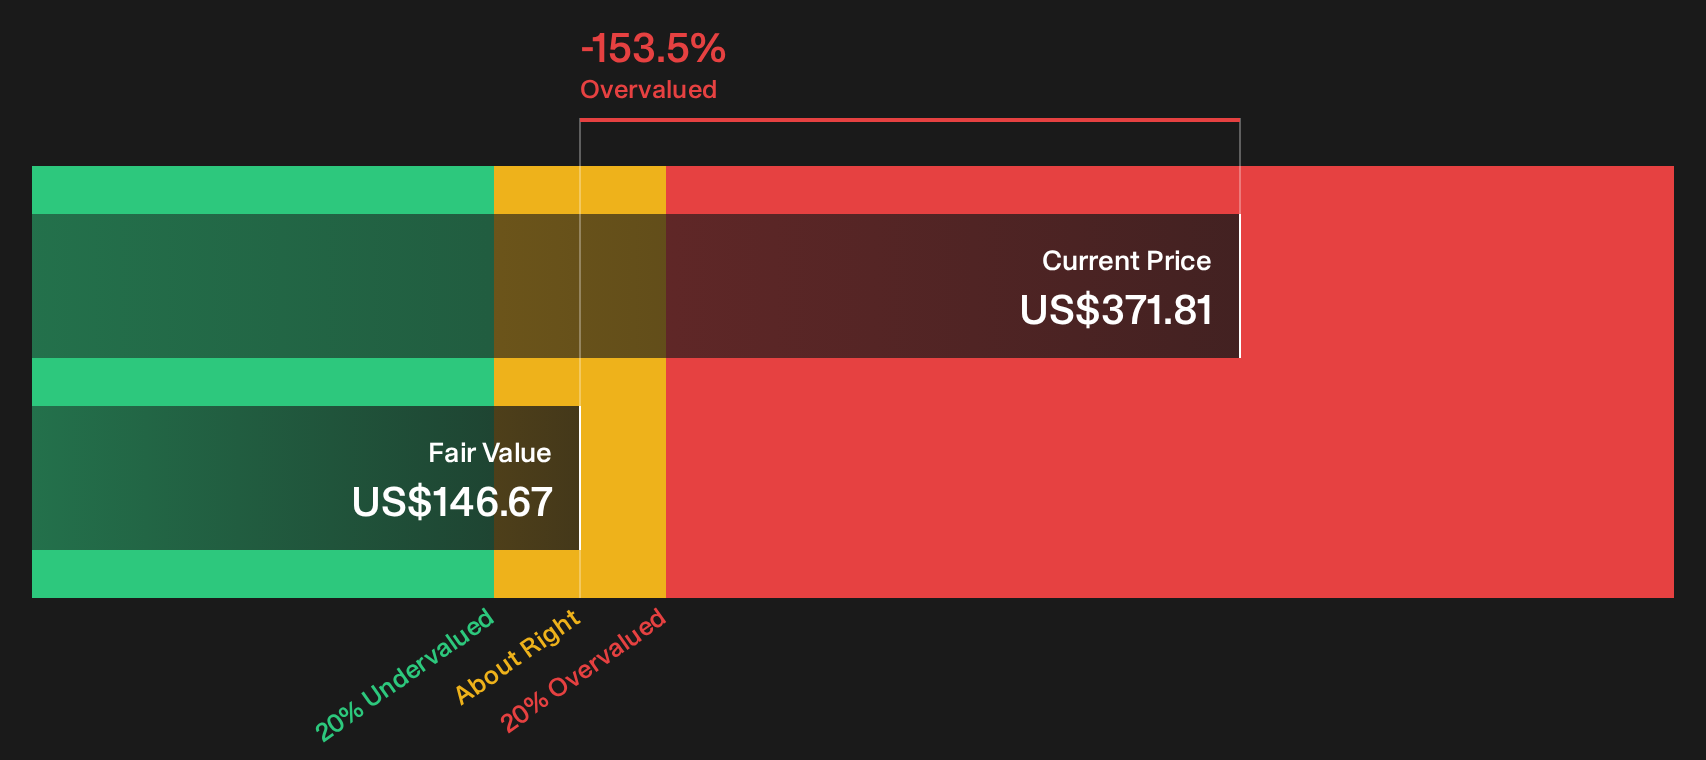
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nova for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Nova's outlook or simply a crossroads? Act while the data and sentiment are fresh and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nova?
If Nova has you thinking harder about valuation, do not stop there. Cast a wider net now so you are not relying on a single story.
- Target potential upside by scanning for companies that combine quality fundamentals with discounted valuations through the 32 high quality undervalued stocks.
- Strengthen your income stream by narrowing in on shares with robust payouts and higher yields using the 6 dividend fortresses.
- Protect your downside by focusing on resilience and financial durability with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com