
Inwit (BIT:INW) Stock Could Be 25% Undervalued On Tower Cash Flow
Infrastrutture Wireless Italiane has delivered a steep 31.9% share price decline over the past three years, while the latest valuation checks show a split picture, with the Discounted Cash Flow (DCF) estimate pointing to a discount and market multiples looking closer to fair.
- The roughly 31.9% fall over three years raises the question of whether the recent share price now embeds a more conservative view of the tower business.
- Future cash flow from Italy focused tower leases can support the current valuation, while any pressure on contract renewals or funding costs may weigh on what investors are willing to pay.
- The stock earns a mixed verdict on valuation checks, with the company scoring 4 out of 6, which points to neither a clear bargain nor an obvious overpricing.
For investors, the debate is whether the near 24.9% DCF discount in Infrastrutture Wireless Italiane is a genuine opportunity or simply compensation for the risks that have driven the share price down.
Pressure test whether Infrastrutture Wireless Italiane's mixed 4 out of 6 valuation score and 24.9% DCF discount reflect rare mispricing by comparing it with 185 high quality undervalued stocks.
Does Infrastrutture Wireless Italiane Look Undervalued on Cash Flow?
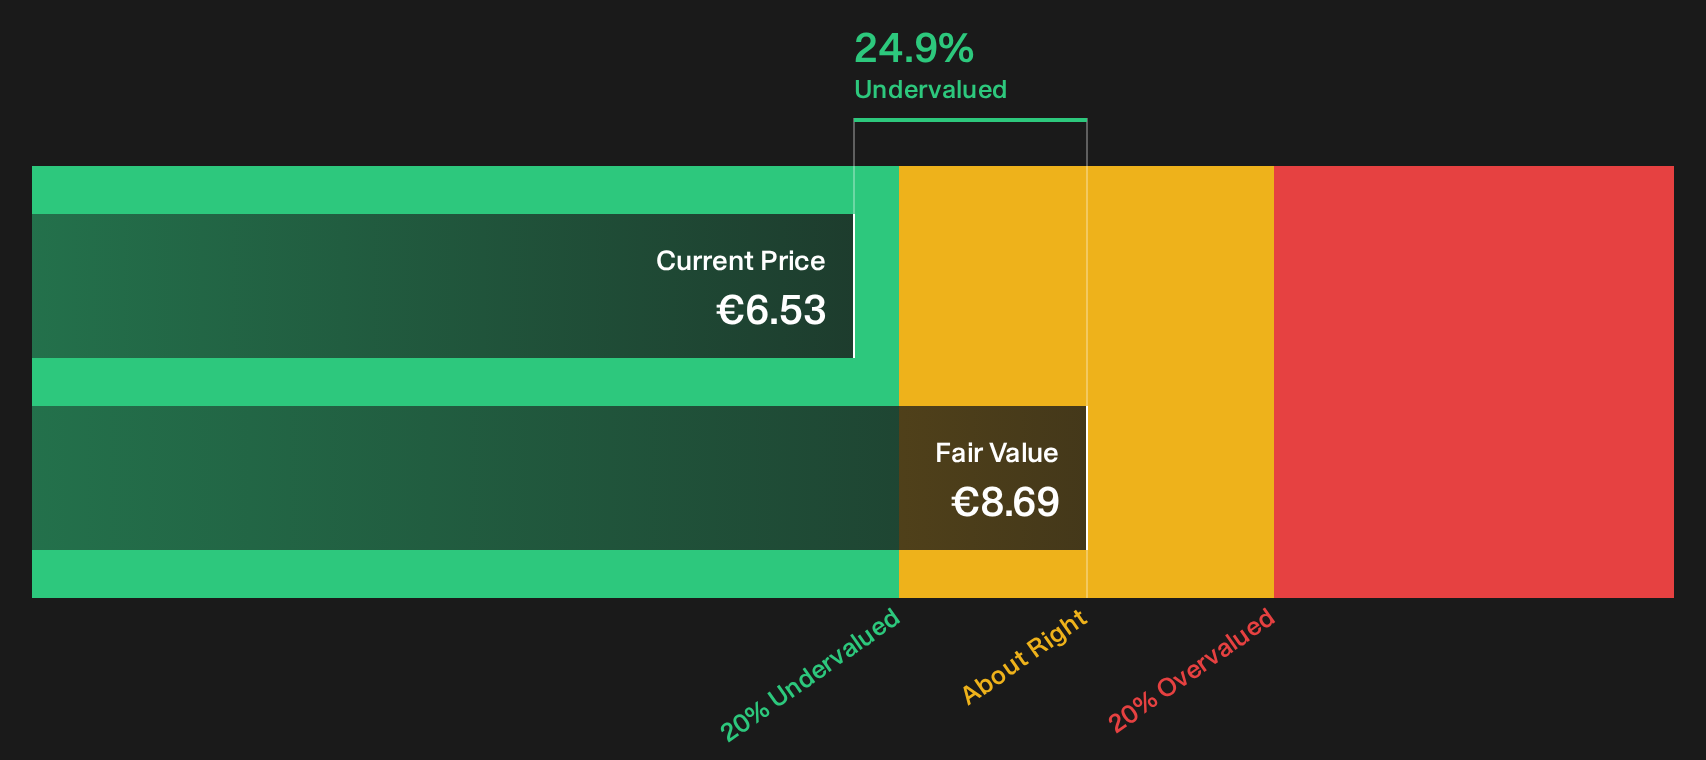
The Discounted Cash Flow (DCF) model used here estimates what Infrastrutture Wireless Italiane could return to shareholders based on its future free cash flows. The latest twelve month free cash flow is about €486.5 million, with the forecast path assuming growing cash generation rather than a sharp decline or a turnaround scenario.
On those projections, the model indicates an estimated intrinsic value of about €8.69 per share. This implies the stock trades at roughly a 24.9% discount to that cash flow based estimate. In practical terms, the market price currently values Infrastrutture Wireless Italiane below what this DCF suggests its tower cash flows may be worth, while still relying on relatively steady growth rather than aggressive expansion assumptions.
On this cash flow view, the stock appears undervalued relative to the DCF based intrinsic value estimate.
Our Discounted Cash Flow (DCF) analysis suggests Infrastrutture Wireless Italiane is undervalued by 24.9%. Track this in your watchlist or portfolio, or discover 185 more high quality undervalued stocks.
Is Infrastrutture Wireless Italiane Fairly Priced on Earnings?
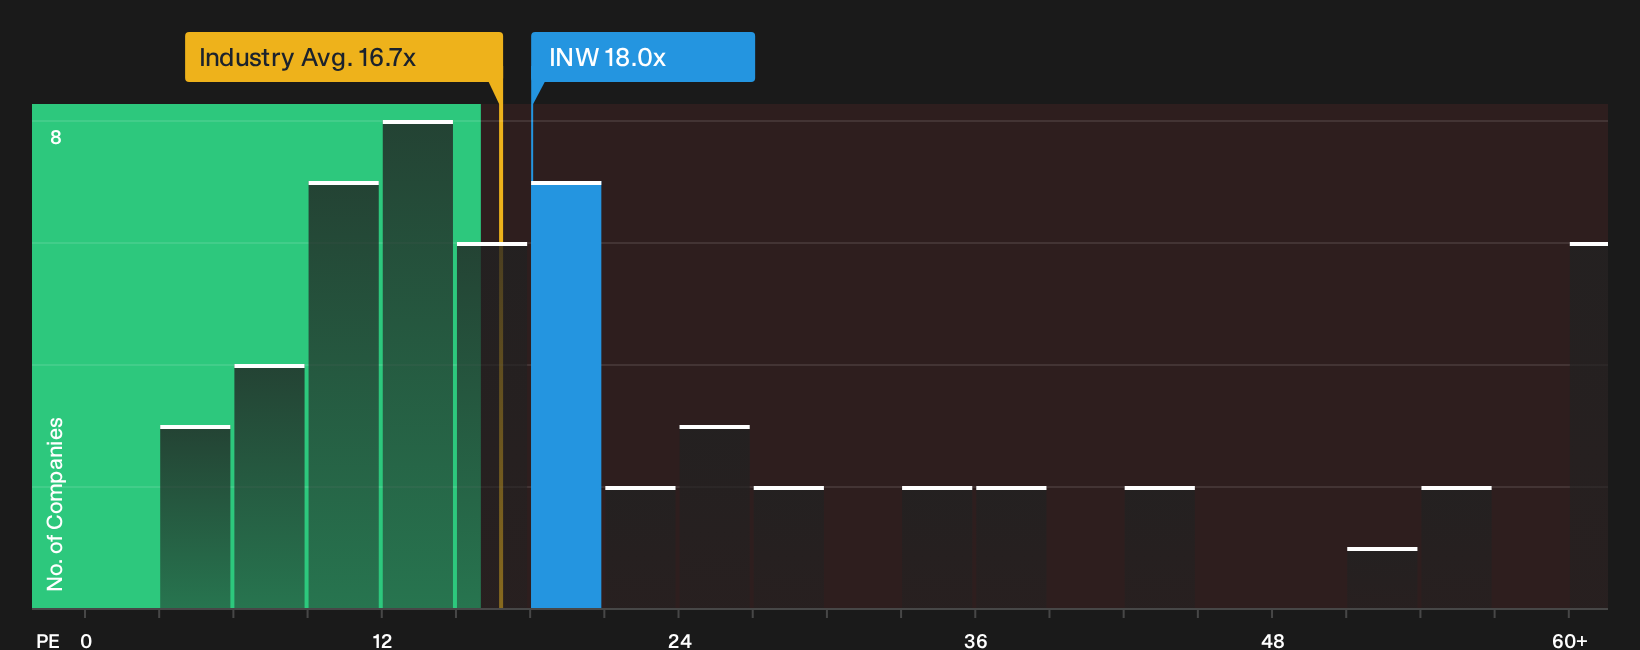
The P/E ratio lines up well for a tower operator like Infrastrutture Wireless Italiane because earnings are a direct read on how the leasing portfolio translates into profit. The stock currently trades on about 18.0x earnings, which sits above the wider telecom industry average of roughly 16.1x, yet below the peer group average near 24.8x. That puts the shares in the middle of the pack, neither the cheapest option in the sector nor the one investors are paying the highest premium for.
A more tailored benchmark, which blends factors such as the company’s margins, size and risk profile, points to a fair P/E ratio of about 18.6x. That is only slightly higher than where Infrastrutture Wireless Italiane trades today, so the gap between the market price and this model based reference looks small. On this earnings lens, the current share price broadly matches what the multiple based framework suggests is reasonable.
On P/E, Infrastrutture Wireless Italiane looks roughly fairly valued compared with both tailored and sector benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
The Infrastrutture Wireless Italiane Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Infrastrutture Wireless Italiane leaves off. They spell out what kind of future for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than today’s price. Each one treats fair value as a thesis about how the business evolves over time, so you can see how that idea holds up as new information arrives on the Community page.
Community views on Infrastrutture Wireless Italiane pull in opposite directions, with one camp leaning into tower demand and the other fixated on contract and funding strain.
Bull case: 17% undervalued
"The expansion of smart infrastructure (DAS and IoT solutions), with revenue up nearly 40% year-on-year and strong market potential for new locations by 2030, is expected to diversify income streams and drive higher-margin earnings while making INWIT a critical enabler of next-generation digital services…"
Read the full Bull Case to see why Infrastrutture Wireless Italiane could be undervalued
Bear case: roughly fairly valued
"Although data traffic growth, 5G rollout in suburban areas and coverage gaps on roughly 9,000 kilometers of roads and railways point to a structural need for more towers, the postponement of outdoor densification projects by budget constrained operators can keep non committed revenues soft and limit upside to overall revenue growth and earnings…"
Read the full Bear Case to see why Infrastrutture Wireless Italiane could be overvalued
Do you think there's more to the story for Infrastrutture Wireless Italiane? Head over to our Community to see what others are saying!
The Bottom Line
Infrastrutture Wireless Italiane screens as undervalued on a Discounted Cash Flow (DCF) basis, yet the market multiple work indicates that the current P/E is roughly in line with peers and tailored benchmarks. That mix suggests a setup in which the potential upside depends on how reliably future tower cash flows materialise relative to today’s pricing. The key issue for investors is whether funding costs and contract renewal risk remain contained enough for that cash generation narrative to hold, or whether the present discount reflects the market correctly pricing in those pressures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com