
Gilead (GILD) Stock Still Looks Cheap Despite New Research Center
Gilead Sciences has quietly turned in a strong run over the past five years, yet the shares still screen as undervalued on broader checks. This puts the current price under scrutiny rather than celebration. After a recent pullback, the question for you is whether the market is fairly discounting the drug pipeline and research spend, or leaving more on the table than the recent rally suggests.
- Gilead Sciences has returned about 138.5% over the past five years, which puts long term holders in a solid position while forcing new buyers to think carefully about what is already reflected in the price.
- The new Foster City research center and focus on oncology and HIV treatments can support long run earnings power. However, execution risk around complex therapies and shifting deal activity in cell therapy may limit how much value investors are willing to assign to that pipeline today.
- The broader checks lean cheap, with a value score of 5 suggesting the stock still looks relatively inexpensive versus its fundamentals.
The issue now is whether Gilead Sciences’ current valuation fairly reflects its research investment and therapy portfolio, or whether the recent performance leaves a gap between price and underlying worth.
Capitalize on the same mix of research firepower and perceived undervaluation driving interest in Gilead Sciences by scanning our handpicked 31 high quality undervalued stocks, which is built on strong cash flows and solid balance sheets.Is Gilead Sciences Still Cheap on Sales?
For a research heavy group like Gilead Sciences, investors often lean on the P/S ratio because revenue tends to be more stable than earnings through product cycles and R&D swings.
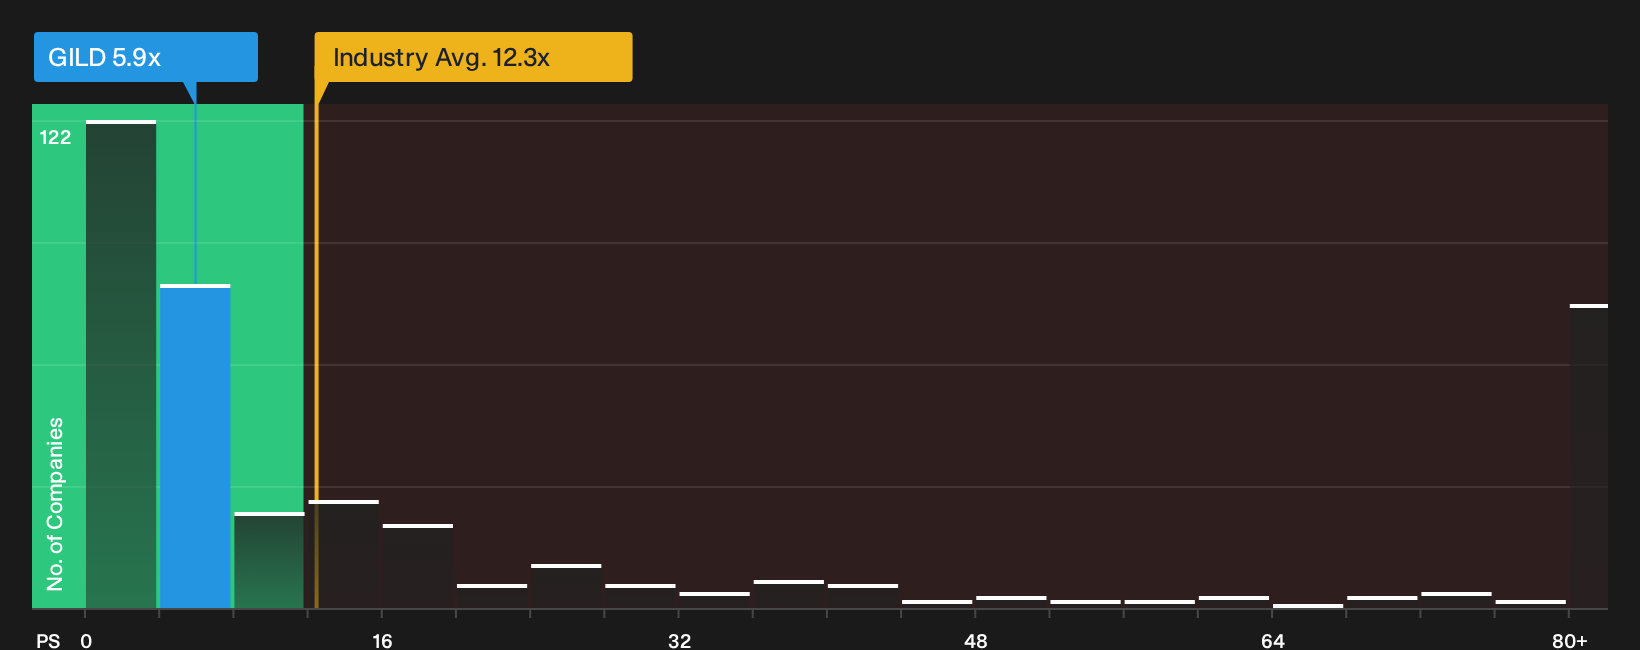
The stock trades on a P/S of 5.9x, which sits below the broader biotech industry average of 12.3x and also under the peer group at 7.0x. A more tailored fair P/S ratio that blends Gilead Sciences’ margins, risk profile and scale comes out at 10.8x, well above where the equity currently changes hands.
Despite the recent headlines around the new Foster City research center and ongoing oncology ambitions, the current P/S still implies a discount relative to both benchmarks and the modelled fair level. That gap suggests the market is cautious about fully crediting the existing portfolio and pipeline revenue stream.
On a pure P/S basis, Gilead Sciences stock appears undervalued relative to both sector norms and the fair multiple indicated by its own fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
The Gilead Sciences Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Gilead Sciences and turn it into concrete what ifs about future growth, margins and earnings that would need to hold for the shares to be worth materially more or less than they trade for today, and they sit on the platform's Community page. Each narrative treats fair value as a specific thesis about Gilead Sciences' business that you can watch over time rather than a one off snapshot.
Community views on Gilead Sciences could hardly be further apart, with one side leaning into the pipeline rebuild and the other zeroing in on execution risk.
Bull case: 9% undervalued
"An expanded pipeline in oncology, cell therapy, and next-generation HIV regimens set Gilead up for multiple new product launches by 2030, pointing to a prolonged innovation cycle likely to increase recurring revenue and insulate long-term earnings from generic erosion..."
Read the full Bull Case to see why Gilead Sciences could be undervalued
Bear case: 12% overvalued
"Bear case: Execution risk (M&A integration, oncology competition, pricing pressure) and near-term EPS dilution..."
Read the full Bear Case to see why Gilead Sciences could be overvalued
Do you think there's more to the story for Gilead Sciences? Head over to our Community to see what others are saying!
The Bottom Line
Gilead Sciences still screens as undervalued on market multiples, with its P/S ratio suggesting investors are reluctant to fully credit the current therapies and pipeline. That discount only helps if research spending in areas like oncology and HIV converts into durable revenue rather than lingering execution risk. For you, the key question is whether the gap between Gilead Sciences’ trading multiple and its implied fair range reflects caution that will fade, or a persistent value trap tied to complex therapies, deal risk and competitive pressure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com