
Is QUALCOMM (QCOM) Cheap As Its Amazon AI Deal Fuels Data Center Hopes?
QUALCOMM (QCOM) is back in the spotlight after announcing a multi generation collaboration with Amazon to build custom AI inference chips and high speed optical links for large scale data centers.
QUALCOMM’s tie up with Amazon lands at a moment when momentum in the shares is rebuilding, with a 1 day share price return of 2.88% and a 7 day share price return of 7.84% helping to lift the year to date share price return to 5.20% despite a 90 day share price pullback of 17.59%. Recent headlines have ranged from Qualcomm’s long term AI chip purchase framework with Amazon, to record automotive revenue contributions, to reports of pricing friction around potential 2nm manufacturing with Samsung, all feeding into how investors weigh future growth avenues against execution risk. Over a longer horizon, the picture looks different, with a 1 year total shareholder return of 14.79% and a 3 year total shareholder return of 71.38%, which shows that long term holders have seen stronger gains than the recent 30 day share price return of 9.76% alone might suggest.
Scan how QUALCOMM’s AI push with Amazon compares with other chipmakers riding the same trend by reviewing our hand picked 89 AI infrastructure stocks today.
QUALCOMM now trades close to analyst targets after a sharp rebound, yet its intrinsic value estimate sits at a small premium. Is the recent AI excitement masking risks that justify the remaining discount?
Most Popular Narrative: 7.3% Undervalued
QUALCOMM’s most followed narrative points to a fair value of $196.27 against a last close of $181.97, which implies modest undervaluation rather than a deep bargain.
Rapid growth in automotive and industrial IoT segments, supported by strong design win momentum and a robust multi-year pipeline (with a combined $22 billion revenue target by 2029), is set to diversify Qualcomm's revenue base and drive margin-accretive growth as these businesses become a larger share of total earnings.
Want to see what is doing the heavy lifting in that valuation gap? The narrative leans on a specific mix of revenue growth, margin resets and a future earnings multiple that together paint a very different picture from the recent handset drag.
Result: Fair Value of $196.27 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, execution risk around early stage AI and data center plans, along with ongoing legal and regulatory scrutiny of Qualcomm's licensing model, could upset that thesis.
Find out about the key risks to this QUALCOMM narrative.
Another View: QUALCOMM And The DCF Pushback
The main fair value story on QUALCOMM leans on earnings and multiples, yet the SWS DCF model points in a different direction. On that cash flow view, QCOM at $181.97 sits above an estimated value of $172.65, so screens as overvalued. Which lens do you give more weight to when the signals conflict like this?
Look into how the SWS DCF model arrives at its fair value.
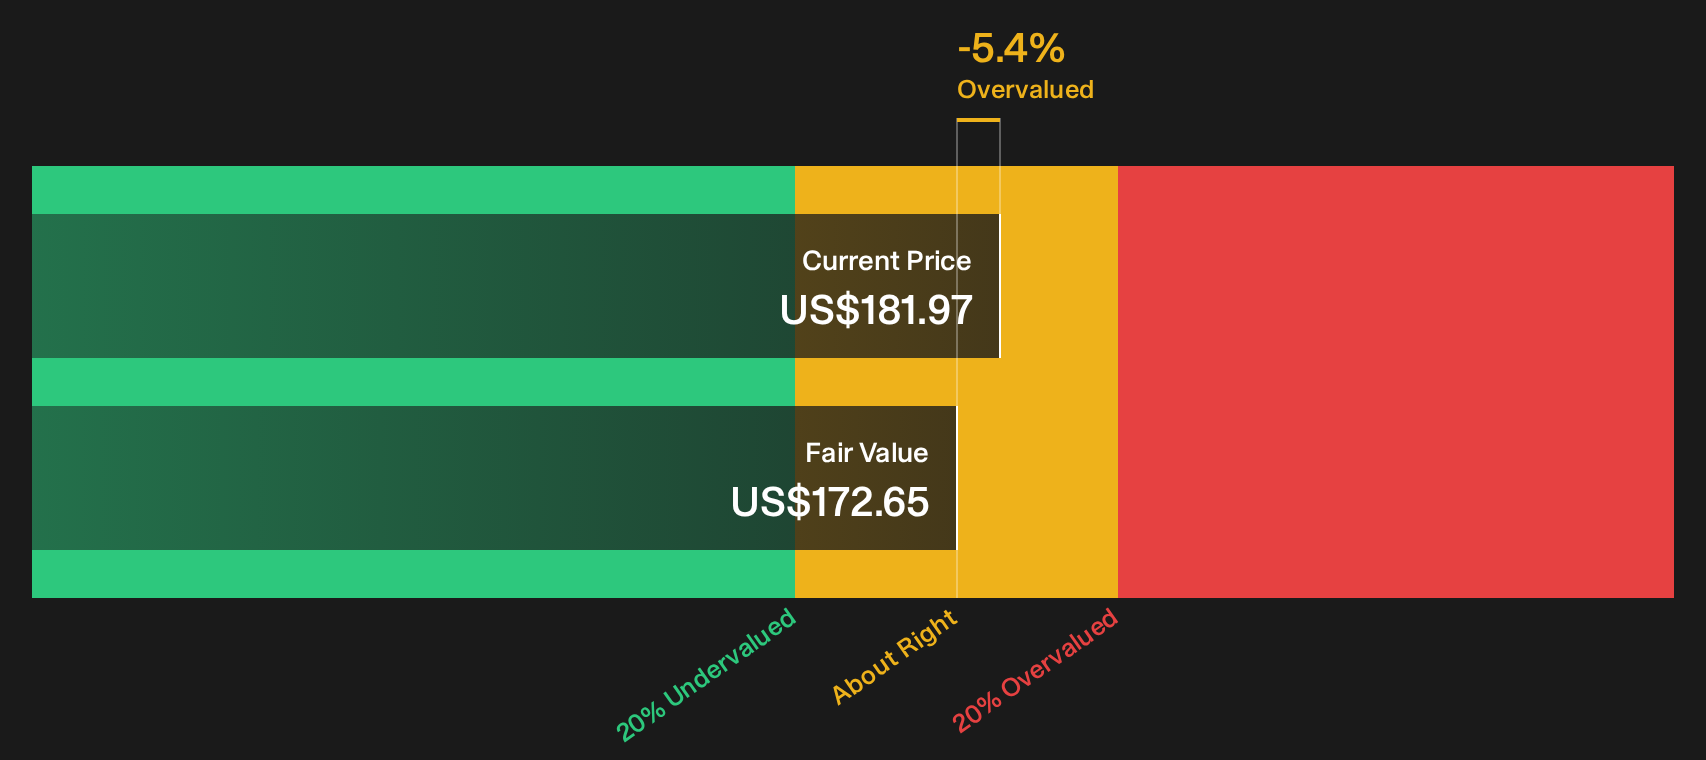
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out QUALCOMM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on QUALCOMM so far. If you want to move fast and build your own stance on the stock's balance of promise and concern, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more QUALCOMM sized ideas?
If QUALCOMM has sharpened your appetite for opportunities, widen your field of view with a few focused screens that surface very different types of candidates.
- Target reliable compounding by zeroing in on companies screened as 6 dividend fortresses for investors who care about income as much as price moves.
- Hunt for mispriced quality through the 15 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Dial down potential volatility by filtering for 11 resilient stocks with low risk scores so you are not scrambling after every headline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com