
Can CF Industries Holdings (CF) Stay Cheap After A 201% Run?
CF Industries Holdings has delivered a powerful 5 year run for shareholders, yet the current valuation checks still suggest the stock trades below a conservative estimate of its intrinsic value. The Discounted Cash Flow (DCF) estimate points to a meaningful gap to fair value, and the market multiple work tells a similar story.
- The share price has returned 201.0% over 5 years, which puts recent enthusiasm firmly on the side of long term holders rather than new entrants.
- Future cash generation from its nitrogen fertilizer operations can support the intrinsic value case, while exposure to cyclical agricultural and energy markets may cap how much investors are willing to pay for those cash flows at any one time.
- The broader checks lean cheap, with CF Industries Holdings scoring a high value rating of 5 out of 6 on key valuation measures.
The issue now is whether CF Industries Holdings still offers a clear valuation edge after such a strong multi year share price performance.
Compare CF Industries Holdings' valuation gap to a curated list of other stocks that screen as inexpensive based on cash flows and balance sheet strength with the 31 high quality undervalued stocks.
Does CF Industries Holdings Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model used here values CF Industries Holdings by projecting future free cash generation and discounting it back to today. On the numbers, the latest twelve-month free cash flow sits at about $2.1b, with the forecast path assuming cash flows ease back from that level rather than climb aggressively over time.
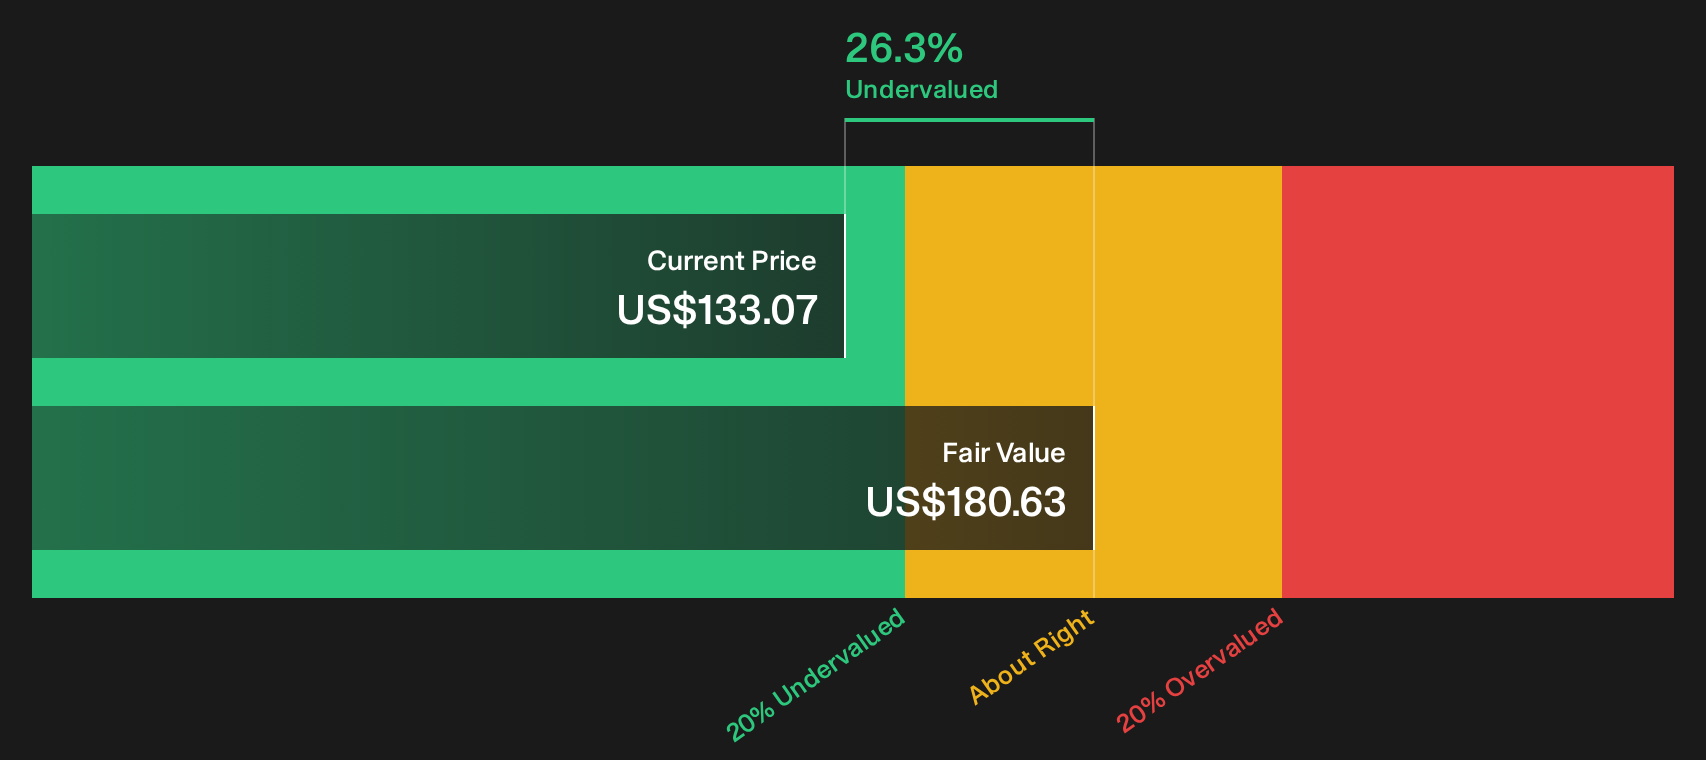
Applying these projections within a 2 Stage Free Cash Flow to Equity framework gives an estimated intrinsic value of about $180.63 per share in dollar terms. Compared with the current share price, this suggests a 26.3% discount, indicating that the market is pricing CF Industries Holdings as if its future cash streams will be worth less than the model suggests, even with temperate long-term assumptions built in.
On this DCF view, CF Industries Holdings appears undervalued relative to the cash flows it is currently expected to produce.
Our Discounted Cash Flow (DCF) analysis suggests CF Industries Holdings is undervalued by 26.3%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is CF Industries Holdings Still Cheap on Earnings?
P/E fits CF Industries Holdings quite well because earnings remain a central reference point for how investors frame this nitrogen fertilizer producer.
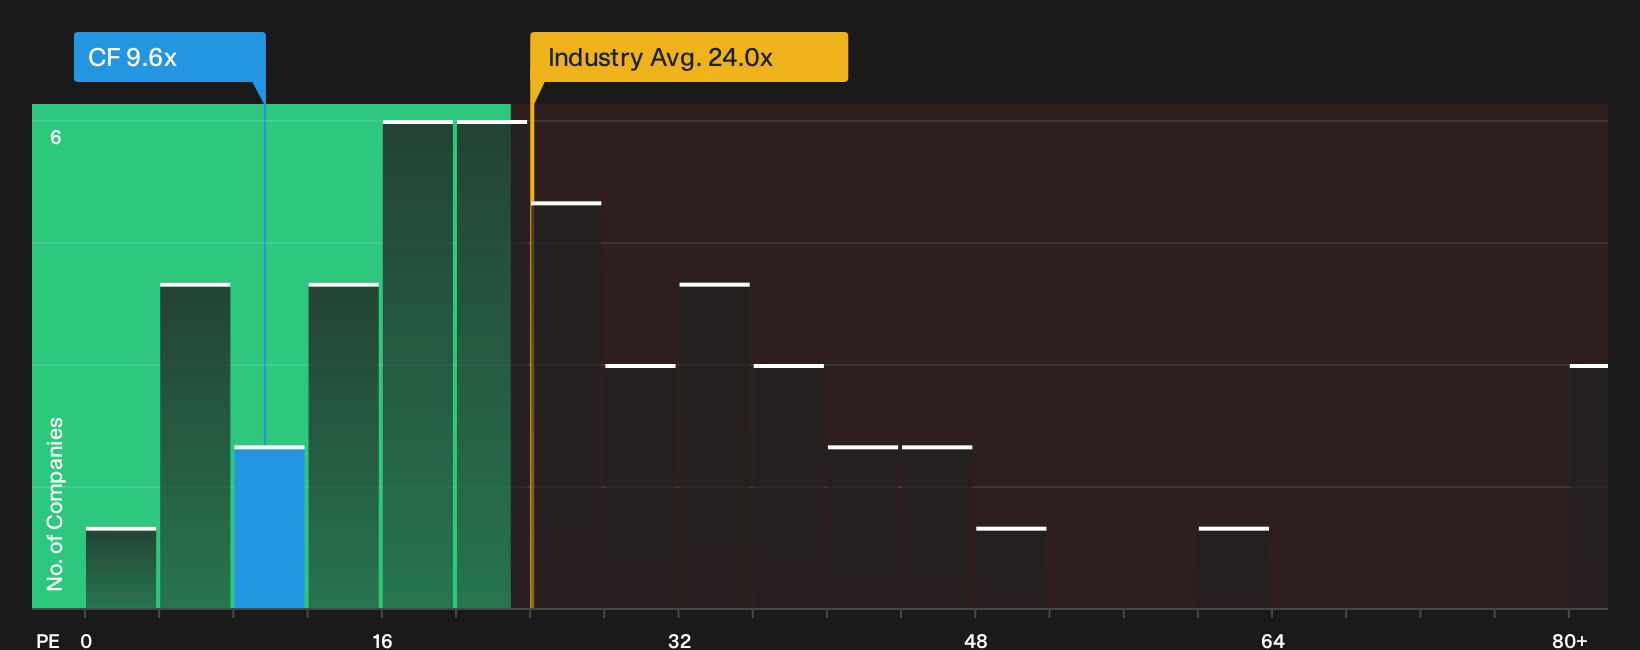
On current numbers, CF Industries Holdings trades on a P/E of about 9.6x. That sits well below the Chemicals sector average of roughly 24.0x and also below a broader peer group average of about 26.4x. The Fair Ratio, which blends factors like profitability profile, size and risk into a more tailored benchmark, sits higher at around 13.8x. That is a meaningful gap between where the stock changes hands and where this framework suggests a more typical multiple might land.
The spread between the 9.6x market price and the 13.8x Fair Ratio suggests that investors are assigning a relatively cautious earnings multiple to CF Industries Holdings despite the current profit base.
On this P/E yardstick, CF Industries Holdings stock appears undervalued relative to the earnings profile implied by the Fair Ratio.
See what the numbers say about this price — find out in our valuation breakdown.
The CF Industries Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CF Industries Holdings pick up where the valuation work leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties a fair value to a clear storyline about CF Industries Holdings' potential catalysts and key pressures so you can track over time which version of events appears to be unfolding.
Community views on CF Industries Holdings are split, with one camp leaning into low carbon ammonia and capital returns while the other worries that nitrogen strength is already in the price.
Bull case: 21% undervalued
"Progress at the Blue Point low carbon ammonia joint venture, including positive FID, offtake secured by partners and contract for difference support from the Japanese government, positions CF Industries to access new energy related ammonia demand and potential premium pricing…"
Read the full Bull Case to see why CF Industries Holdings could be undervalued
Bear case: 33% overvalued
"Management highlights tight global nitrogen supply and delayed capacity as a support for pricing. If new capacity in regions such as North America or Brazil reaches full rates faster than expected, or idled plants return, pricing for globally traded ammonia and urea could normalize and compress EBITDA and earnings from current levels…"
Read the full Bear Case to see why CF Industries Holdings could be overvalued
Do you think there's more to the story for CF Industries Holdings? Head over to our Community to see what others are saying!
The Bottom Line
For CF Industries Holdings, both the Discounted Cash Flow (DCF) work and the earnings multiples still lean the same way, with each pointing to an undervalued profile rather than a fully priced one. The intrinsic value estimate implies the market is treating future cash flows cautiously, while the P/E gap to the Fair Ratio suggests a similar discount on the earnings side.
The key issue from here is whether nitrogen fertilizer profitability and new ammonia demand can support those cash flows without a sharp reset. If that holds, the current discount could reflect investor caution more than a clear value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com