
L3Harris (LHX) Stock Looks Reasonable Following Its 51% 3 Year Run
L3Harris Technologies has slid sharply over the past month, yet the valuation checks still suggest the stock trades at a discount to what its cash flows may be worth on a reasonable intrinsic value estimate. The Discounted Cash Flow (DCF) workup and market multiple checks both lean toward the shares being undervalued even after the recent pullback.
- L3Harris Technologies is up 50.6% over the past 3 years, which means today's weaker share price comes after a solid multi year gain.
- A multi year, US$4.7b propulsion contract for the PAC 3 MSE program can support long run cash generation, while the securities investigation tied to the former CEO's resignation may weigh on investor confidence and valuation multiples.
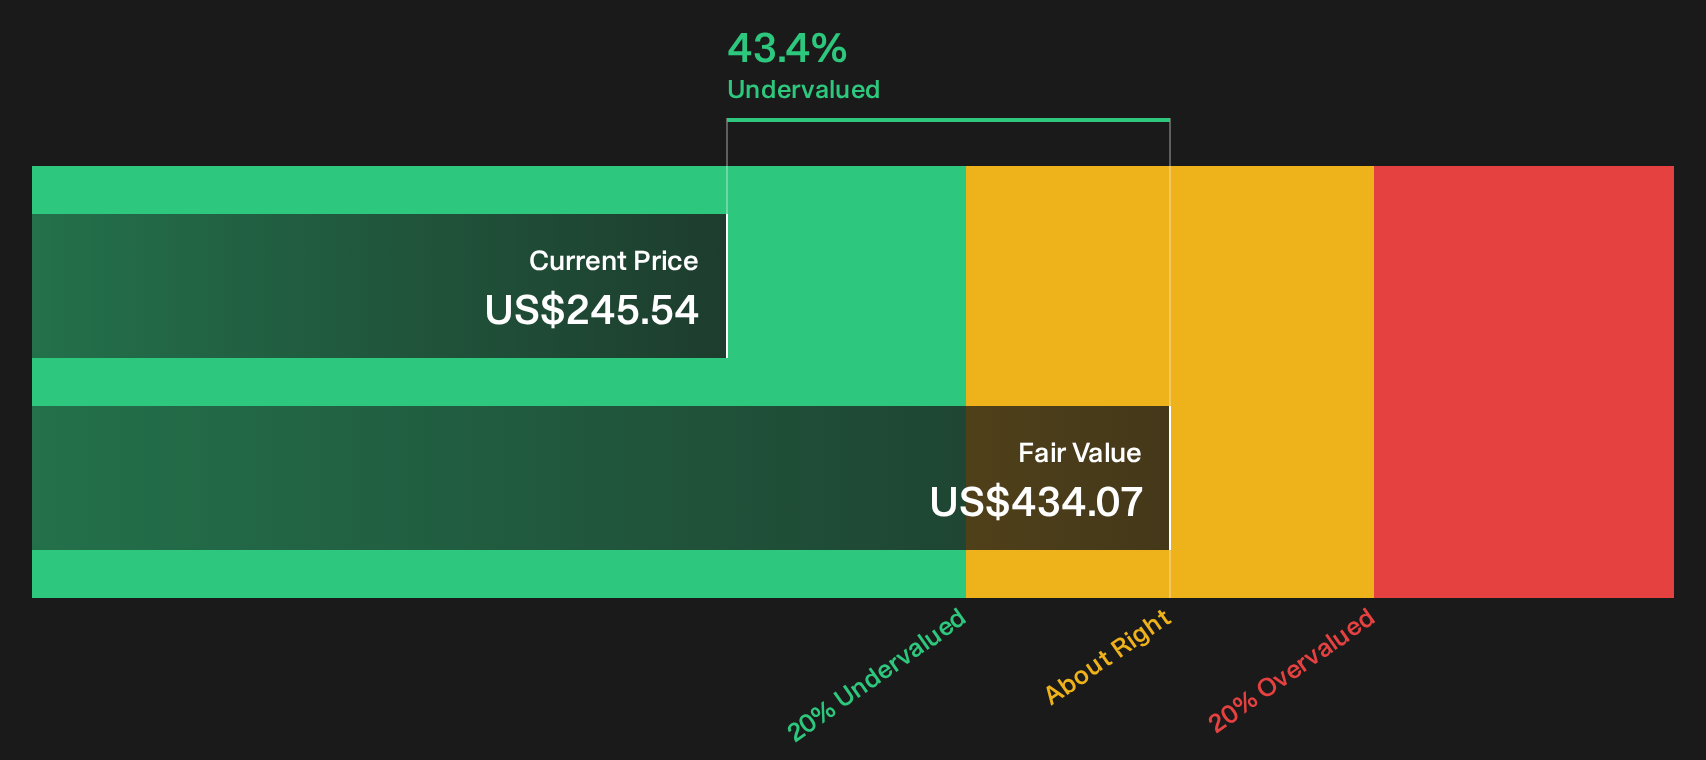
- The broader checks lean cheap, with the company screening as undervalued in 6 of 6 valuation tests, and the Discounted Cash Flow (DCF) estimate sitting about 43.4% above the current share price.
For investors, the debate is whether L3Harris Technologies' recent share price weakness already reflects these governance and execution risks or if the apparent discount to intrinsic value still overstates the downside.
Capitalize on the recent pullback in L3Harris Technologies by lining it up against 31 high quality undervalued stocks that also screen as potentially mispriced on cash flows and fundamentals.Does L3Harris Technologies Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around the cash the business can return to shareholders rather than accounting earnings. For L3Harris Technologies, the latest twelve month free cash flow sits at about $2.8b, with the model assuming growing cash generation over time rather than a sharp step change. Feeding those projections into the 2 Stage Free Cash Flow to Equity framework gives an estimated intrinsic value of roughly $434 per share, which is described as about 43.4% above the current market price.
The large, multi year US$4.7b PAC 3 MSE propulsion contract helps explain why the cash flow outlook in the DCF is relatively robust, even as the securities investigation over the former CEO keeps a lid on sentiment. Because the market price still sits well below the modelled value, the gap points to investors pricing in a meaningful governance and execution discount to L3Harris Technologies that the cash flow workup does not fully reflect.
On this Discounted Cash Flow view, L3Harris Technologies screens as undervalued relative to the cash it is expected to generate.
Our Discounted Cash Flow (DCF) analysis suggests L3Harris Technologies is undervalued by 43.4%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Does L3Harris Technologies Look Undervalued on Earnings?
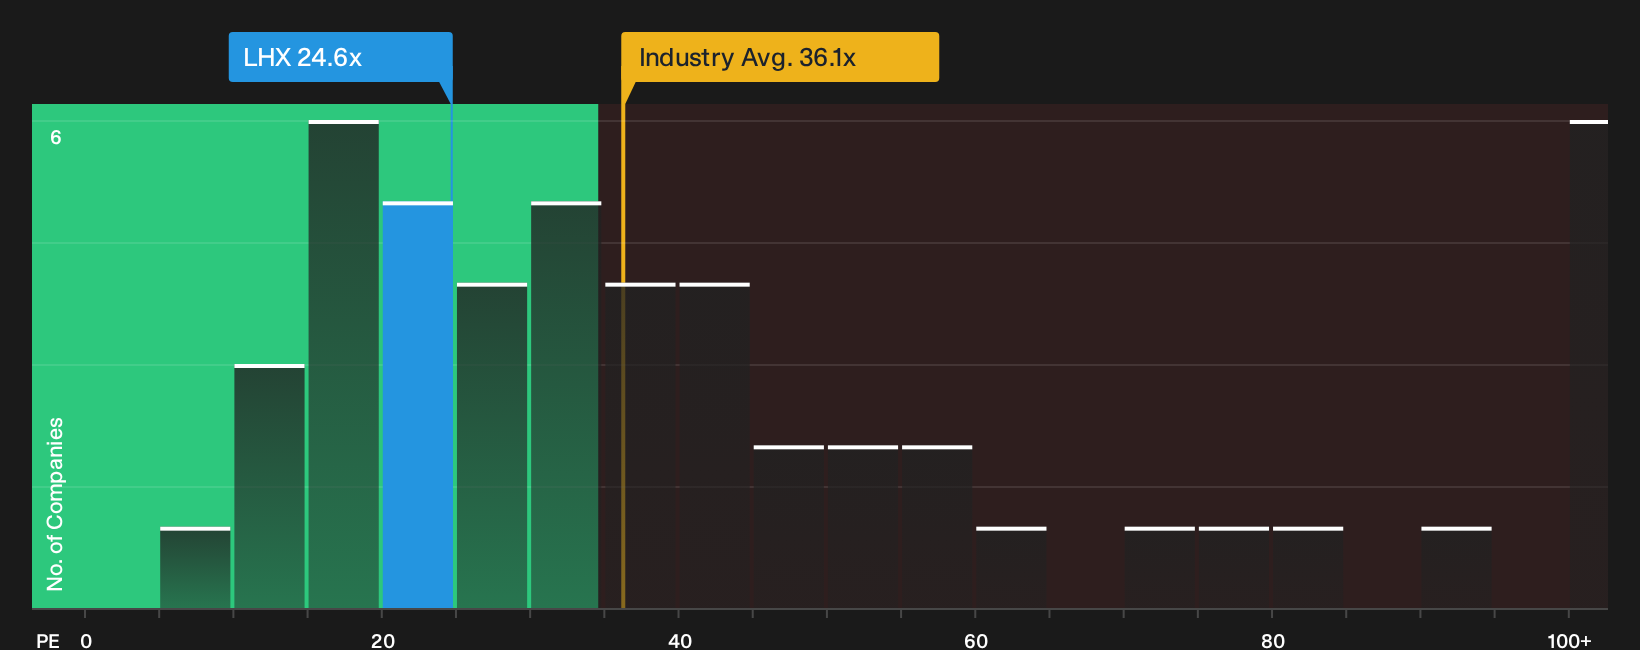
The P/E ratio works well for L3Harris Technologies because earnings power is a core focus for most defense contractors. On this measure, the stock trades on about 24.6x earnings, compared with roughly 31.8x for close peers and 36.1x for the wider Aerospace & Defense group. That is a clear discount to the going rate for similar businesses.
The modelled fair P/E for L3Harris Technologies is about 28.7x, which reflects what investors might typically pay given its sector, profitability profile and risk mix. The current 24.6x level sits meaningfully below that fair ratio. As a result, the market is valuing each dollar of earnings more conservatively than the framework suggests.
On the P/E multiple, L3Harris Technologies stock appears undervalued relative to both its tailored fair ratio and sector benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
The L3Harris Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for L3Harris Technologies give you a clearer link between the valuation puzzle above and the assumptions that would need to hold for L3Harris Technologies' share price to be materially higher or lower than it is today, based on different paths for growth, margins and earnings. Each scenario ties a fair value to a particular storyline about future catalysts and risks so you can track which version of events appears to be unfolding over time on the Community page.
One of the top community narratives on L3Harris Technologies: 28% undervalued
"LHX NeXt and strategic partnerships in AI and communications likely to improve efficiency and expand market reach, driving margin and earnings growth..."
Read one of the top narratives on L3Harris Technologies
Do you think there's more to the story for L3Harris Technologies? Head over to our Community to see what others are saying!
The Bottom Line
L3Harris Technologies screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and the P/E multiple checks, which point in the same direction rather than sending mixed messages. The crux is whether current governance and execution concerns keep a lid on the valuation multiple or fade as contracts like the PAC 3 MSE program play through cash flows. For investors, the key judgment is whether that discount reflects mispricing or is a fair cushion for the legal and leadership risks that are still being worked through.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com