
Kroger (KR) Stock Climbs On Profit Resilience As Sales Momentum Slows
Kroger stock came into this print a little bruised, with the 90 day return down about 8.7%, yet the shares popped 2.7% to $58.49 once investors saw the latest figures. The market reacted to one thing above all else: profit resilience.
Adjusted earnings per share landed at about $1.09 for Q2, with adjusted First In First Out operating profit around $1.1b, even as identical sales without fuel barely moved. For a grocer locked in a price fight for value focused shoppers, holding that kind of profit line is the real headline today.
Love Kroger's profit resilience but worried that sluggish identical sales without fuel could cap the upside? Take a look at the list of solid balance sheet and fundamentals stocks (23 results) for ideas that pair steady earnings power with stronger underlying growth drivers.
Q2 2027 Earnings Summary
- Total Revenue (Q2 2027 vs. Q2 2026): US$34,621m vs. US$33,940m (approximately 2.0% higher)
- Net Income Excl. Extra Items (Q2 2027 vs. Q2 2026): US$641m vs. US$612m (up about 4.7%)
- Basic EPS (Q2 2027 vs. Q2 2026): US$1.06 vs. US$0.92 (increased roughly 14.4%)
- Trailing 12 Month Net Profit Margin (Q2 2027 vs. Q2 2026): 0.7% vs. 1.8% (compressed by 1.1 percentage points)
If you prefer clean charts over another wall of earnings tables and footnotes, explore Kroger's full financial picture, including a clear view of its valuation in the company report for Kroger.
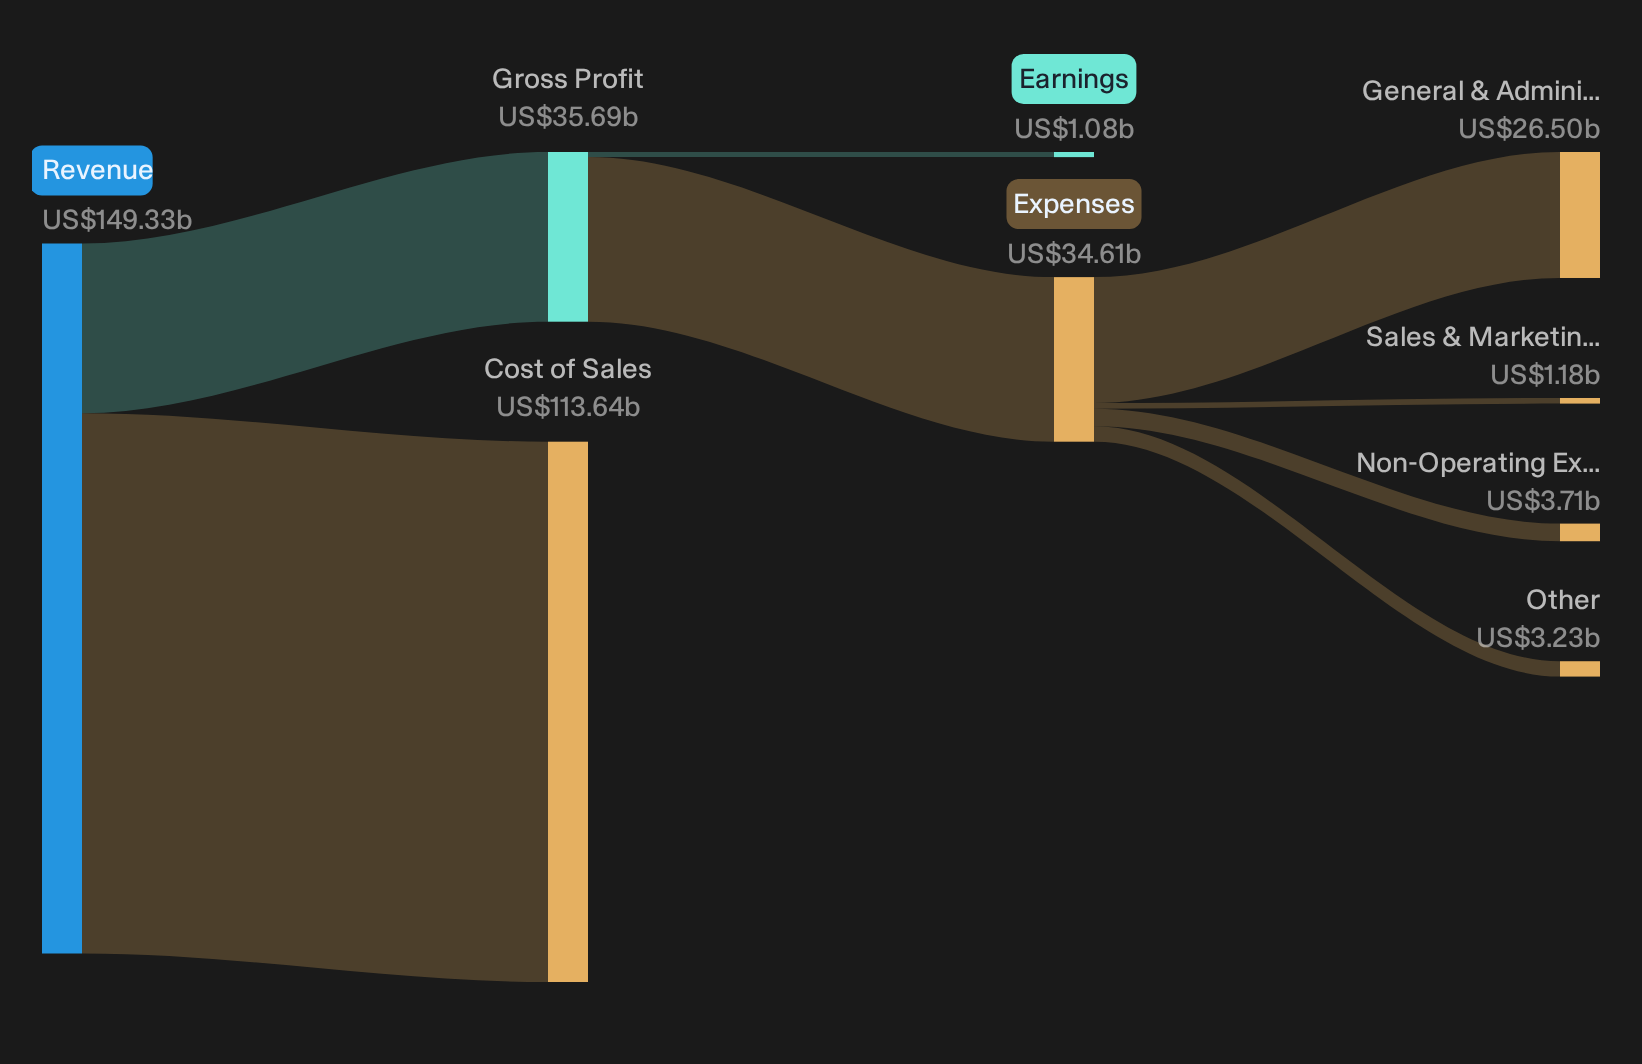
Kroger bull story leans on profit mix
Bulls argue Kroger is quietly turning a low growth grocer into a higher quality profit engine built on e commerce, retail media and private label, with cost savings funding the shift. Q2 lines up with that script in several ways. Adjusted EPS rose to about US$1.09 while identical sales without fuel ticked only 0.2%, so earnings resilience clearly came from mix and efficiency rather than volume. Online revenue advanced roughly 20% and stayed profitable for a second quarter, a key milestone for the turnaround narrative. Retail media grew about 24% with monetization up 88 bps, which supports the idea that Kroger Precision Marketing is becoming a meaningful earnings layer. Private label penetration increased about 50 bps and Smart Way expanded, matching the value focused playbook. The maintained full year EPS and operating profit outlook, despite softer comp guidance, also backs the claim that the cost program is doing real work.
Bear worries on comps and quality are not gone
Skeptics worry that Kroger is leaning too hard on cost levers and non core profit pools while the underlying grocery engine slows, and that recent execution gaps could weigh on trust. This quarter gives that concern some traction. Management cut full year identical sales without fuel guidance to 0.2% to 0.8% after a 0.2% print, even after backing out roughly 265 bps of headwinds from Cyclospora, pharmacy pricing and egg deflation. That hints at softer demand than the model originally assumed. Net profit margin over the trailing 12 months compressed from 1.8% to 0.7%, which reinforces the idea that reinvestment and mix shifts carry a cost. Recent headlines on pricing accuracy and a proposed pharmacy settlement sit awkwardly beside the heavy value messaging. The market reaction, a 2.7% move up but a 90 day return still down about 8.7% suggests those longer term worries have not fully cleared.
After profit margins compress from 1.8% to 0.7% and insider selling picks up, it helps to review an independent red flag audit. Scan the risk analysis for Kroger which shows 4 important warning signsStay Ahead With Simply Wall St
If Kroger's profit resilience with softer identical sales has your attention, register for free with Simply Wall St and add it to a Watchlist so you can track the share price against fair value and watch for a better entry point. When you do decide to buy or adjust a position, manage everything through the Portfolio Command Center so you only see clear, focused alerts on the developments that matter. For longer term context on Kroger and peers, turn to the Community to see how other investors are interpreting the same data and risks. That combination helps you surface hidden catalysts or trouble signs early and stay a step ahead of the wider market.
Seeking Alternatives Beyond Kroger?
Fresh ideas move first, and prices often follow once the crowd catches on. Scan curated stock shortlists before the next breakout momentum phase gets fully priced in, act now.
- Spot resilient cash generators early and review a curated list of solid balance sheet and fundamentals stocks (23 results) while balance sheets are still strong and valuations have not fully caught up.
- Track fast moving niche trends and scan the hand picked 15 high quality undiscovered gems while these stories are still flying under the radar for now.
- Target income opportunities with staying power and work through the focused 6 dividend fortresses before yields drop and the market crowds into the same names.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com