
Is AI Networking Rollout Altering The Investment Case For Extreme Networks (EXTR)?
- Extreme Networks reported that Extreme Agent ONE Coworker, its agentic AI for enterprise networking, is now generally available worldwide to all Extreme Platform ONE subscribers, delivering recommendations, troubleshooting support, and context-aware insights across user, device, application, and network data.
- The new “Nudge” capability, which continuously scans historical baselines and live traffic to surface high-confidence network issues, is designed to reduce operating costs by cutting manual investigation time and helping IT teams shift from firefighting to planned maintenance.
- We will assess how Extreme Networks' investment narrative evolves as the Agent ONE Coworker AI, including its Nudge capability, reaches customers.
Scan beyond Extreme Networks and line up other AI infrastructure plays by checking our curated list of 89 AI infrastructure stocks.
Extreme Networks Investment Narrative Recap
To be comfortable owning Extreme Networks, you need to believe the firm can turn its AI centric networking portfolio into steadier recurring software and subscription income, not just lumpy hardware and large public sector deals. The Agent ONE Coworker launch fits that story, but the most important near term catalyst is still real adoption of Extreme Platform ONE across large enterprises and governments.
The biggest risk remains concentration in government and education budgets, along with stiff competition from much larger vendors with deeper R&D pockets. If Agent ONE and its Nudge capability do not materially reduce churn, raise attach rates, or support higher value contracts, this news will be operationally interesting but not decisive.
The Agent ONE Coworker general availability is the headline announcement that matters here. It plugs directly into the existing Extreme Platform ONE subscription, which is where a lot of the long term thesis around higher SaaS ARR, better retention, and improved margin structure sits for Extreme Networks.
For you as a shareholder, the practical question is whether this AI coworker suite actually tightens customer lock in and supports new commercial models like MSP or consumption based billing. Execution risk around scaling those models, winning beyond a few marquee government contracts, and holding pricing power against Cisco and HPE will likely drive how much of this AI story turns into durable numbers.
Extreme Networks' current analyst script points to revenues of $1.7b and earnings of $60.2 million by 2029, assuming a 9.8% yearly revenue growth rate. This would be an increase from earnings of $42.1 million today and implies an earnings increase of about $18.1 million over that period.
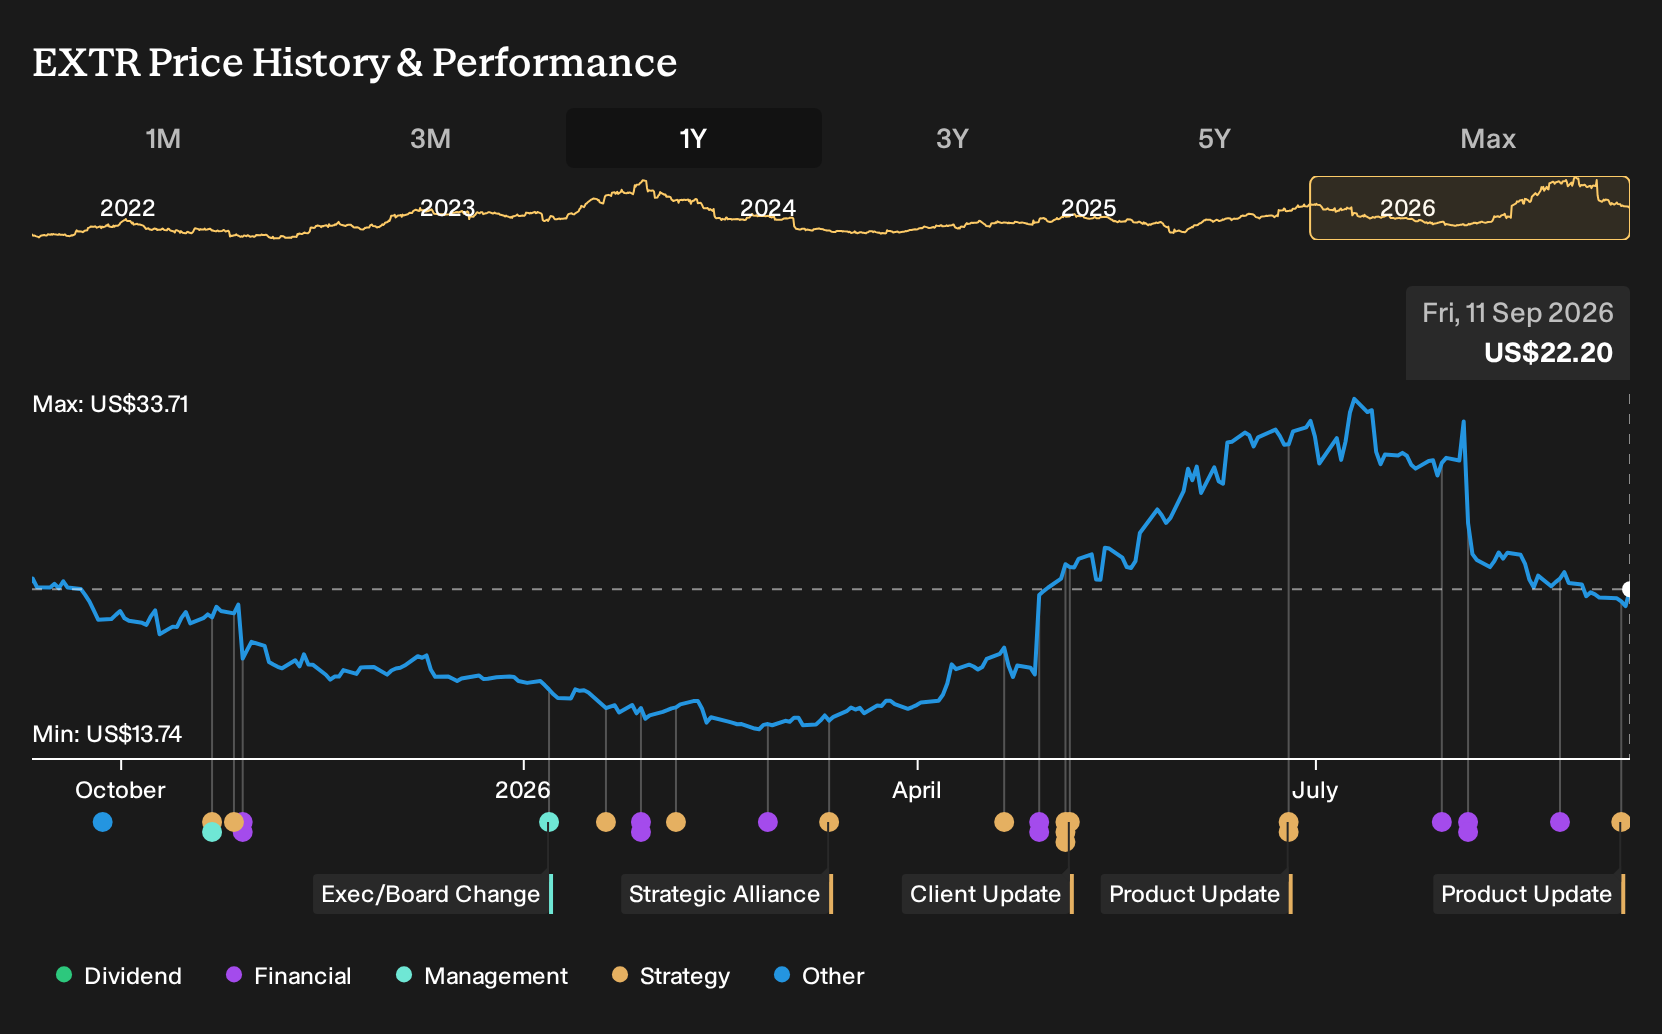
Uncover why Extreme Networks' fair value indicates a 51% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some analysts put more weight on Extreme Networks' AI push and assume stronger traction for Platform ONE. That optimistic camp was modeling about US$1.7b of revenue and US$45.2 million of earnings by 2029, with the stock on a 140.4x P/E before this Agent ONE Coworker news, so their storyline may shift meaningfully from here.
Explore 4 other Extreme Networks fair value estimates, including one that suggests up to 134% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Extreme Networks research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Extreme Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extreme Networks' overall financial health at a glance.
Looking For More Ideas Beyond Extreme Networks?
If the Extreme Networks story has you thinking about how AI, cash flow resilience, and balance sheet strength fit into a broader portfolio, it may be worth lining up a few contrasting plays using the Simply Wall St Screener.
- For investors who want potential upside without ignoring quality, scan through a curated pool of 15 high quality undiscovered gems that pair solid fundamentals with under-the-radar stories.
- If stability matters more than excitement right now, narrow your focus to a list of solid balance sheet and fundamentals (23 results) that can help you filter for companies with stronger financial footing.
- Those looking to tilt toward income can start with a 6 dividend fortresses that screens for higher yields while still letting you compare business strength side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com