
Is Quanta Services (PWR) Trading At A Premium To Fair Value?
Quanta Services has delivered a very strong 5 year run, yet current valuation checks suggest the stock trades at a premium to its intrinsic value estimate and to traditional market multiples.
- The share price has returned 453.7% over 5 years, which places a lot of faith in the company’s ability to keep converting its infrastructure work into long term cash flows.
- Expectations for continued demand in utility and infrastructure projects can support the current share price. However, any pressure on project execution or cash flow timing may challenge that optimism.
- Quanta Services scores 0 out of 6 on broader valuation checks, which points to a stock that screens expensive rather than a clear bargain.
The issue now is whether Quanta Services offers enough long term cash flow potential to justify a market price that sits above the current intrinsic value estimate.
Balance that kind of five year surge in Quanta Services with a fresh look at other infrastructure plays that still screen as potentially cheaper using our 39 power grid technology and infrastructure stocks.
Has Quanta Services Run Too Far on Cash Flow?
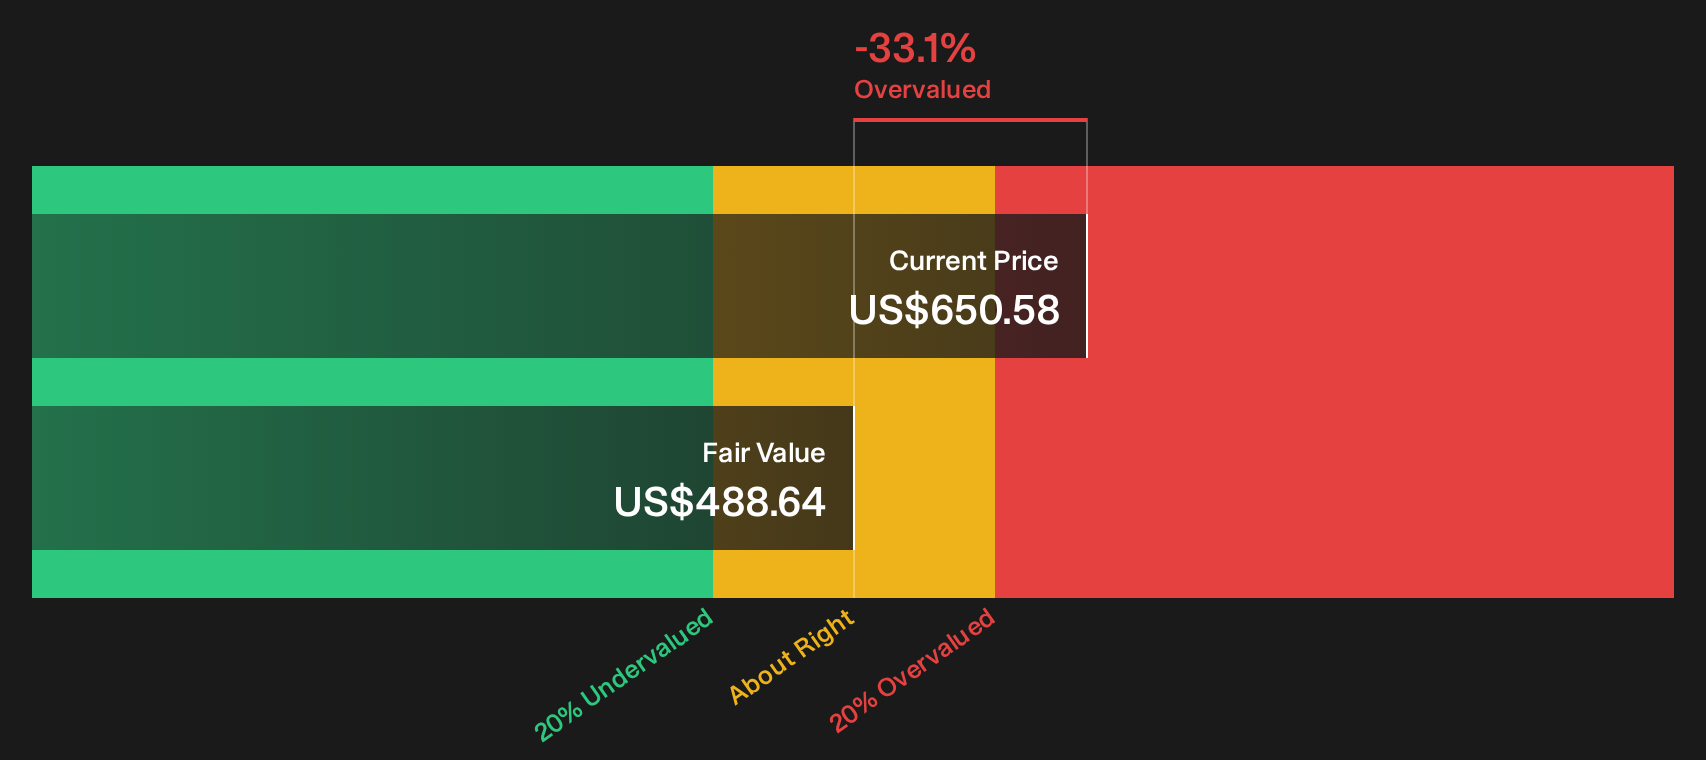
The Discounted Cash Flow model here projects how much cash Quanta Services might generate for shareholders over time, then brings those figures back to today’s dollars. On the latest twelve month numbers, the business produced about $2.36b in free cash flow, and the forecast assumes that this cash generation keeps growing rather than tapering off quickly.
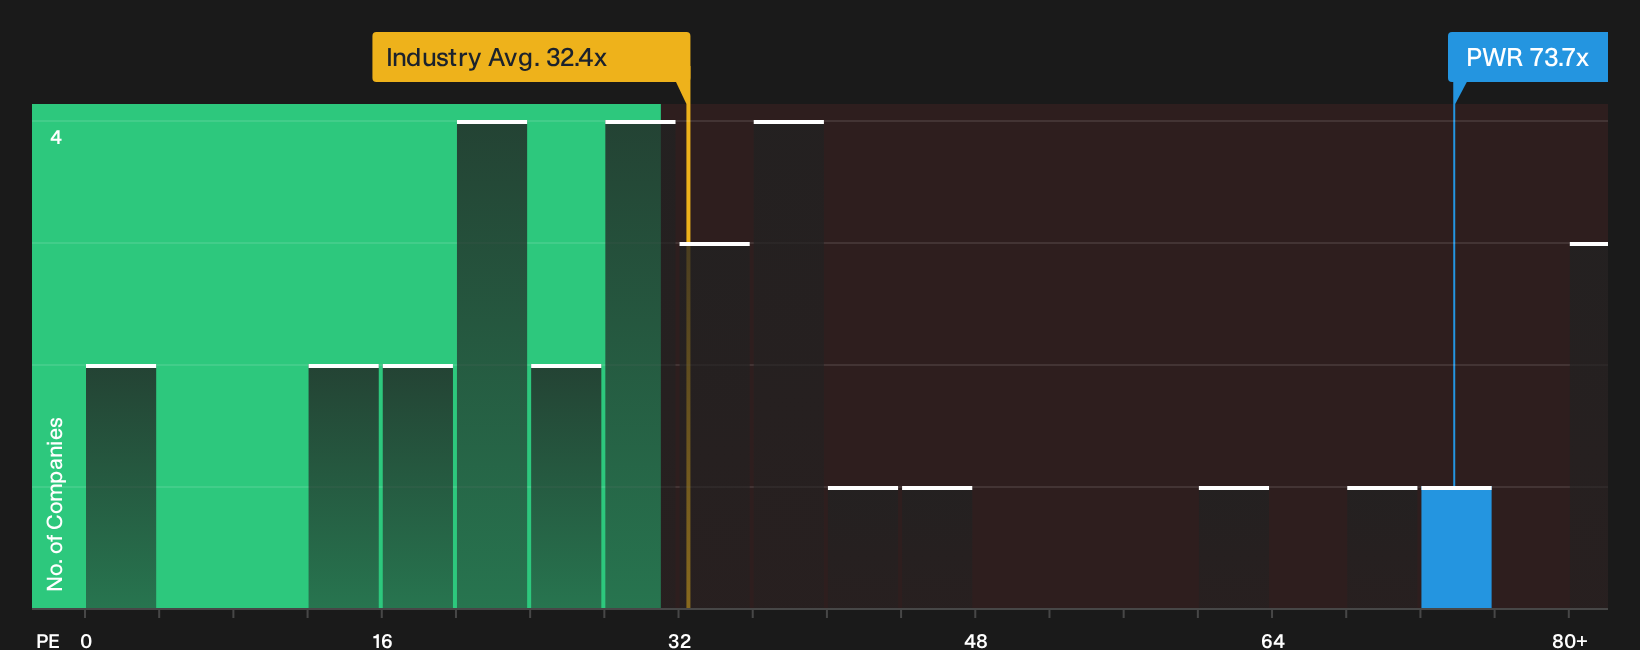
Under those inputs, the intrinsic value for Quanta Services comes out at about $488 per share, which sits well below the current market price and implies the stock trades roughly 33.1% above that estimate. The current P/E of 73.7, compared with an industry average of 32.4 and a fair ratio of 38.8, points in the same direction, as do the much higher P/B and P/S multiples than the broader Construction group.
On this model and these cash flow assumptions, Quanta Services currently appears overvalued.
Our Discounted Cash Flow (DCF) analysis suggests Quanta Services may be overvalued by 33.1%. Discover 31 high quality undervalued stocks or create your own screener to find better value opportunities.
Is Quanta Services Getting Expensive on Earnings?
The P/E ratio works well for Quanta Services because earnings sit at the centre of how investors usually price established contractors. On this measure, the stock changes hands at about 73.7x earnings, more than double the Construction sector average of roughly 32.4x and also well above the peer group on about 35.0x.
A more tailored yardstick, which blends Quanta Services’ size, industry, profitability and risk profile, suggests a fair P/E closer to 38.8x. That is roughly half the current multiple. The gap signals that a lot of confidence is already embedded in the price and that buyers today are paying a sizeable premium relative to what this model would typically support for a contractor in this space.
On the P/E test alone, Quanta Services looks overvalued compared with both its sector and the fair multiple implied by its fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
The Quanta Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Quanta Services pick up exactly where this valuation puzzle leaves you. They spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth far more, or far less, than today’s price on the market. Rather than leaning on a single multiple or model point, each narrative explains the assumptions sitting behind its view of fair value so you can compare those expectations with Quanta Services' actual results over time.
Community views on Quanta Services are sharply split, with one camp seeing a rare compounder and the other flagging valuation and execution risk.
Bull case: 8% undervalued
"The long case is simple: Quanta sits at the intersection of several unusually durable spending waves, including aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand."
Read the full Bull Case to see why Quanta Services could be undervalued
Bear case: 27% overvalued
"The company’s increasing reliance on large, multi-year projects exposes it to heightened project concentration risk; any major project delays or cancellations, particularly amid regulatory and permitting complexity, threaten significant earnings volatility and unpredictability in future quarters."
Read the full Bear Case to see why Quanta Services could be overvalued
Do you think there's more to the story for Quanta Services? Head over to our Community to see what others are saying!
The Bottom Line
Quanta Services now screens as overvalued on both intrinsic value work using Discounted Cash Flow and on traditional earnings multiples, with broader checks also pointing to a weak value profile. The common thread is simple: a lot of future cash generation is already embedded in the price. For current holders, the key question is whether project execution and cash conversion can keep matching those rich expectations. For potential new investors, the crux of the debate is whether that premium multiple proves justified by long term infrastructure demand or whether sentiment cools if large projects or cash flow timing disappoint.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com