
Has CoStar Group (CSGP) Fallen Far Enough To Look Fairly Valued?
CoStar Group stock has suffered a deep drawdown over the past few years, yet current market multiples still suggest the shares may be cheaper than the past performance might imply. With a mixed overall value score and a steep price decline already in place, investors are weighing whether the current quote fairly reflects the business risk and earnings power.
- Over the past 5 years, CoStar Group has delivered a cumulative share price decline of roughly 65.9%, which raises the question of how much bad news is already in the price.
- Future revenue growth in CoStar Group's data and marketplace platforms can support the current valuation. Any slowdown in customer adoption or weaker profitability, however, could limit how much the market is willing to pay for the stock.
- The broader valuation checks present a mixed picture rather than a clear bargain or clear overvaluation, with CoStar Group scoring 3 out of 6 on value metrics.
The issue now is whether CoStar Group's current price already reflects these risks or if the market is still paying too much for the earnings profile on offer.
Spot fresh opportunities beyond CoStar Group by comparing its pullback and mixed value score against our curated list of 31 high quality undervalued stocks.Is CoStar Group Still Cheap on Sales?
P/S fits CoStar Group because investors often focus on revenue when a business is still leaning heavily on reinvestment and reported earnings can look thin.
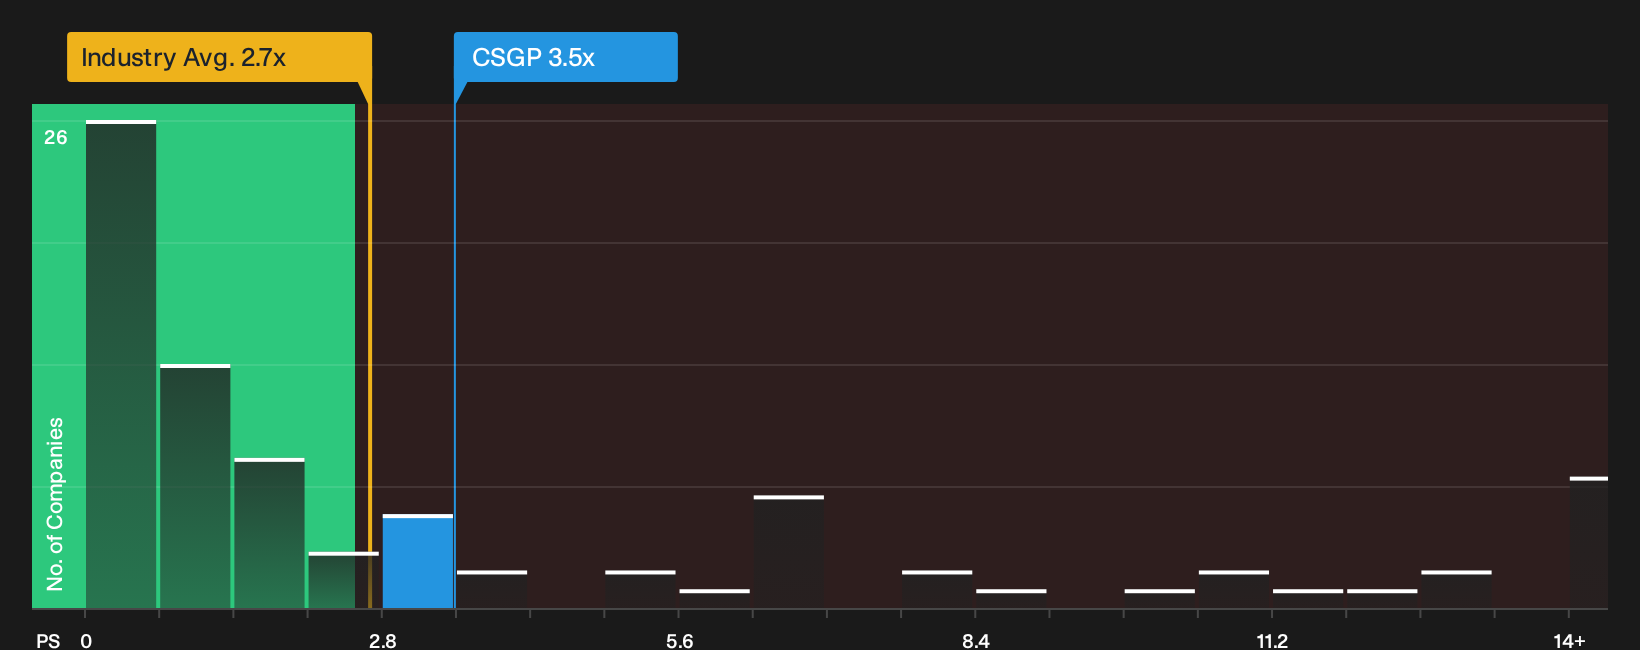
On this yardstick, CoStar Group trades at about 3.5x P/S, above the real estate industry average of roughly 2.7x and also higher than the peer group at about 1.4x. The fair P/S ratio estimated for the company is closer to 4.0x, which is higher than where the stock is currently priced. That indicates the market is not paying the level implied by this tailored benchmark, even though the raw comparison against the sector indicates a premium.
The gap between the current 3.5x and the 4.0x fair multiple is not huge, but it points to some headroom if the business delivers the revenue profile that the market-multiple model is assuming.
On the P/S metric, CoStar Group appears undervalued relative to the fair multiple implied by its characteristics.
See what the numbers say about this price — find out in our valuation breakdown.
The CoStar Group Narrative: What Would Justify Today's Price?
Narratives for CoStar Group pick up where the valuation puzzle leaves off, by spelling out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or materially less than today's price on Simply Wall St's Community page. Rather than just giving a single output from a ratio or model, they unpack the future conditions that underpin that figure so you can watch how reality lines up with those assumptions over time.
Community views on CoStar Group could hardly be further apart, with one camp leaning into platform expansion and the other fixating on bookings risk and competition.
Bull case: 18% undervalued
"Aggressive investment in the Homes.com platform and rapid sales force expansion are enabling accelerated penetration in residential real estate, opening up a vast addressable market and creating meaningful opportunities for top-line growth and revenue diversification..."
Read the full Bull Case to see why CoStar Group could be undervalued
Bear case: 22% overvalued
"Bearish analysts point to "muted" net bookings in recent quarters and weaker than expected Q2 revenue as key reasons to cut ratings and price targets..."
Read the full Bear Case to see why CoStar Group could be overvalued
Do you think there's more to the story for CoStar Group? Head over to our Community to see what others are saying!
The Bottom Line
CoStar Group screens as mildly undervalued on its tailored P/S yardstick, yet broader checks paint only a mixed picture rather than a clear mispricing. The valuation case now turns on whether revenue growth and marketplace adoption are strong enough to support that higher implied multiple without eroding profitability. The central debate is simple. Either the current discount reflects temporary doubt about execution on Homes.com and other platforms, or it is the market correctly pricing in the risk that growth or margins fall short of expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com