
What Is Drawing Fresh Attention To ZoomInfo Technologies (GTM)?
ZoomInfo Technologies integration with Cursor sparks fresh attention
ZoomInfo Technologies (GTM) just pushed its MCP Server live on the Cursor Technologies Marketplace, putting its verified go to market data directly inside Cursor’s AI coding agent for developers and revenue teams.
For investors watching ZoomInfo Technologies, the new Cursor tie-up lands against a mixed price backdrop, with the share price down 7.99% over the past week and 6.17% over 30 days, yet showing a 33.8% 90-day share price return after heavy longer term total shareholder losses.
Compare how ZoomInfo Technologies stacks up against other AI data and automation plays by scanning our hand picked 89 AI infrastructure stocks plugged into fast growing software workflows.
The Cursor link-up gives ZoomInfo Technologies fresh product proof at the same time the share price is still working through heavy long term damage. Is this reset mostly about sentiment or about what the business is worth now?
Most Popular Narrative: 62% Undervalued
At a last close of $3.80 against a narrative fair value of $10.01, ZoomInfo Technologies is framed as heavily reset yet still carrying sizeable upside in the most followed storyline.
The accelerating adoption of advanced AI-powered features such as Copilot and operations solutions is unlocking higher value use cases for enterprise customers, driving strong upsell momentum and expansion into new user personas. This broader product adoption raises average contract values and supports top-line revenue growth through both new customer wins and deeper penetration within existing accounts.
Read the complete narrative. Read the complete narrative.
Want to see what underpins that valuation gap? The narrative leans on a sharp profit swing, a richer margin profile, and a future earnings multiple below many software peers.
Result: Fair Value of $10.01 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, two pressure points could flip that undervalued ZoomInfo Technologies narrative fast: tighter privacy rules that restrict data collection and large customers choosing to build competing in-house datasets.
Find out about the key risks to this ZoomInfo Technologies narrative.
Another View: ZoomInfo Technologies on Sales-Based Valuation
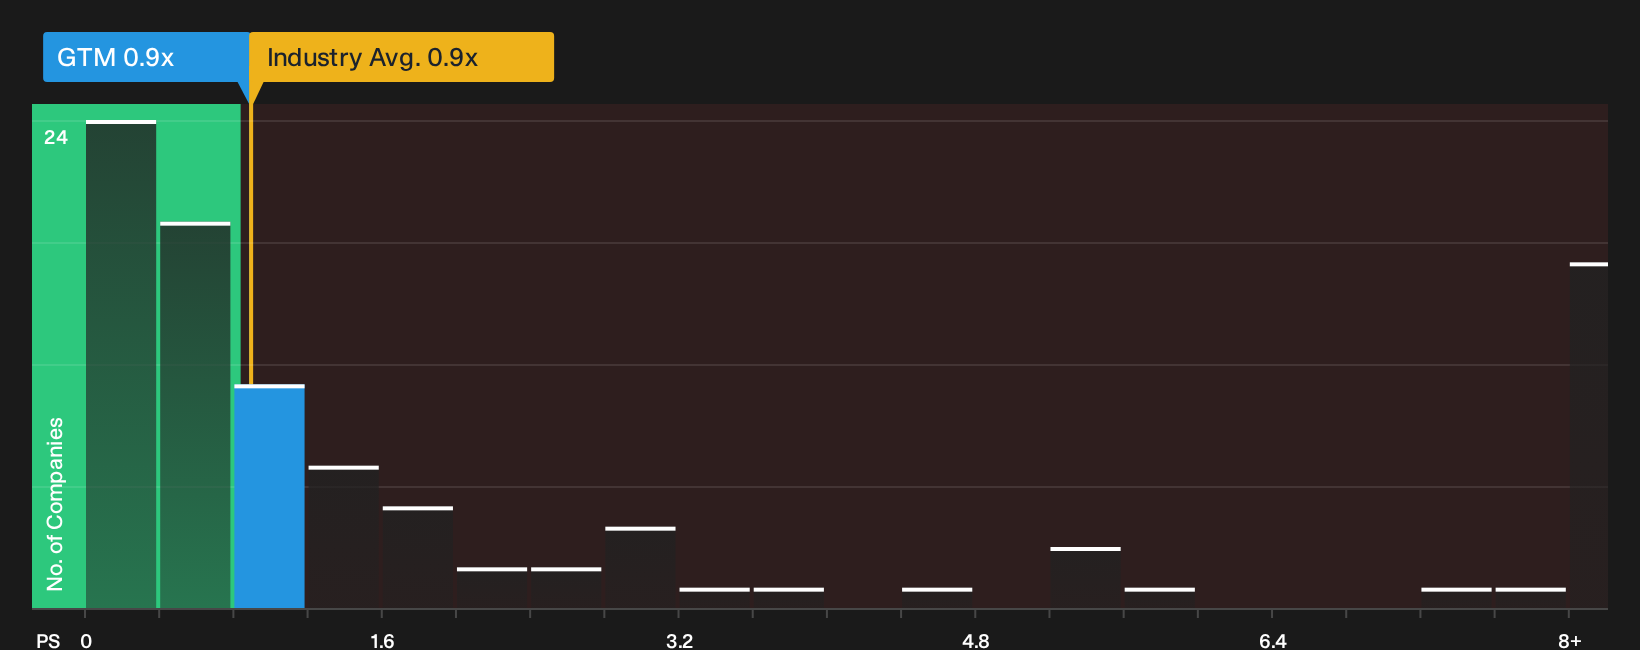
The first storyline around ZoomInfo Technologies leans heavily on future cash flows and a large gap to fair value. A simple P/S check paints a cooler picture. The stock trades on a 0.9x P/S, which is in line with the US Interactive Media and Services average of 0.9x and only slightly below an estimated fair ratio of 1.1x. That hints at some room for rerating, but not the dramatic discount suggested by the cash flow work. Which version of value do you trust more for a business that is still loss making and facing revenue pressure?
For a closer look at how the numbers line up against peers and where the fair ratio could matter if sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on ZoomInfo Technologies leaves you torn between reset risk and recovery upside, move quickly and weigh both sides of the ledger. Start by checking the 2 key rewards and 1 important warning sign.
Looking for more ZoomInfo Technologies sized ideas?
ZoomInfo Technologies might be on your radar now, but the real edge comes from lining up a full watchlist of high conviction ideas that match your style.
- Target quality at a discount by scanning a curated 31 high quality undervalued stocks that filters for strong fundamentals without stretching on price.
- Anchor your portfolio with income by reviewing a focused 6 dividend fortresses built around higher yielding payouts that aim for resilience.
- Dial down volatility risk by working through a 11 resilient stocks with low risk scores tailored to businesses with sturdier financial profiles and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com