
Sandisk (SNDK) Renews Its $1.5b Credit Line, Is The Stock Still Cheap?
Sandisk (SNDK) has just overhauled its lending playbook. The flash storage producer signed a US$1.5b revolving credit facility amendment that refreshes its bank commitments and extends access to multi currency funding.
Recent trading tells a mixed story for Sandisk. The share price has slipped 3.5% over the past day and is down 22.5% across three months, yet the year to date share price return of 493% and one year total shareholder return of roughly 18x still signal powerful momentum. Recent conference appearances and this fresh credit facility are helping to test that momentum rather than ignite it.
Scan beyond Sandisk and see which peers are also drawing intense AI data demand with the hand picked 89 AI infrastructure stocks.
After a move this extreme, with Sandisk now sitting on a fresh US$1.5b credit line and a share price reset in recent weeks, does the current risk reward still favor new money stepping in?
Most Popular Narrative: 23.2% Undervalued
Sandisk's most followed narrative pegs fair value at about $2,126 per share, noticeably above the last close of $1,633.35, which frames the latest pullback in a different light.
Rapid AI and cloud workload expansion is driving data center NAND exabyte growth at a pace well above overall supply. This positions Sandisk's enterprise SSD portfolio and deepening hyperscaler engagements to support sustained revenue acceleration and structurally higher pricing power, benefiting earnings.
Read the complete narrative. Read the complete narrative.
Want to see why this fair value runs well ahead of the screen price? The narrative leans on aggressive top line expansion, sharp margin uplift and a leaner future earnings multiple. The real story sits in how those three levers interact over time, not in any single headline metric.
Analysts behind this widely tracked storyline are not just assuming stronger sales. They are also baking in a shift to higher profitability and using a discount rate of 8.58% to pull those future cash flows back into today’s dollars. The result is a fair value estimate that treats Sandisk as a business with meaningful earnings power and a lower future valuation multiple than many current US tech peers.
Result: Fair Value of $2,126 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Sandisk narrative wobbles if NAND moves from tight supply to glut, or if AI driven demand cools and leaves heavy capacity spend underused.
Find out about the key risks to this Sandisk narrative.
Another View: Multiples Tell A Different Sandisk Story
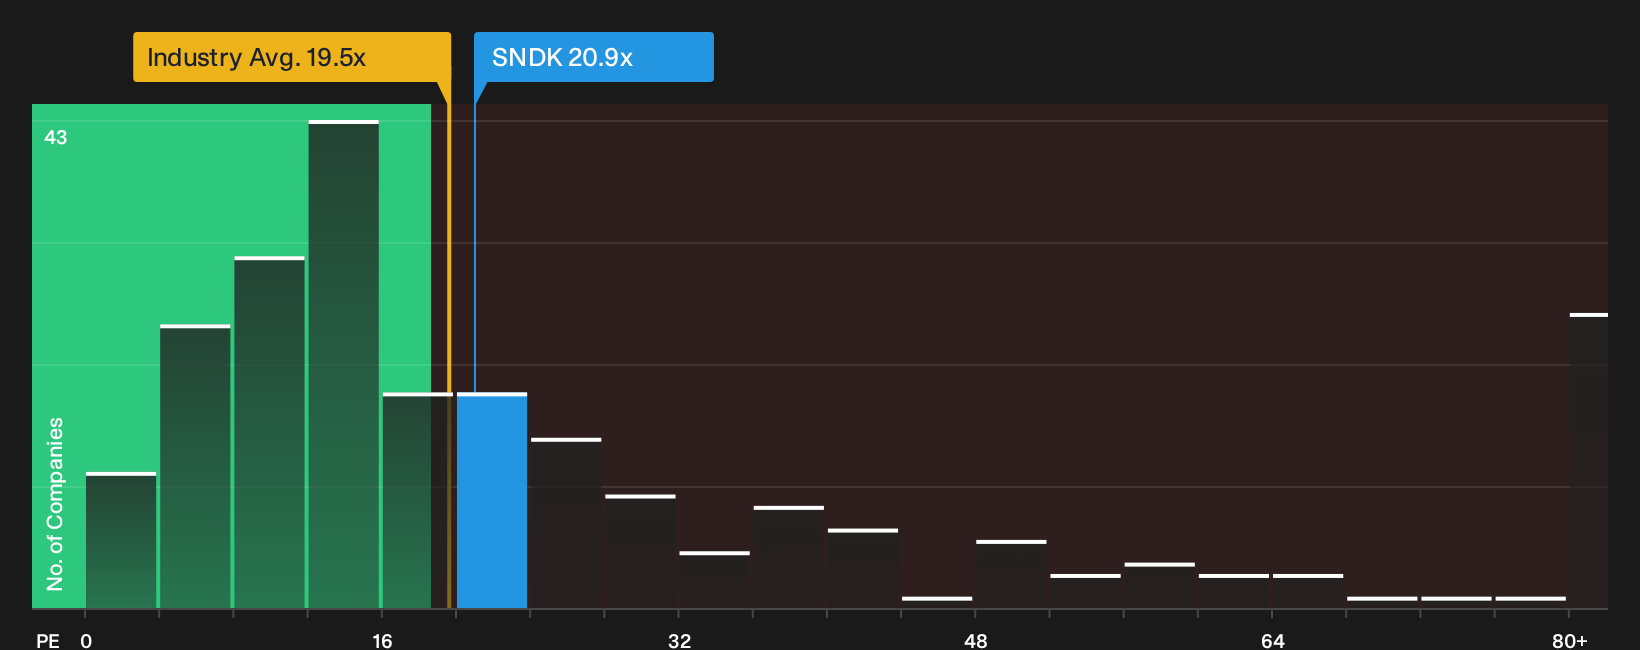
The fair value narrative leans heavily on future cash flows, yet the current P/E of 20.9x adds a different flavor. It sits below the US Tech sector on 29.2x, above the global Tech group on 19.5x, and well under a fair ratio estimate of 58.1x. That mix hints at both a premium to some peers and a large theoretical upside gap. How comfortable are you with the risk that the market never closes it?
Investors weighing those ratios against the Sandisk growth story might want to stress test whether earnings quality, profit forecasts and sentiment justify that kind of fair ratio, or if today’s multiple already reflects a generous share of the optimism. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this often split opinion, so move quickly, review the key data for Sandisk, and weigh both the upside and the downside yourself with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Sandisk?
Do not stop with Sandisk. Turn today’s research momentum into a broader watchlist by scanning other opportunities that match your return goals and risk comfort.
- Target potential mispricings by reviewing a carefully filtered set of 31 high quality undervalued stocks that combine attractive valuations with solid business profiles.
- Lock in income-focused opportunities by assessing companies in the 6 dividend fortresses that pair strong yields with staying power.
- Control downside risk by building a shortlist from the 11 resilient stocks with low risk scores so you are not chasing upside without checking resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com