
Avolta (SWX:AVOL) Extends Mexico Airport Deals As Undervalued Narrative Faces A Fresh Test
Avolta (SWX:AVOL) just locked in extended contracts with Grupo Aeroportuario del Pacífico across four major Mexican airports, securing exposure to more than 30 million travelers a year and future store expansion opportunities.
Avolta’s latest contract wins and its September 2026 blockchain payment pilot come against a mixed price backdrop, with the share price at CHF43.6 after a 30 day share price return down 12.31% and a 3 year total shareholder return of 22.61%, which points to longer term momentum still intact.
Scan other travel and consumer-focused stocks that analysts have hand-picked for similar contract-driven and payment-technology stories using the 618 high quality undiscovered gems.
Avolta just locked in fresh Mexican contracts and is piloting new payment rails while the share price has pulled back. Does that set up a better entry now, or is patience on valuation the smarter move?
Most Popular Narrative: 16.1% Undervalued
Avolta’s most followed narrative sees fair value above the last close of CHF43.6, framing the recent pullback as a pricing gap rather than a verdict.
Ongoing synergies from integration of Dufry and Autogrill, along with rigorous cost discipline and capital allocation, are expected to yield operating efficiency gains and further expand net margins and free cash flow over time.
Read the complete narrative. Read the complete narrative..
Curious what justifies that higher fair value? The story leans heavily on measured revenue growth, firmer margins and a richer earnings multiple held together by an 8.8% discount rate.
Result: Fair Value of CHF51.94 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Avolta narrative depends on air travel holding up and key concessions remaining secure, so any traffic shock or lost airport contracts could quickly challenge it.
Find out about the key risks to this Avolta narrative.
Another View On Avolta’s Valuation
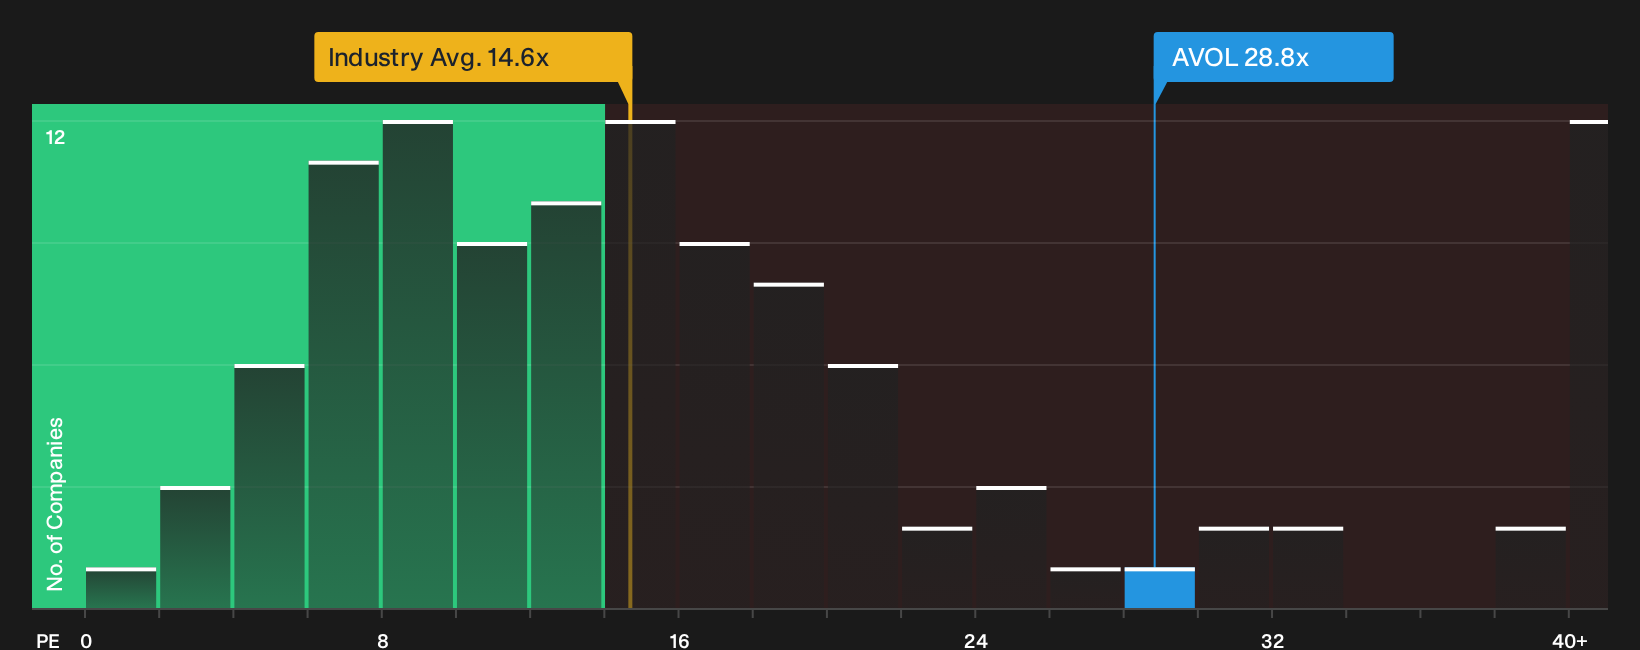
The earlier narrative leans on a discounted cash flow style fair value of CHF51.94, which frames Avolta as undervalued at CHF43.6. A simple P/E lens tells a very different story. At 28.8x earnings versus 15x for the European Specialty Retail group and 16.7x for peers, the stock looks expensive on earnings. Is that a quality premium you are comfortable paying, or a margin of safety you would rather see wider?
For a closer look at how earnings-based pricing compares with other options, have a read of our valuation breakdown next See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Seeing both optimism and caution around Avolta, it makes sense to move quickly, stress test the thesis against the data and then decide where you land. To weigh up the upside against the red flags in one place, start with these 4 key rewards and 2 important warning signs.
Looking for more Avolta-sized investment ideas?
If you like how the Avolta story blends contract wins with valuation debate, you may want a wider watchlist working for you in the background.
- Target cash rich, attractively priced businesses by scanning the market through the 184 high quality undervalued stocks that analysts have already filtered for quality and pricing discipline.
- Prioritise resilience and focus on the 99 resilient stocks with low risk scores that scores highly on financial strength and lower historical risk indicators.
- Look for underfollowed opportunities by combing through the 618 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com