
Why Par Pacific Holdings (PARR) Is Back In The Spotlight
Par Pacific Holdings (PARR) has been in focus after refining peers, including HF Sinclair, recorded gains of more than 50% over the past six months as tight capacity, low fuel inventories, and steady demand supported margins.
Par Pacific Holdings has ridden this refining upswing hard, with a 90 day share price return of 58.28% and a year to date gain of 136.32% to reach US$84.65. Momentum has been strong for existing shareholders, reflected in a 1 year total shareholder return of 157.92% and a 5 year total shareholder return of 467.74%. However, that kind of track record also raises the stakes around what investors expect from future refining margins and earnings resilience.
Scan for other refiners catching similar tailwinds by focusing on our curated shortlist of 39 power grid technology and infrastructure stocks that help move energy from source to end user.
Par Pacific Holdings now trades near its analyst price target after a steep run. Does it make more sense to wait for a pullback or start pencilling in value at this level?
Most Popular Narrative: 10% Overvalued
Par Pacific Holdings closed at $84.65 compared to a popular fair value narrative of $84.57, so the gap is small but worth unpacking in more detail.
The analysts have a consensus price target of $84.57 for Par Pacific Holdings based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $95.0, and the most bearish reporting a price target of just $65.0.
Read the complete narrative. Read the complete narrative.
Analysts are incorporating expectations for changing revenues, margins, and a higher future earnings multiple to justify that $84.57 figure. Want to see exactly how those moving parts, including the profit bridge into the late 2020s, line up in their models.
Result: Fair Value of $84.57 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Par Pacific Holdings faces concentration risk in its Hawaii and Western U.S. refining hubs, and its older facilities and higher leverage can quickly turn into pressure points if conditions shift.
Find out about the key risks to this Par Pacific Holdings narrative.
Another View: Par Pacific Holdings Through The Earnings Lens
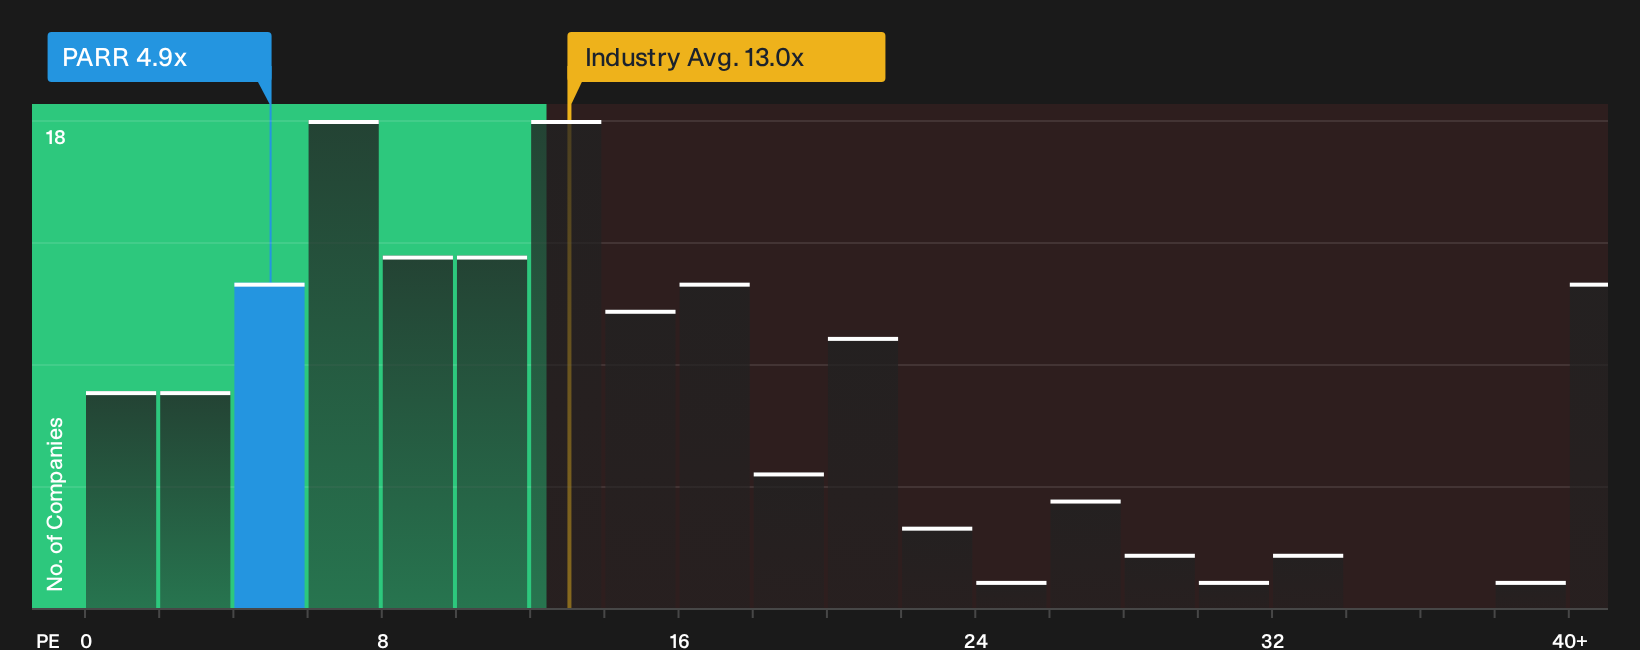
Analysts frame Par Pacific Holdings as roughly 10% overvalued at $84.65, yet the current P/E of 4.9x tells a very different story. The broader US Oil and Gas group sits closer to 13x, and a fair ratio of 7.3x suggests the multiple could plausibly shift higher or lower from here.
That gap between 4.9x, 7.3x and 13x points to either valuation risk if margins fade or potential upside if current profitability holds up longer than the Street expects. Which scenario do you think the market is really pricing in right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Par Pacific Holdings story can make it hard to pin down a clear stance, so move quickly, test the numbers yourself, and weigh both the upside and the downside through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Par Pacific Holdings?
If Par Pacific Holdings already sits on your radar, you can use that momentum to broaden your watchlist and test your thinking against fresh, data driven opportunities.
- Target potential mispricings by scanning a focused universe of companies with stronger fundamentals and room for rerating through the 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that combine higher yields with resilient payout metrics using the 6 dividend fortresses.
- Dial down portfolio stress with companies that show steadier earnings profiles and healthier financial structures through the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com