
SolarEdge Tie Up Might Change The Case For Investing In Infineon Stock
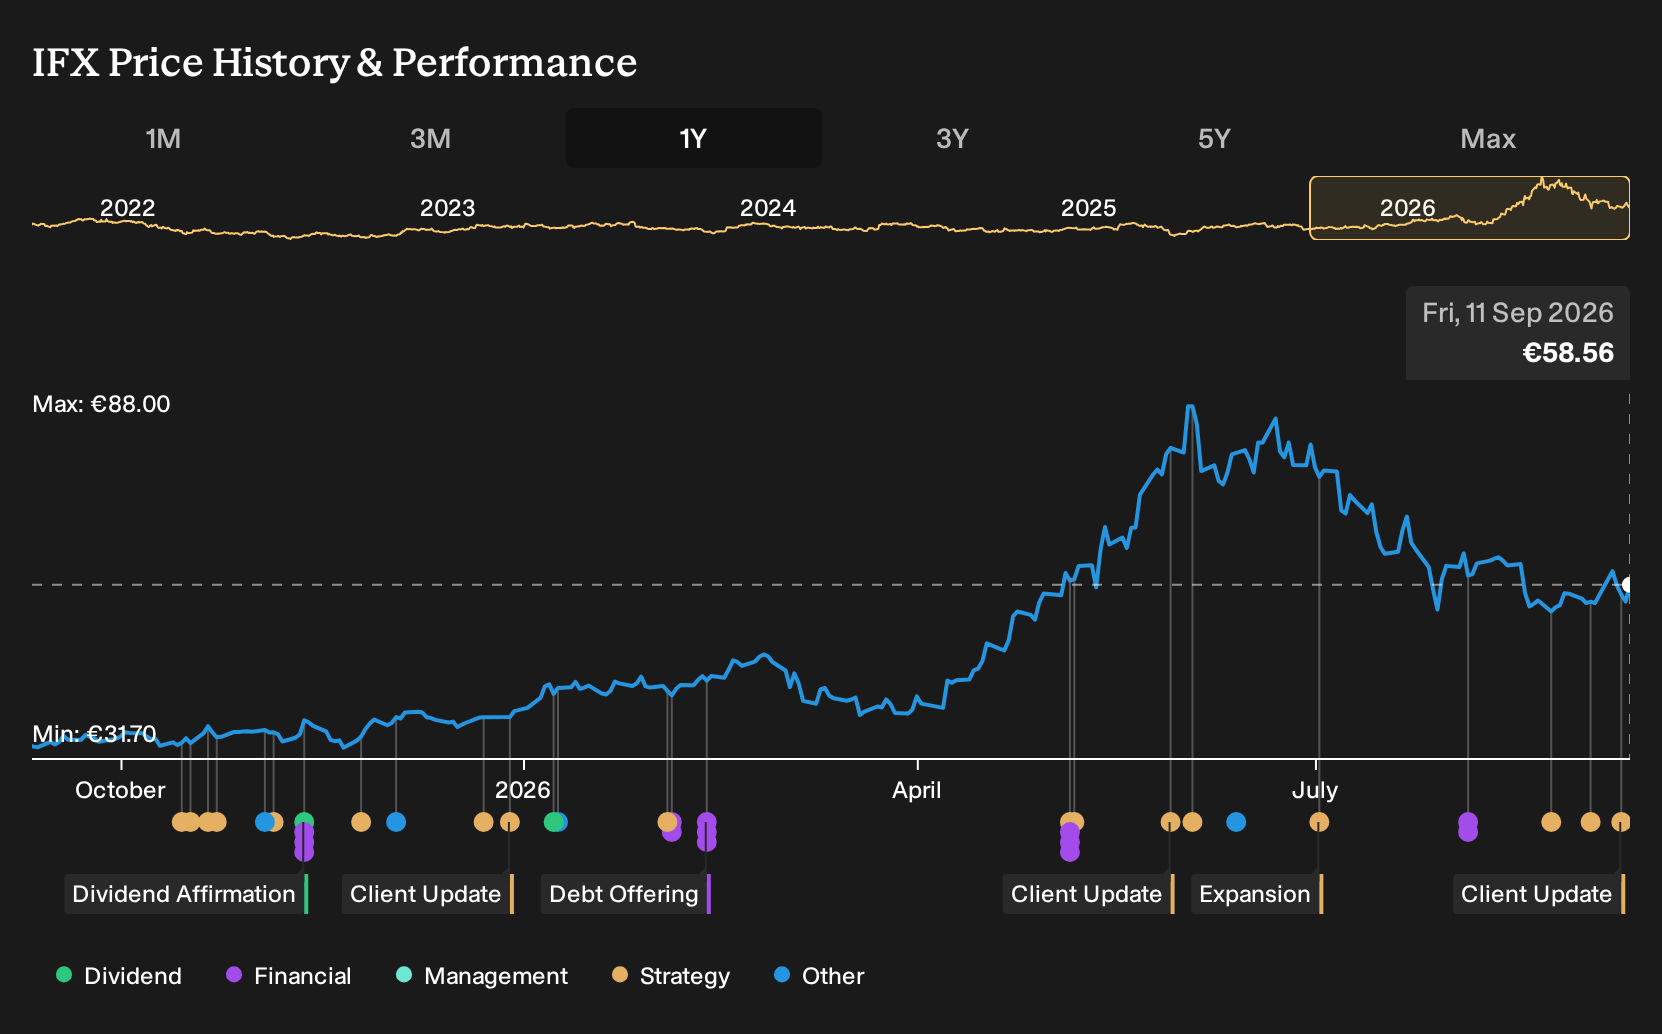
- In early September 2026, SolarEdge Technologies announced it extended its collaboration with Infineon Technologies to use Infineon’s silicon carbide JFET devices in solid-state circuit breakers for 800 VDC distribution in AI and hyperscale data centers.
- This move deepens Infineon Technologies’ role inside an 800 VDC, grid-to-rack powertrain for AI factories, tying its SiC portfolio directly to high value data center protection and distribution hardware.
- We will now explore how Infineon Technologies’ deeper role in 800 VDC solid-state protection could influence the broader investment narrative.
Scan how Infineon Technologies fits into the AI power backbone and compare it with other potential beneficiaries using a curated list of 89 AI infrastructure stocks for this theme.
Infineon Technologies Investment Narrative Recap
To own Infineon Technologies, you need to believe its power and sensor portfolio can keep finding real demand in AI data centers, renewable energy and electrification, while inventory and pricing stay under control. The SolarEdge extension reinforces that Infineon silicon carbide and JFET technology is embedded deeper in AI power trains, but it does not by itself resolve near term margin pressure or idle costs.
The near term swing factor still looks operational. Execution on inventory normalization, utilization of existing fabs, and discipline on capital spending remain central, especially with a high P/E and low current return on equity. The biggest risk stays the same: weaker end markets, excess stock at customers, or aggressive competitors could pressure pricing and keep those idle charges elevated.
The SolarEdge solid state circuit breaker work is tightly linked to the earlier solid state transformer collaboration that targets 800 VDC architectures for AI and hyperscale data centers. That earlier announcement placed Infineon power devices inside a single stage medium voltage to 800 to 1,500 VDC conversion platform with stated efficiency above 99%, which directly connects to the new protection layer design.
Viewed together, the SST and SSCB projects create a clearer operational path for Infineon Technologies into grid to rack AI infrastructure, a segment analysts already tie to faster earnings growth. The opportunity sits next to real risks, including price competition in silicon carbide, high investment needs and exposure to policy shifts in electrification, so execution quality across these programs matters as much as design wins.
Infineon Technologies' narrative projects €23.7b revenue and €4.8b earnings by 2029. This assumes 16.1% yearly revenue growth and an earnings increase of about €3.7b from €1.1b today.
Discover how Infineon Technologies' fair value points to a 48% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the lowest Infineon Technologies analysts focus on concentration risk in AI power. They worry that redirecting capacity from high voltage E mobility into data center power could backfire, which is why they were only pencilling in about €21.8b in revenue and €4.0b in earnings by 2029 before this SolarEdge news. Their view is clearly more cautious than consensus, and this new 800 VDC protection partnership could eventually push both narratives to shift.
Explore 3 other Infineon Technologies fair value estimates, including one that suggests as much as 14% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Infineon Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Infineon Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Infineon Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Infineon Technologies?
If the Infineon Technologies story has sharpened your interest in AI infrastructure and power electronics, it can be useful to widen the lens and compare it with other potential opportunities using the Simply Wall St Screener.
- Prefer to keep risk in check while still hunting for upside potential? Then scan a group of 99 resilient stocks with low risk scores that score well on resilience and financial robustness.
- If quality at a reasonable price is your priority, focus on companies with strong cash generation and balance sheets by running a search across a 618 high quality undiscovered gems that are not yet widely followed.
- Income focused investors who want cash returns today can zero in on payout durability by filtering for 161 dividend fortresses that pair higher yields with underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com