
Align Technology (ALGN) Stock Looks Cheap On Earnings While Broader Checks Stay Mixed
Align Technology stock has had a rough long run, with the share price down about 79.0% over five years, yet the current valuation checks on earnings multiples still screen the company as undervalued. For investors trying to make sense of Align Technology today, the question is whether that long slide has already priced in the key risks or if the recent mixed signals on value argue for more caution.
- The roughly 79.0% decline over five years points to a market that has heavily marked down expectations for Align Technology.
- Future demand for clear aligners and the company’s ability to defend pricing power can support the current valuation, while any sustained pressure on margins or slower procedure volumes may weigh on what investors are willing to pay.
- The broader valuation checks present a mixed picture rather than a clear bargain or clear overvaluation for Align Technology, with the stock scoring 4 on 6 value metrics.
The issue now is whether the current market price for Align Technology fairly reflects this combination of long term share price damage and a still not outright cheap valuation profile.
Contrast Align Technology’s long 5 year decline with other beaten down yet potentially mispriced opportunities by scanning our hand picked list of 32 high quality undervalued stocks.
Is Align Technology Still Cheap on Earnings?
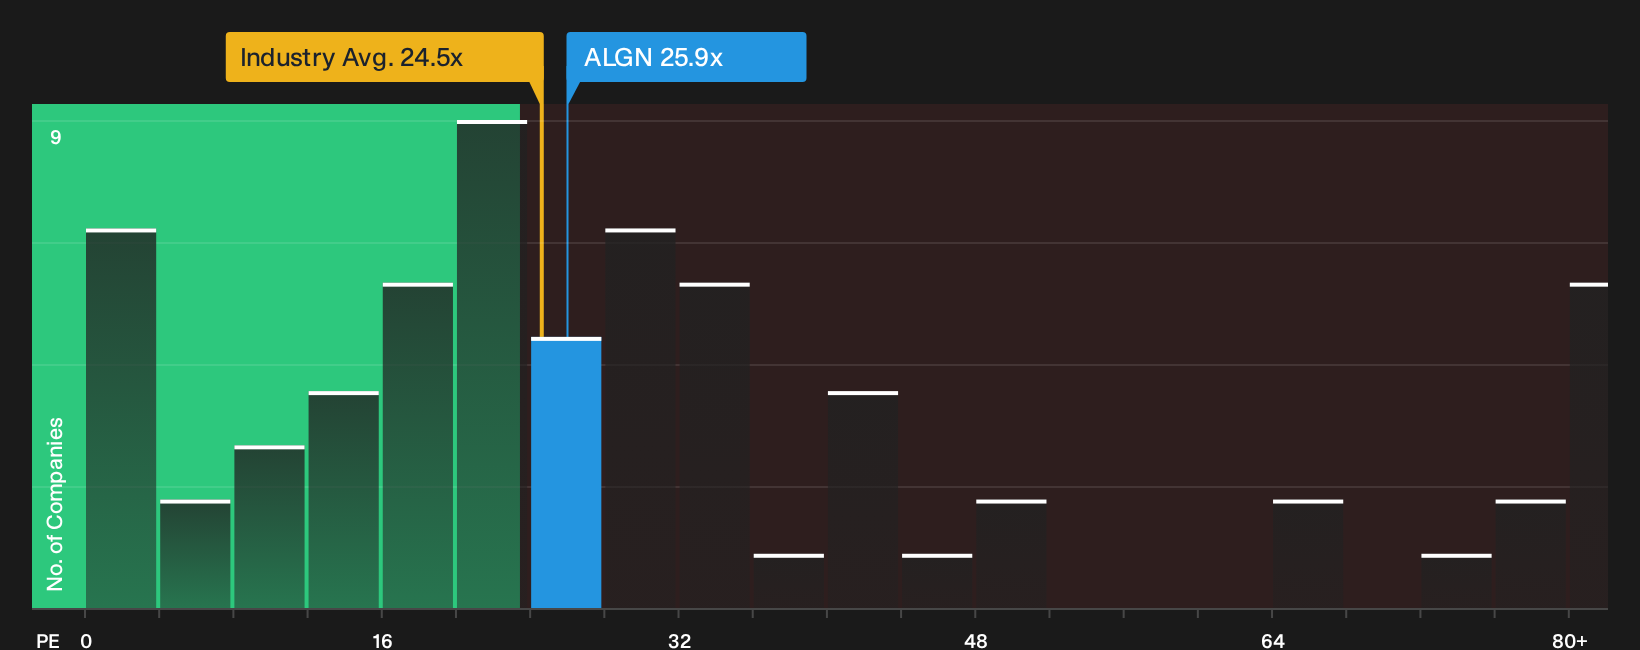
The P/E ratio fits Align Technology reasonably well because the market still judges the business heavily on its ability to turn orthodontic demand into earnings. Align Technology trades on a P/E of about 25.9x, which is close to the medical equipment sector average of roughly 24.5x and in line with the peer group near 25.2x. That cluster around the mid 20s indicates the market is not treating this as a distressed story on earnings, despite the long share price slide.
The more tailored fair P/E for Align Technology is estimated at about 30.0x, higher than where the stock changes hands today. That gap suggests investors are pricing the company below what this framework would expect once you factor in its margins, size and risk profile within medical equipment. For readers, it indicates the market is assigning a discount rather than a premium on this earnings yardstick.
On the P/E multiple alone, Align Technology stock appears undervalued compared with the fair ratio implied by its fundamentals and industry position.
See what the numbers say about this price — find out in our valuation breakdown.
The Align Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off for Align Technology and explain what path for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today’s price. Each narrative links its number to a concrete view of how Align Technology’s growth profile, profitability and risk picture could evolve, providing a reference point you can revisit as new information becomes available.
One of the top community narratives on Align Technology: 28% undervalued
"Bullish analysts point to multiple platform growth levers, including teen conversion, Advanced Restorative Treatment with lab partnerships, peer to peer channel expansion, continued ClinCheck development, and plans to scale direct fabrication…"
Read one of the top narratives on Align Technology
Do you think there's more to the story for Align Technology? Head over to our Community to see what others are saying!
The Bottom Line
Align Technology looks modestly undervalued on its P/E against both peers and a tailored fair multiple, but the broader checks only point to a mixed overall picture. That kind of discount often reflects doubts about how durable demand, pricing and margins will be rather than a clear mispricing. The key question from here is whether Align Technology can keep procedure volumes and profitability resilient enough for the current earnings multiple to hold or improve, instead of turning into a value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com