
Is Envista Holdings (NVST) Undervalued Or Is Its Premium P/E Already Priced In?
Envista Holdings (NVST) has been drawing attention after recent trading showed the share price at US$25.55, with performance mixed over different timeframes and longer term returns still recovering from earlier declines.
For Envista Holdings, the recent drop, including a 7 day share price return down 6.34% and a 30 day share price return down 8.98%, sits against a 17.8% year to date share price gain and a 21.61% 1 year total shareholder return. This pattern points to momentum cooling in the short run after a stronger rebound phase.
Scan how Envista Holdings stacks up against other healthcare stocks by running through the hand picked list of solid balance sheet and fundamentals (23 results) while momentum cools after its recent rebound.
Envista Holdings now trades well below some estimates of fair value after a choppy rebound, which raises a simple question. Do recent swings reflect a shift in sentiment, or something more fundamental in the business, when you line up the valuation numbers next?
Most Popular Narrative: 14% Undervalued
Envista Holdings is priced at $25.55 against a widely followed fair value estimate of $29.69, which frames the recent pullback as a valuation gap rather than a complete reset of expectations.
Increasing R&D investment (up 14% year-over-year) and successful launches of digital and AI-driven products (e.g., DTX Studio Clinic with AI, DEXIS CDCTs, Spark product line) enhance Envista's ability to capitalize on growing demand for digital dentistry, supporting both future revenue growth and gross margin expansion.
Want to see what underpins that $29.69 fair value for Envista Holdings? The narrative leans heavily on earnings expansion, richer profit margins, and a future earnings multiple that assumes investors keep paying up for this dental platform. Curious which forecasts and cash flow assumptions have to hold to support that view? The full narrative lays out the numbers behind the story.
Result: Fair Value of $29.69 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Envista Holdings faces pressure from China volume based procurement reforms and higher tariffs, which could squeeze margins and unsettle that underpriced narrative.
Find out about the key risks to this Envista Holdings narrative.
Another Angle On Envista Holdings Valuation
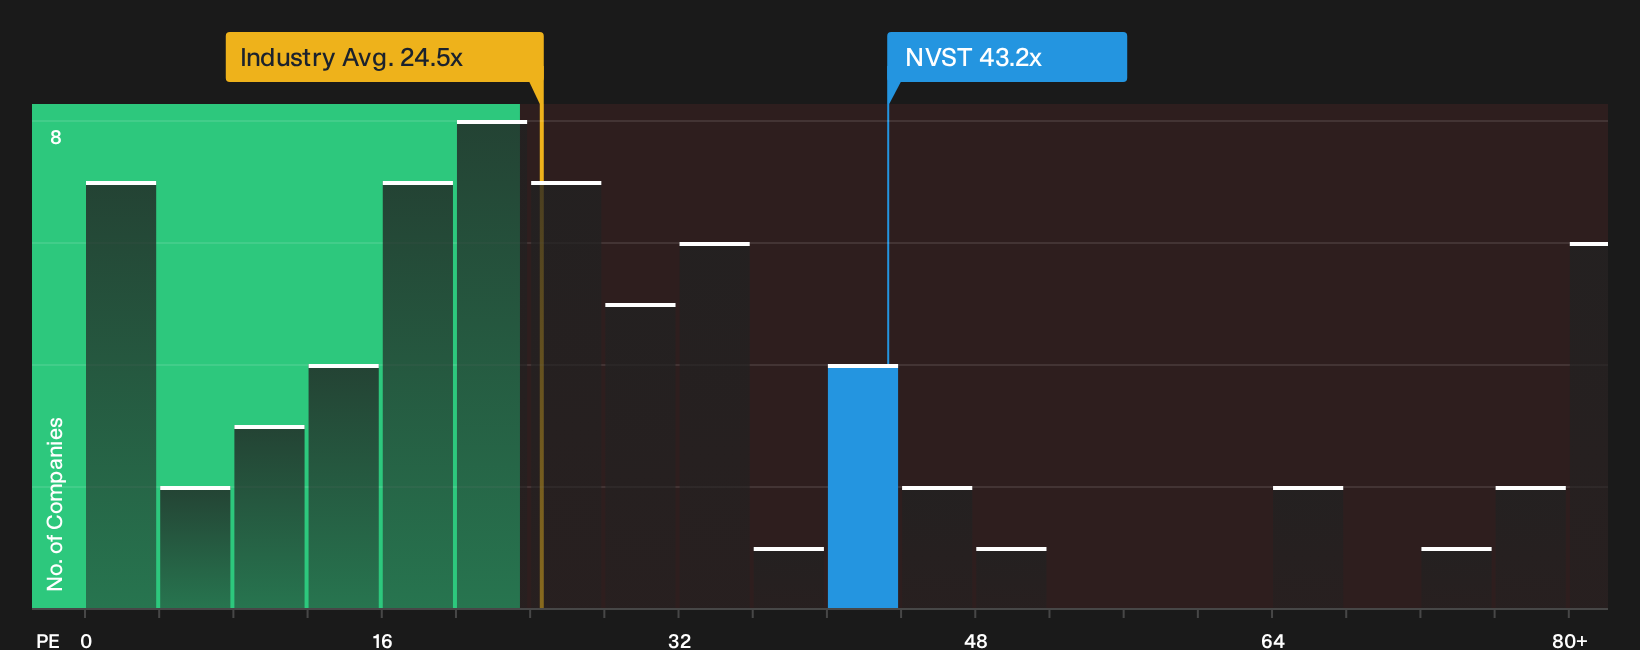
The story looks very different once the focus shifts from future cash flows to what the market is actually paying for Envista Holdings earnings today. The stock trades on a P/E of 43.2x compared with a peer average of 30.6x, while the fair ratio sits at 31.2x. That gap suggests investors are already paying a premium, so the discount to fair value may not be as straightforward as it first appears.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Envista Holdings can make the story feel split, so move quickly, review the key rewards, and weigh the 4 key rewards.
Looking for more Envista Holdings sized investment ideas?
Do not stop with Envista Holdings. Broader context from other opportunities can sharpen how you judge this setup and help you position with more confidence.
- Target potential mispricing by scanning the 32 high quality undervalued stocks that share solid fundamentals and may trade below what the market is currently willing to pay.
- Prioritise resilience by checking the 11 resilient stocks with low risk scores that screen for steadier balance sheets and lower historical risk scores.
- Get ahead of the crowd by reviewing the 15 high quality undiscovered gems that combine quality metrics with limited current attention from the wider market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com