
Does Early Debt Payoff Change The Bull Case For Constellation Brands Stock (STZ)?
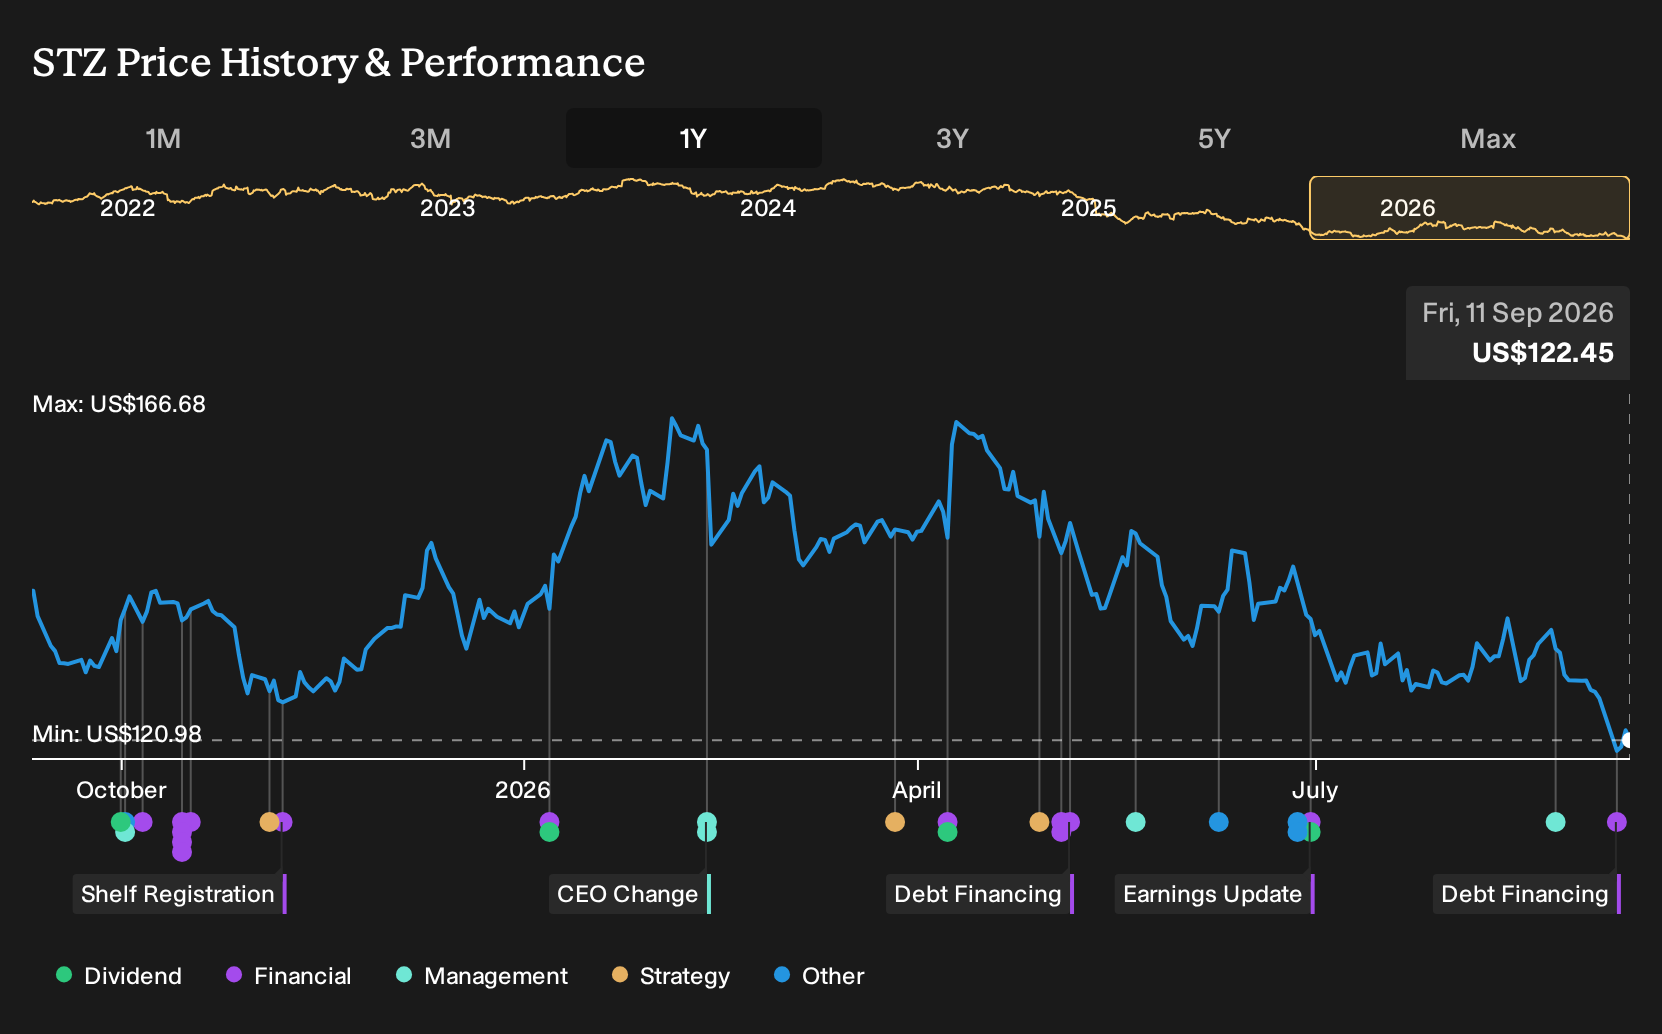
- Constellation Brands has already completed a full redemption of its 4.350% Senior Notes due 2027, repaying US$600 million of outstanding principal in cash under the terms set out in the governing indenture.
- This early repayment reshapes Constellation Brands' debt profile and gives investors a fresh data point on how management is prioritizing interest costs, balance sheet flexibility, and future capital deployment.
- We will now look at how Constellation Brands' investment narrative could be influenced by this early senior notes redemption decision.
Compare Constellation Brands' early debt repayment with other balance-sheet focused opportunities by scanning our hand-picked 11 resilient stocks with low risk scores that may appeal to investors who closely watch leverage and interest costs.
Constellation Brands Investment Narrative Recap
To own Constellation Brands you need to be comfortable with a story built on beer scale, a leaner Wine & Spirits portfolio, and disciplined cash generation. The early redemption of the 4.350% Senior Notes fits into that picture as a balance sheet clean up rather than a shift in the operating playbook, so it does not change the near term demand and margin questions.
The key near term swing factor still sits in beer volumes and pricing resilience with Hispanic consumers under pressure. Tariffs and input costs sit on the other side as the main threat to margins. Redeeming US$600 million of debt may slightly ease interest expense risk, but does not resolve those core operating uncertainties.
The most relevant piece of context for this redemption is management’s plan to generate about US$9b in operating cash flow and US$6b in free cash flow from fiscal 2026 to fiscal 2028. That cash is earmarked for brewery expansion in Mexico and broader growth projects, so lowering fixed interest outflows can support funding for those commitments.
For you as a shareholder, the link between this payoff and the catalysts is about execution capacity. Constellation Brands still aims to improve Wine & Spirits margins through past divestitures and restructuring, keep beer margins strong despite tariffs and inflation, and return capital through dividends and buybacks under the US$4b authorization. A lighter debt stack gives a bit more room to pursue those plans without stretching the balance sheet further.
What The Forecasts Assume For Constellation Brands
Constellation Brands' narrative projects US$9.5 billion revenue and US$2.1 billion earnings by 2029. This is based on 1.7% yearly revenue growth and an earnings increase of about US$300 million from US$1.8 billion today.
Discover how Constellation Brands' fair value indicates a 40% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist on Constellation Brands focuses less on tariffs and more on what stronger cash generation could allow. The most optimistic analysts were already penciling in about US$9.9b of revenue and US$2.2b of earnings by 2029. With this early debt redemption now on the table, those pre news forecasts might shift again. It therefore makes sense to explore both the upbeat case and the more cautious views before deciding how this fits your own thesis.
Explore 6 other Constellation Brands fair value estimates, including one that suggests as much as 126% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Constellation Brands research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Constellation Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Constellation Brands' overall financial health at a glance.
Looking for more Constellation Brands style investment ideas?
If Constellation Brands has sharpened your focus on balance sheets, cash flow, and debt profiles, it can help to widen the lens and see how other businesses stack up on similar metrics.
- For investors who want potential upside with some quality filters already applied, scan a curated 15 high quality undiscovered gems that might not yet be widely followed.
- If resilience and financial strength are higher on your checklist, compare Constellation Brands with a list of solid balance sheet and fundamentals (23 results) that screens for sturdy fundamentals and cleaner leverage.
- Income focused investors can zero in on cash returns by reviewing a hand picked 6 dividend fortresses that prioritizes yield and consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com