
Terna (BIT:TRN) Launches ESG Linked Buyback, Is The Stock Below Fair Value?
Terna’s ESG-linked buyback puts incentives under the spotlight
Terna (BIT:TRN) has launched an ESG-linked share buyback tied to its 2026-2030 Performance Share Plan. The program extends stock-based incentives to management and employees while anchoring rewards to specific environmental objectives.
Recent trading has been softer, with Terna’s share price slipping 5.68% over the past month and 9.23% over the past quarter. Yet longer-term total shareholder return of 12.67% over one year and 74.98% over five years points to momentum that has been accumulated over time as the market weighs fresh ESG-linked incentives against existing expectations for the business.
Compare Terna’s ESG-linked approach with other grid and infrastructure players by scanning the 39 power grid technology and infrastructure stocks that are already aligning capital returns with energy transition targets.
Terna now trades below average analyst targets after a recent pullback, even as its ESG-linked incentives take shape. Is that discount reflecting healthy caution or mispricing what this grid operator delivers today?
Most Popular Narrative: 5.8% Undervalued
Terna closed at €9.20, while the most followed narrative pegs fair value closer to €9.77. That gap frames how investors may read the new ESG-linked buyback.
Ongoing and accelerating investments in grid modernization, digitalization, and resilience, including AI adoption and smart technologies, are described as positioning Terna to capture regulated asset base growth and higher-efficiency operations, supporting long-term revenue and margin expansion.
Read the complete narrative. Read the complete narrative..
Want to understand why this framework is still viewed as supporting upside from today’s price? The narrative leans heavily on steady grid expansion, protected returns, and a richer future earnings multiple built into that fair value call.
Result: Fair Value of €9.77 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Terna narrative can be challenged if heavy capex leaves leverage elevated without clear returns, or if future regulatory decisions reduce allowed profitability on its regulated grid.
Find out about the key risks to this Terna narrative.
Another View: Terna’s P/E sends a different signal
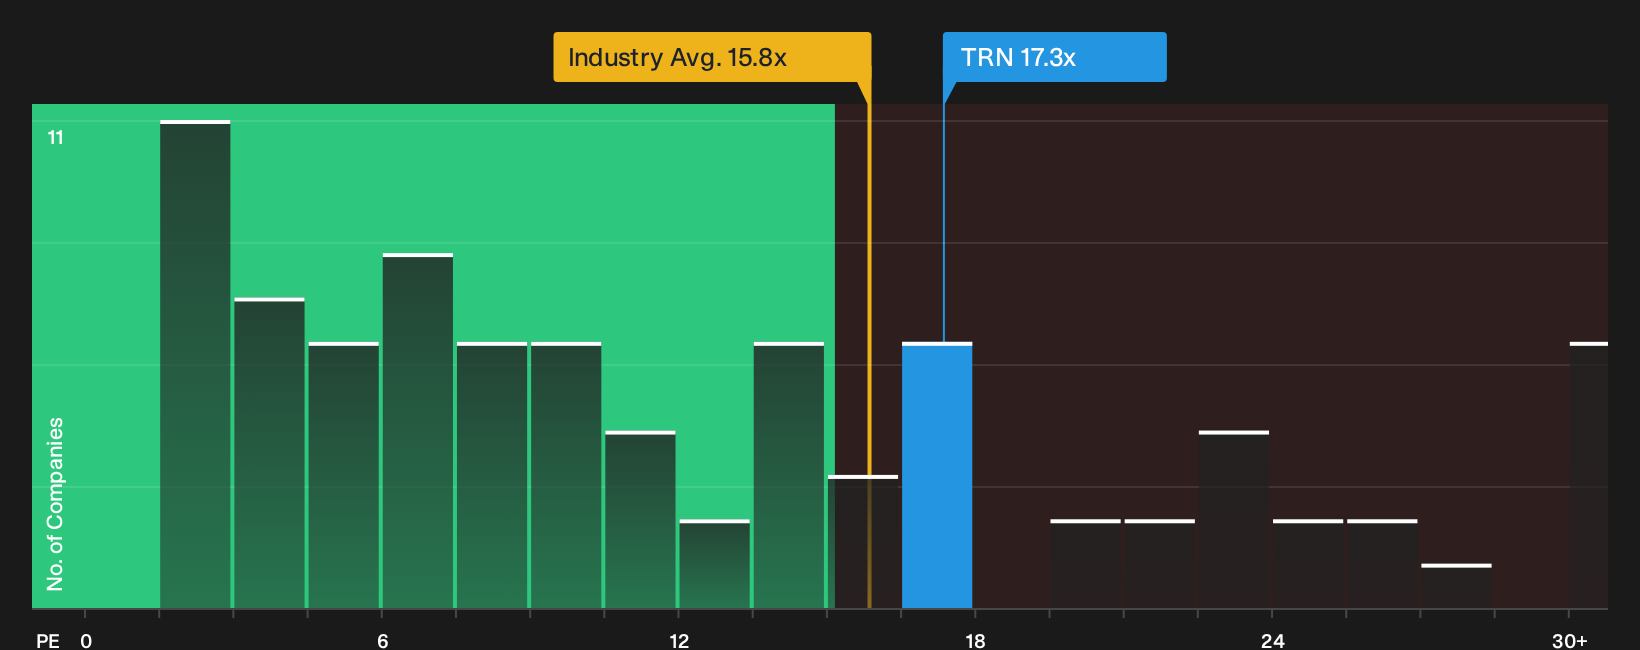
Terna looks modestly undervalued against the €9.77 fair value narrative, yet the P/E story is less generous. The stock trades on 17.3x earnings, above the European electric utilities average of 15.8x and only slightly above an estimated fair ratio of 17x, which leaves less obvious room for error if growth disappoints.
For a closer look at how this earnings multiple lines up against sector peers, and where the market could shift towards that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Terna’s valuation and incentives can feel confusing, so move quickly and weigh both sides of the story yourself with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Terna?
If Terna has sharpened your interest in regulated infrastructure, do not stop here. Use the Simply Wall Street Screener to surface fresh opportunities that match your style.
- Target quality at a discount by scanning a curated set of 183 high quality undervalued stocks that pair solid fundamentals with prices below their estimated worth.
- Secure more resilient income streams by reviewing a focused group of 161 dividend fortresses that prioritise yield alongside balance sheet strength.
- Dial down potential volatility by filtering for 99 resilient stocks with low risk scores that score strongly on financial health and historical stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com