
Solaris Energy Infrastructure (SEI) Lifts Guidance After Omega Deal While Undervalued Case Holds
Solaris Energy Infrastructure (SEI) lifted its adjusted EBITDA guidance for Q3 and Q4 2026 and outlined an initial Q1 2027 view after acquiring Omega Foundation Services to deepen its data center infrastructure work.
The guidance lift and Omega deal come after a sharp share price move, with Solaris Energy Infrastructure’s stock up 5.1% on the day and a 7 day share price return of 22.6%, alongside a 1 year total shareholder return of 119.2%. This suggests momentum has picked up again despite a 90 day share price return that declined 13.6%.
Scan other data center and power infrastructure opportunities moving on similar themes to Solaris Energy Infrastructure with our curated list of 39 power grid technology and infrastructure stocks.
For Solaris Energy Infrastructure, the sharp rebound after a recent pullback pits improved guidance and the Omega deal against a possible swing in mood. The next step is to see how today’s price compares with those fundamentals.
Most Popular Narrative: 28.5% Undervalued
At a last close of $67.42 against a widely followed fair value estimate of $94.34, Solaris Energy Infrastructure is framed as materially undervalued in the leading narrative, which leans heavily on long term power contracts and profitability assumptions.
Transition from using lower-margin, short-term third-party rental assets to Solaris-owned, high-efficiency, low-emission generation equipment in the Power Solutions segment is anticipated to expand EBITDA per megawatt and enhance overall company net margins over the next several quarters.
Read the complete narrative. Read the complete narrative.
Want to see what underpins that higher margin profile and cash flow outlook? The valuation hinges on rapid top line expansion, much fatter profit margins, and a future earnings multiple that has to compress meaningfully from today’s levels.
Result: Fair Value of $94.34 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Solaris Energy Infrastructure story leans heavily on hyperscaler contracts and high data center power demand, so any contract delays or funding snags could quickly test that undervalued thesis.
Find out about the key risks to this Solaris Energy Infrastructure narrative.
Another View: What Multiples Say About Solaris Energy Infrastructure
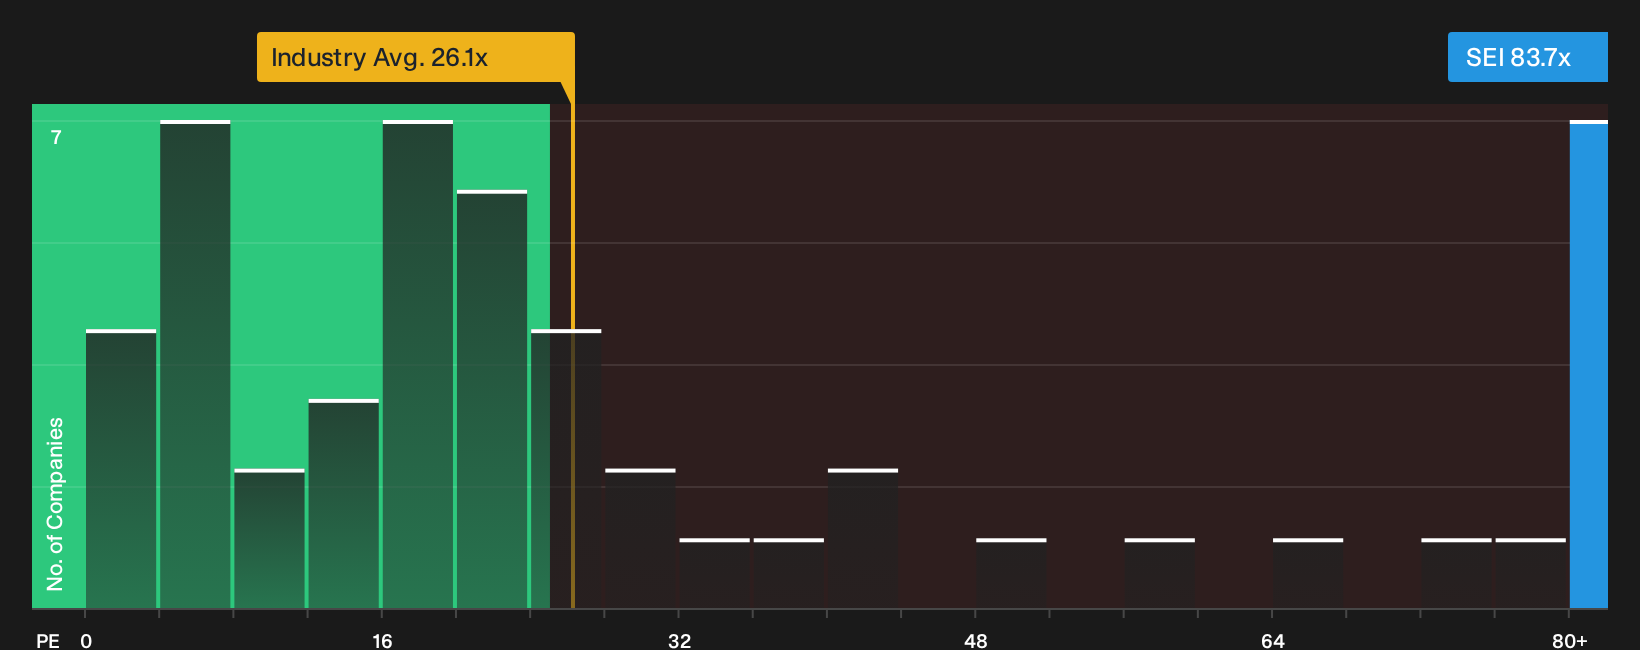
Solaris Energy Infrastructure screens very differently when you look at simple market multiples. The stock trades on a P/E of 83.7x, which is far above both the estimated fair ratio of 30.4x and the US Energy Services sector at 26.1x, as well as a 33.3x peer average.
That kind of gap suggests investors are already paying a steep price for Solaris Energy Infrastructure’s growth story, even if the narrative argues the shares are undervalued. The key question is which yardstick you trust more when sentiment cools or expectations shift.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the bullish story and the rich P/E for Solaris Energy Infrastructure? Move fast, check the key data points yourself, then weigh the 4 key rewards and 3 important warning signs.
Looking for more Solaris Energy Infrastructure style ideas?
If Solaris Energy Infrastructure has sharpened your focus on where capital might work harder, do not stop here. The strongest opportunities often appear just before most investors pay attention.
- Target income resilience by scanning a curated set of reliable payers in the 6 dividend fortresses that aim to balance yield with staying power.
- Hunt for quality at a discount through the 15 high quality undiscovered gems, where robust fundamentals meet lower market attention.
- Prioritise capital protection first and use the 11 resilient stocks with low risk scores to focus on businesses with sturdier financial profiles and less volatile histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com