
How Investors Are Reacting To MYR Group (MYRG) Expanded Credit Facility
- MYR Group entered into a new five-year Fourth Amended and Restated Credit Agreement, adding a US$690 million revolving facility plus term loans of US$150 million and C$70 million, with multi currency features, letter of credit capacity and customary covenants and security.
- The expanded borrowing capacity and option to increase commitments by up to an additional US$445 million gives MYR Group more room to fund working capital, capital spending and potential acquisitions without relying on shorter term or less flexible funding sources.
- We will now look at how MYR Group's investment narrative could be influenced by this larger, more flexible credit agreement.
MYR Group Investment Narrative Recap
To own MYR Group, you need to believe in steady demand for grid, data center and broader electrification work, and in management’s ability to keep margins intact as projects get larger. The expanded credit agreement mostly reinforces that story by giving the business more reliable funding for working capital and capital spending rather than changing it.
The key near term swing factor remains backlog quality and execution on complex T&D and C&I jobs, not the credit facility itself. The biggest risk still sits with labor cost pressure, competitive bidding and potentially uneven C&I awards, which could squeeze profitability if project mix or pricing turns against MYR Group.
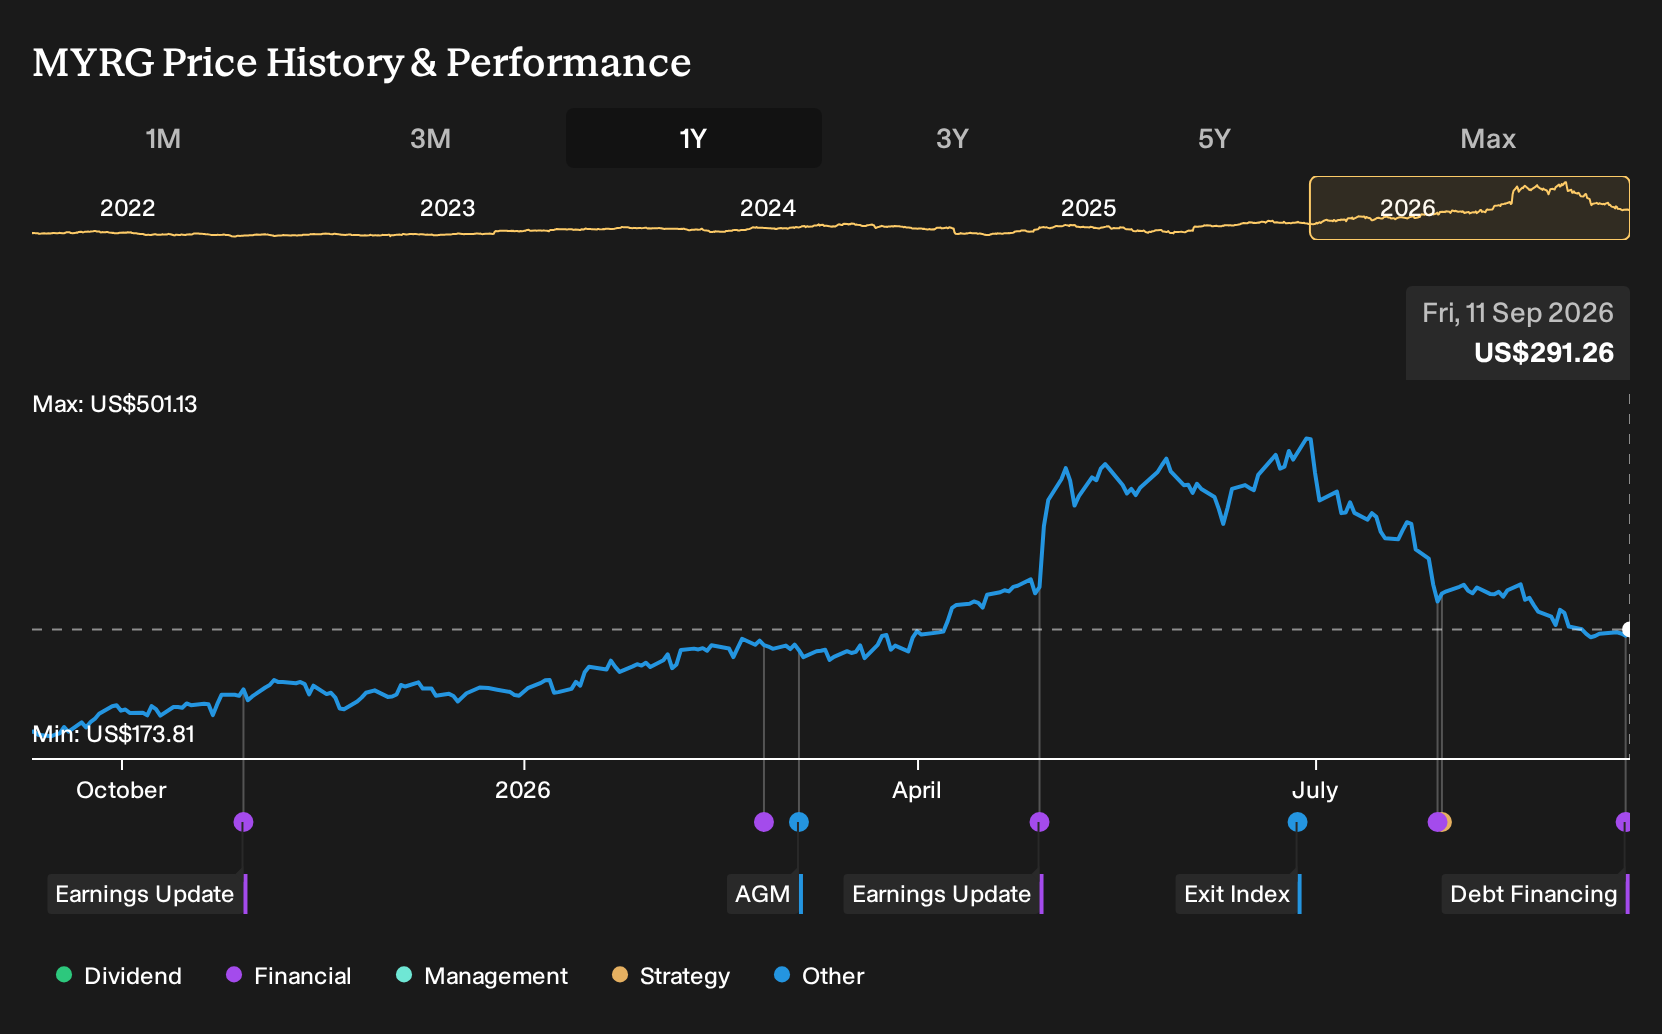
The credit agreement is most relevant when viewed next to MYR Group’s participation in investor events such as the Jefferies Renewables, Clean Energy and E&C Conference on 11 September 2026. Management now speaks to investors with a much larger, committed pool of liquidity already in place.
That combination matters for potential catalysts. A seasoned team, contract wins in grid and clean energy projects, and a balance sheet structured around committed revolving debt rather than ad hoc funding can support execution on large awards. The same leverage covenants, security package and event of default terms keep pressure on MYR Group to maintain earnings quality and interest coverage as it pursues that work.
MYR Group's current earnings sit at US$165.3 million and analysts collectively expect this to reach US$269.8 million by 2029. This implies an earnings increase of about US$104.5 million. The same consensus points to MYR Group generating US$5.6b of revenue by that year, based on an assumed 11.7% yearly revenue growth rate.
Uncover why MYR Group's fair value indicates a 49% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You see the bigger swing in the alternate MYR Group story around timing risk. The most pessimistic analysts were already assuming about US$5.9b of revenue and US$298.5m of earnings by 2029 before this new credit deal. That gap versus consensus shows how far opinions can stretch, and why fresh financing news could prompt some to rethink their timelines.
Explore 4 other MYR Group fair value estimates, including one that suggests as much as 31% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your MYR Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for MYR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MYR Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond MYR Group?
If the MYR Group story has sharpened your thinking about grid spending and balance sheet flexibility, it can be useful to compare it with other businesses that meet clear financial filters. The Simply Wall St Screener can help you scan the market quickly, so you spend more time assessing narratives and less time sifting through raw data.
- If you want potential mispricing with solid fundamentals at the center of your research process, start with a curated 32 high quality undervalued stocks that pairs quality financial profiles with compressed valuations.
- If you prefer resilience and capital preservation to be front and center, focus on companies screened for 11 resilient stocks with low risk scores that score well on financial strength and earnings stability tests.
- If you are looking for financially sound operators that might be flying under the radar, uncover a 15 high quality undiscovered gems that combines healthier balance sheets with supportive operating metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com